Privia Health Beats And Raises Again, But Slowing Third-Quarter EBITDA Growth And Softer Cash Conversion Complicate The Story
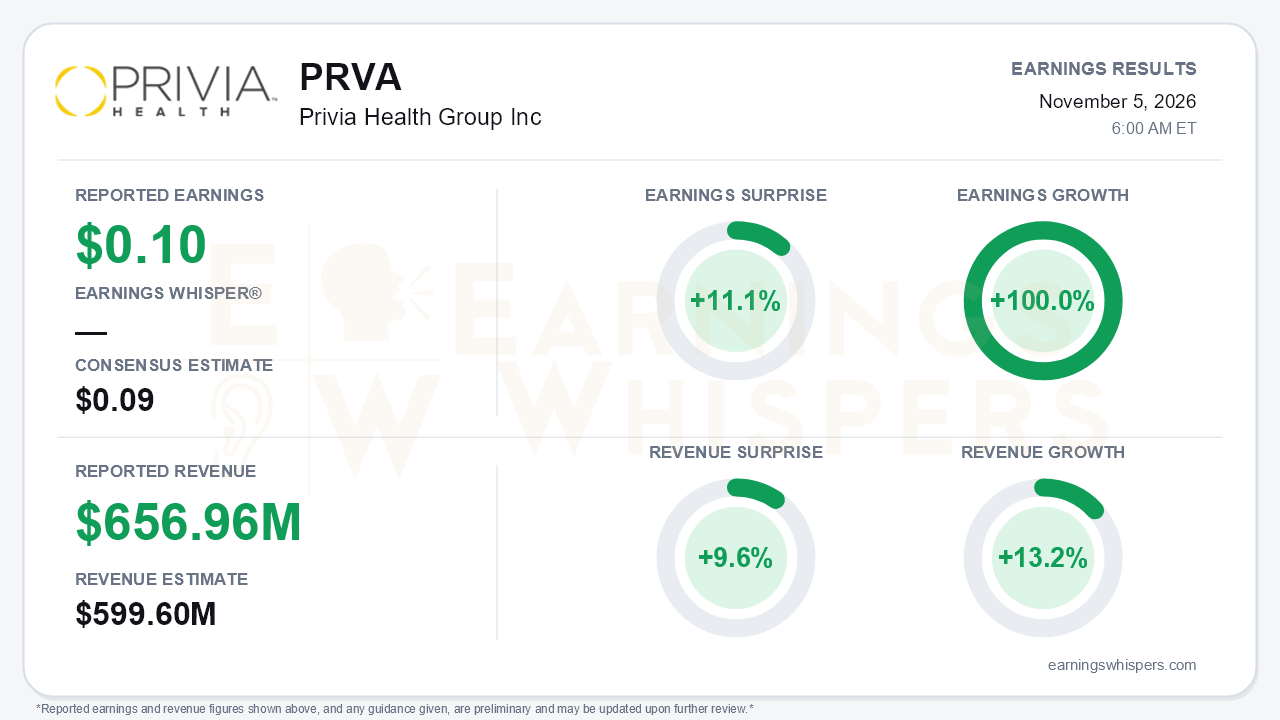
Privia Health Group delivered another beat-and-raise quarter, reporting third-quarter earnings of $0.10 per share against a $0.09 consensus, an 11.1% surprise. Revenue of $656.96 million topped the $599.6 million estimate by 9.6%. Earnings grew 100.0% year over year and revenue rose 13.2%. Management lifted full-year 2026 guidance above the initial high end for every key financial metric, its third straight upward revision. Beneath the headlines, though, quarterly profit growth was far more modest than the year-to-date figures suggest, and the cash outlook moved the other way. That is the central tension.
The quality of the beat deserves scrutiny. GAAP net income nearly doubled to $13.5 million, but a large share of that came from below the operating line. Stock compensation fell to $14.0 million from $19.0 million, and net income attributable to non-controlling interests dropped to $1.1 million from $2.9 million. On an adjusted basis, EPS rose a more measured 10.5% to $0.21. Adjusted EBITDA grew just 6.3% to $40.6 million, and Platform Contribution rose only 4.8%. Both lagged their nine-month growth rates of 21.9% and 16.8%. Adjusted EBITDA margin on care margin slipped to 29.4% from 30.5% a year ago. Shared savings revenue fell to $68.8 million from $80.0 million. Revenue growth of 13.2% was also well below the 19.7% nine-month pace, so top-line growth decelerated even as GAAP earnings growth accelerated. The call analysis adds that revenue beats are running ahead of care margin and EBITDA beats partly because of the Florida TIN consolidation, which flatters GAAP revenue.
The operating metrics, by contrast, strengthened. Implemented providers grew 12.2% to 5,893, up from 10.1% growth in the second quarter, on 249 sequential additions versus 109 in Q2. Attributed lives climbed 19.2% to 1.676 million, with CMS Medicare lives up 59% and commercial lives up 11.8%. Practice collections rose 9.4% in the quarter and 12.0% year to date. The guidance path shows how much the year has improved:
- Adjusted EBITDA guidance of $154–157 million now implies 23.9% growth at the midpoint, versus roughly 20% at the original $150 million midpoint.
- Practice collections growth is now 13.1% at the midpoint, versus 6.6% initially.
- Care margin growth is now 16.3% at the midpoint, versus 13% initially.
- Providers are guided to the high end, around 6,000.
Management's tone grew noticeably more confident. Executives described a 30% EBITDA-to-care-margin ratio as very near term and the high end of a 30–35% range as achievable. For the first time, they signaled a lower bar for share buybacks absent M&A, citing $800–900 million of deployment capacity, a shift from earlier "last resort" language. They also continued to deploy capital: the roughly $36 million purchase of Cano Health's American Choice Healthcare MSSP ACO adds more than 36,000 lives across ten existing and three new states starting January 2027. Management expects the deal to add to 2027 lives and EBITDA. Executives also floated larger adjacent deals in areas such as ASCs, ancillaries and in-home or virtual care. The 2025 MSSP settlement expected in November is a nearer-term event to watch.
Bears have legitimate ammunition on cash. Operating cash flow was negative $19.4 million through nine months, compared with positive $35.9 million a year earlier, as receivables jumped. Free cash flow conversion guidance has slid from 80% to 70–80% to about 70%, and management now frames 70–75% as the long-term target as a full cash taxpayer. The year-end cash target fell to at least $520 million from about $600 million originally, partly because of the acquisition and settlement timing. The Montana exit, covering 69 providers and about $23 million in collections, is small and guided as EBITDA-neutral. Policy risk remains, including the physician fee schedule, the REACH-to-LEAD transition and attribution shifts.
The market setup is still repairing. Shares fell to a 52-week low of $18.92 in late September, then rebounded 18.4% to $22.40 ahead of the report. That leaves the stock up 7.2% since the post-Q2 open, 3.2% below its inter-earnings high and just 1.1% under its 200-day moving average. Investor sentiment remained negative but improved modestly, moving from -0.27 to -0.21. Sequential growth, momentum and AVWAP trend readings are positive, while the broader price trend remains negative.
The bottom line is that Privia keeps raising its outlook, adding providers and lives faster, and sounding more confident about margins and capital returns. However, the third quarter itself showed single-digit EBITDA growth, revenue flattered by consolidation, and a weaker cash trajectory. Investors who are still cautious will want to see the fourth quarter deliver the acceleration the raised guidance implies, along with a clean MSSP settlement, before treating this as more than a well-executed raise.
Read our earnings preview for Privia Health Group Inc: https://www.earningswhispers.com/article/PRVA/22172
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-02 | |
| Oct-28 | |
| Oct-08 | |
| Sep-18 | |
| Aug-18 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 | |
| Jul-07 | |
| May-27 | |
| May-07 |
