Gibraltar's OmniMax Synergies Face A Soft Housing Market As Stock Sinks Toward Range Lows
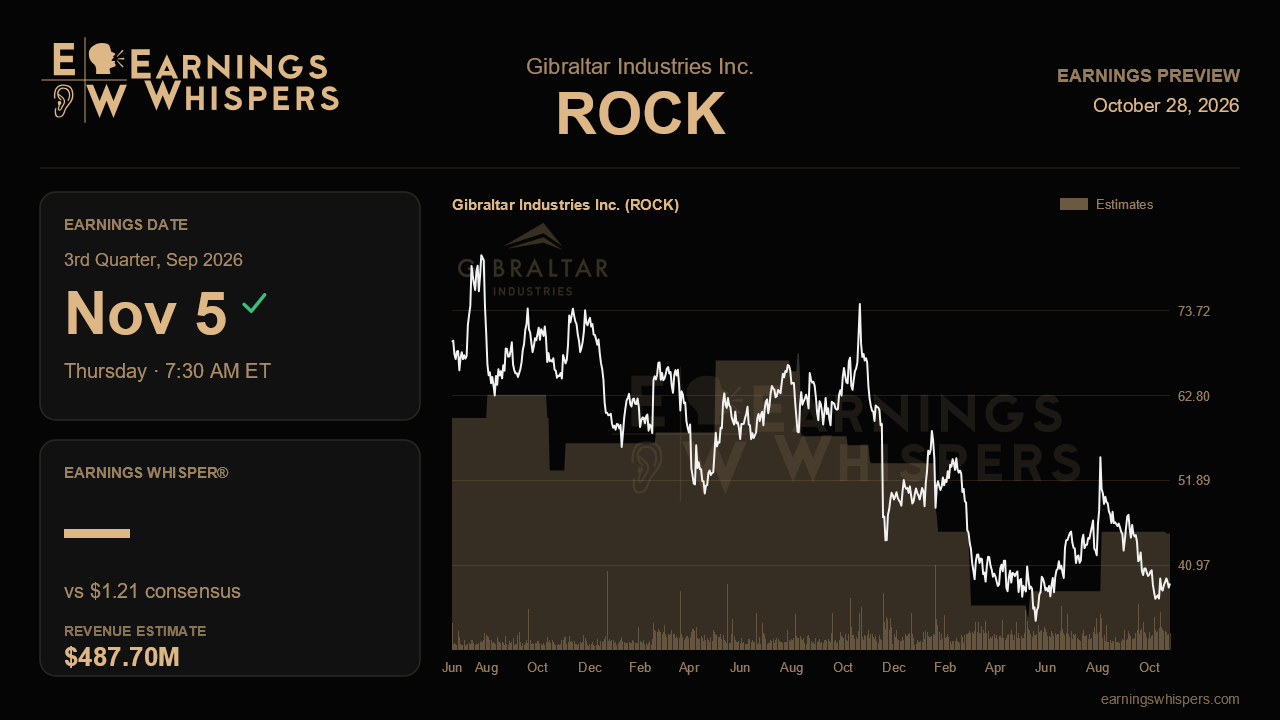
Gibraltar Industries heads into its third-quarter report with an awkward contradiction. Last quarter, management showed that its OmniMax integration was finally paying off: organic growth turned positive, margins jumped sequentially, and synergy targets rose for a third straight call. Since then the stock has fallen about 26% while the S&P 500 was essentially flat. The market is treating the self-help story with deep skepticism, and this report needs to show whether integration gains can keep outrunning a residential market that management itself says is getting weaker.
The Street expects earnings of $1.21 a share on revenue of $487.7 million. Revenue would be up nearly 57% from a year ago, but that jump mostly reflects the OmniMax acquisition rather than underlying demand. Earnings growth tells the more sober story: a projected 6.1% gain over last year's $1.14. Sales are also expected to slip from the second quarter's $509.5 million, consistent with a seasonally softer period and a weak end market. Management recently reaffirmed full-year adjusted EPS guidance of $3.65 to $4.05 on revenue of $1.76 billion to $1.83 billion. The $3.80 consensus sits near the midpoint for earnings, but the $1.76 billion revenue estimate is pinned to the bottom of the range. In other words, analysts already assume volume will disappoint and are betting that margins and synergies make up the difference.
That makes margins the key test. Residential EBITDA margin rose 340 basis points sequentially to 19% last quarter, and total adjusted EBITDA margin reached 17.3%. Holding most of that gain on lower seasonal volume would confirm that synergies are structural rather than a function of a strong spring. Management raised its 2026 synergy commitment to $29.4 million executed and $17 million realized and said integration was running close to a year ahead of plan. Investors should want to see realized savings keep climbing and new items, such as the freight and participation-gain synergies identified last quarter, start to show up. The risk is price-cost. Aluminum, steel and fuel inflation forced the company to keep chasing costs last quarter, and margin slippage here would undercut the central argument for the stock.
Demand is the other major variable. Management estimated true residential end-market demand was down mid-single digits, with retail point-of-sale down 8% to 10% in the second quarter, and expects that softness to last through the second half. The positive 5% residential organic growth in the second quarter came partly from shingle restocking and pre-buying ahead of price increases, so some payback is plausible. AgTech is another weak spot. Its organic growth turned positive last quarter, but backlog fell 34% year over year to $66.2 million, which raises the risk of a gap in second-half volume. Rebuilding that backlog would ease concerns. Further erosion would suggest the segment's recovery was premature.
The new supply agreement covering more than 1,700 locations, including 630 net new ones, is mostly a 2027 story, since shipments begin late in the fourth quarter. This report should still show whether the rollout is on schedule and whether startup costs are weighing on near-term margins. With net leverage at 3.9x and the 2.5x target not expected until early 2028, cash generation and debt paydown also deserve attention.
Sentiment has improved to modestly bullish from clearly bearish before the last report, yet the stock trades at $38.61. That is well below its 200-day average of $43.47 and only a few dollars above the $35.63 low of its post-earnings range. Expectations embedded in the share price are therefore subdued. The question that decides whether the narrative holds is simple: can Gibraltar sustain its newly expanded margins and reaffirm guidance while volumes soften? If it can, the selloff looks excessive. If margins slip back toward first-quarter levels, the market's doubts will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-22 | |
| Oct-15 | |
| Sep-17 | |
| Aug-14 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-22 | |
| Jul-16 | |
| Jul-01 | |
| Jun-03 | |
| May-08 | |
| May-07 | |
| May-07 |
