Gibraltar Misses And Slashes 2026 Outlook As Roofing Slump And Agtech Delays Overwhelm Rapid OmniMax Synergy Gains
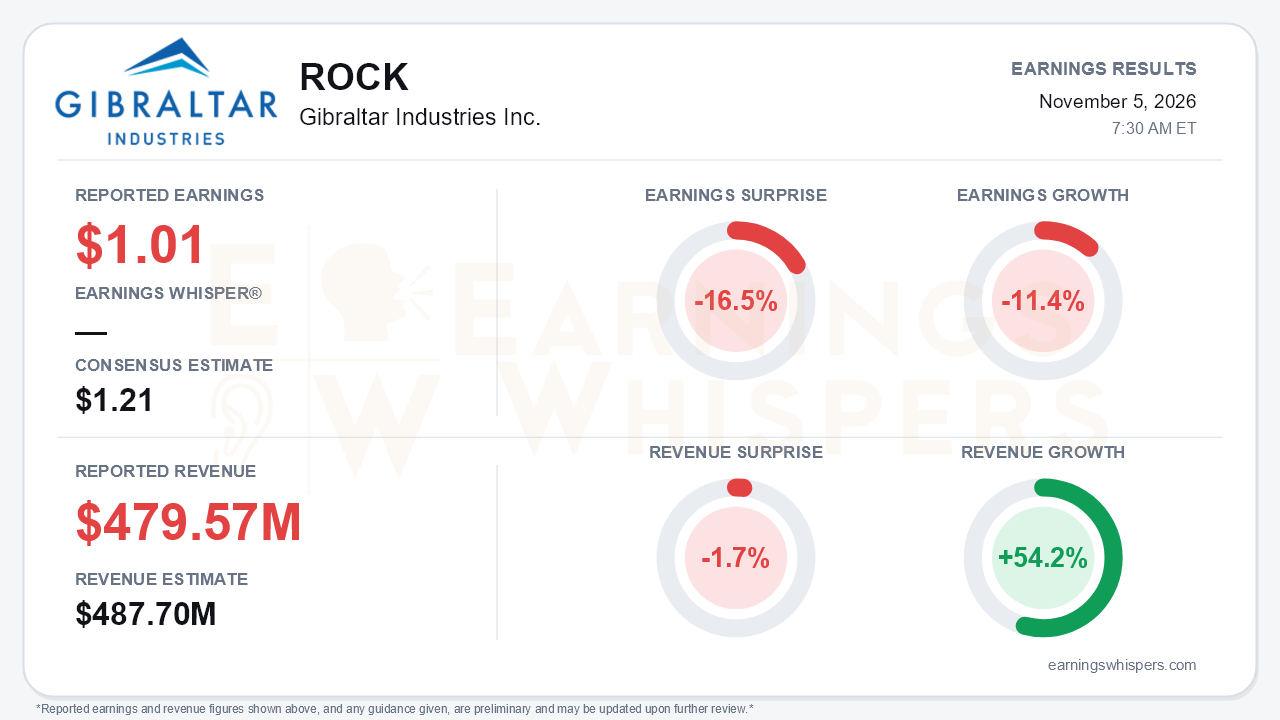
Gibraltar Industries (NASDAQ: ROCK) delivered a quarter where the acquisition story kept working but the earnings story did not. Adjusted EPS of $1.01 missed the $1.21 consensus by 16.5% and fell 11.4% from a year ago. Revenue of $479.57 million rose 54.2% on the OmniMax acquisition but still came in 1.7% below the $487.7 million estimate. The more consequential news was the guidance reset. Management cut 2026 adjusted EPS from $3.65–$4.05, a range reaffirmed in each of the three prior reports, to $2.70–$2.85 before reclassifying Infrastructure and $2.25–$2.40 for continuing operations. That is the central tension. Integration is running ahead of plan, but the end market is deteriorating faster than the plan assumed, and investors are being asked to trust a forecast that has now proven too optimistic.
The quality of the quarter deserves scrutiny beneath the 62.5% jump in adjusted EBITDA to $83.5 million. That gain is almost entirely acquired. Leverage from the OmniMax deal brought $21.5 million of quarterly interest expense, compared with essentially none a year ago, and that is why adjusted net income fell even as EBITDA surged. GAAP EPS from continuing operations dropped to $0.69 from $1.11 after $9.9 million of integration and restructuring costs. Cash generation was the weakest link. Third-quarter free cash flow was just $8 million, or 1.7% of sales, versus 15.6% a year earlier. Full-year free cash flow guidance collapsed from about 8% of sales to roughly 1% for continuing operations, while net debt sits at $1.2 billion and leverage held at 3.9x.
Operationally, Residential genuinely outperformed a bad market. The company estimated shingle shipments fell 13% year over year and 22% sequentially after demand broke in August. Against that backdrop, Residential grew 3.1% organically and pro forma building products grew 4.1%. Adjusted EBITDA margin held at 18.9%, roughly flat with the second quarter despite a 6.3% sequential sales decline. The trajectory, however, is clearly lower:
- Organic growth slowed from 5% in the second quarter, and pro forma building products growth decelerated from 15.5%.
- Residential margin was down 140 basis points year over year and missed internal expectations.
- Steel, diesel and freight inflation is running ahead of price recovery into the fourth quarter.
- Management now assumes the second-half market is down about 15%, versus mid-single digits three months ago.
- The call flagged possible short-term pricing aggression from competitors.
Agtech is a similar split picture. Adjusted EBITDA margin expanded 380 basis points to 13.2%, but permit delays pushed roughly $40 million of revenue into 2027. Backlog fell 55% to $45.6 million, down from $84 million in the first quarter. A post-quarter $75 million controlled-environment agriculture award and clearing permits offer some relief. Notably, management also floated Agtech as a possible future divestiture candidate.
The constructive catalysts are real but mostly structural rather than near-term earnings drivers:
- **Synergies:** The run-rate was raised to $36.5 million, already surpassing the original three-year $35 million target only eight months in.
- **D.S. Brown sale:** The $208 million sale to Saint-Gobain, at roughly 10x trailing EBITDA, should lower year-end net debt to below $1 billion.
- **Lowe's:** Gibraltar was named a Lowe's Building Products Vendor Partner of the Year, and a 1,700-location trims and flashings award begins late in the fourth quarter, though it is primarily a 2027 contributor.
Bears have legitimate ammunition on the other side. CFO Joe Lovechio is departing mid-transformation. A roughly $30 million tax refund slipped to 2027 amid an IRS exam. Special charges were raised to $60 million from $50 million. Management's tone also shifted from reaffirming to defensive, emphasizing controllables and scenario planning for 2027.
The market setup is more complicated than the miss implies. Shares have fallen 16.2% since the open after the August report, from $51.98 to $43.58 heading into this release. They are 24.3% below the inter-earnings high of $57.58 set on the day of that report. Yet the stock had already rebounded 22.3% from its October 14 low of $35.63, which came one day before the D.S. Brown sale was announced. Shares entered the print just 1.2% above the 200-day moving average. Investor sentiment improved meaningfully, moving from clearly negative (-0.29) to roughly neutral (+0.01). That suggests expectations had been rebuilding around the divestiture and deleveraging story before management delivered a much lower outlook.
The bottom line is that Gibraltar is executing the parts of its strategy it controls: synergies, portfolio simplification and debt reduction. The parts it does not control, residential volume, input inflation and agtech permitting, are moving against it faster than management anticipated. A guidance cut of this size after three reaffirmations, combined with negligible free cash flow, elevated leverage and a CFO transition, means credibility now has to be rebuilt quarter by quarter. Deleveraging progress and Residential margin defense will matter more than synergy headlines from here.
Read our earnings preview for Gibraltar Industries Inc.: https://www.earningswhispers.com/article/ROCK/22178
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-22 | |
| Oct-15 | |
| Sep-17 | |
| Aug-14 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-22 | |
| Jul-16 | |
| Jul-01 |
