Targa Must Show Permian Volumes Can Offset Fading Marketing Gains As Shares Near Highs
Targa Resources heads into its third-quarter report with a problem most midstream companies would happily trade for. Last quarter's results were so strong, helped by an unusually rich stretch of marketing and optimization profits, that the coming numbers will almost certainly look softer on a sequential basis. The real question is whether record Permian volumes and a busier downstream system can fill the gap management itself warned about, and whether the full-year guide still holds near its top end.
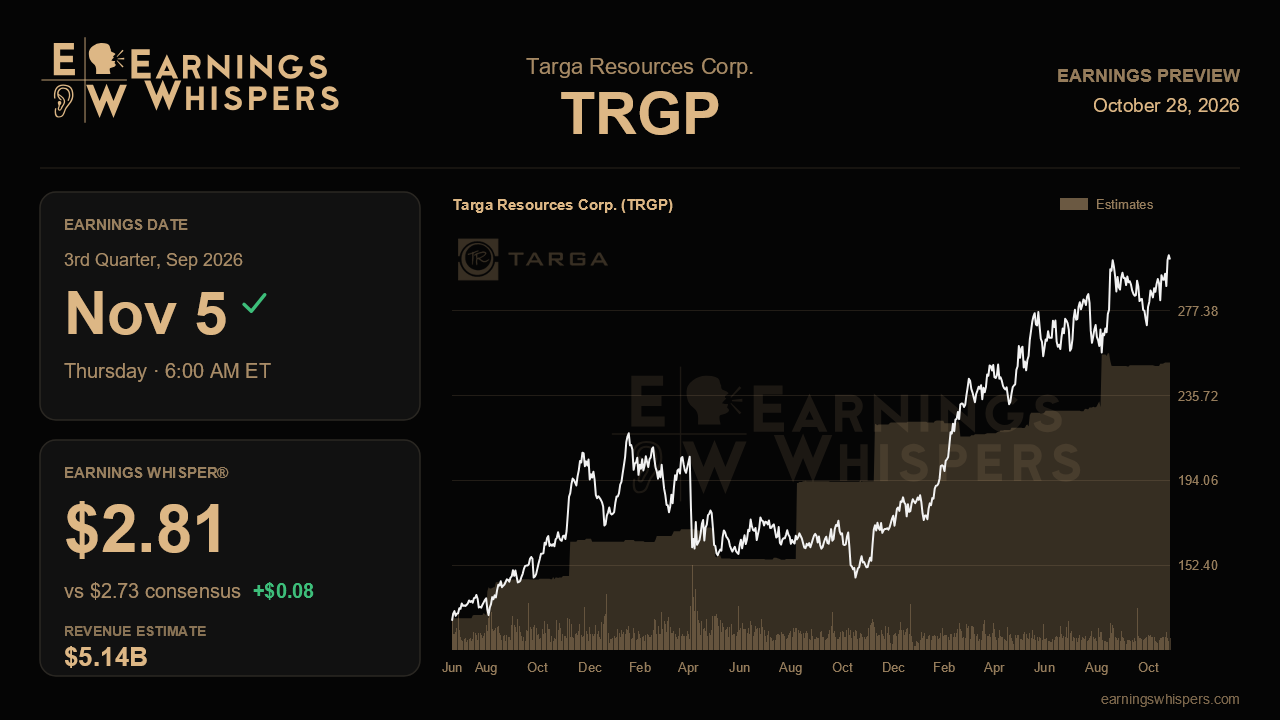
Wall Street expects earnings of $2.73 a share on revenue of about $5.14 billion, which would mark growth of roughly 24% on both lines from a year ago. That is strong growth by any standard, but it also represents a meaningful step down from the $3.54 a share Targa earned in the second quarter. The Earnings Whisper sits a bit higher at $2.81, suggesting the more engaged crowd sees modest room for upside but not a dramatic beat. In other words, the bar is elevated year over year yet sensibly reset relative to the spring quarter's windfall.
That reset traces directly to the last conference call. Management lifted its 2026 adjusted EBITDA outlook to the top end of a $5.7 billion to $5.9 billion range, the second upgrade this year after starting at $5.4 billion to $5.6 billion. With roughly $3 billion already banked in the first half, hitting the top end implies second-half EBITDA somewhat below the $1.6 billion run rate of the second quarter. Management was explicit about why: marketing gains, which totaled about $250 million in the first half versus roughly $150 million for all of 2025, should moderate as the Waha basis narrows, and the company assumed little further help from that source. If third-quarter EBITDA lands comfortably around or above $1.45 billion, the guide looks conservative. A figure that leans heavily on leftover optimization rather than volumes would make the quality of the beat harder to trust.
The volume story is where the narrative can be validated. Permian throughput hit a record 7.2 Bcf/d last quarter, up about 450 MMcf/d sequentially despite price-related shut-ins of 200 to 400 MMcf/d. With Hugh Brinson Phase 1 and the GCX expansion relieving takeaway constraints, the East Driver plant running ahead of schedule, and management describing July and August as strong, another clear sequential increase in Permian volumes is the most important evidence to look for. Downstream records should follow if the system is working as designed: NGL transport of 1.1 million barrels a day, fractionation of 1.2 million, and LPG exports of 14.8 million barrels a month, aided by the new Train 11 fractionator and Delaware Express pipeline. Any update on long-term export contracts tied to Middle East demand, or on data-center gas supply talks, would add color to the 2027 growth runway behind Speedway and the LPG expansion. On the cautious side, Targa expected to remain below fee floors in aggregate through the third quarter, so per-unit gathering and processing margins are likely flat rather than expanding, and stretched equipment lead times of 18 to 24 months could nudge capital spending higher.
Investors have clearly bought into the story. The stock has climbed about 12.8% since the last report while the S&P 500 was essentially flat, and at around $302 it sits roughly 18% above its 200-day moving average and less than 2% below its post-earnings high of $307.94, effectively testing a breakout. Sentiment has also improved, moving from a 9.4% bearish reading before last quarter to a nearly neutral 2.0% bearish. That combination means a clean quarter may already be partly priced in.
Ultimately, this report comes down to substitution. If volume growth and downstream throughput visibly replace the fading marketing tailwind and management reaffirms or lifts the top-end guide, the repeatable side of Targa's story wins out. If the quarter instead shows that the first-half outperformance was doing more of the work than it appeared, a stock sitting near its highs has little cushion.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-13 | |
| Sep-22 | |
| Sep-16 | |
| Aug-26 | |
| Aug-25 | |
| Aug-25 | |
| Aug-18 | |
| Aug-17 | |
| Aug-06 | |
| Jul-31 | |
| Jul-21 | |
| Jul-16 | |
| May-29 | |
| May-07 |
