Targa Beats As Record Permian Volumes Drive Fourth 2026 Outlook Upgrade, But Fading Marketing Gains And Higher Capex Temper The Quarter
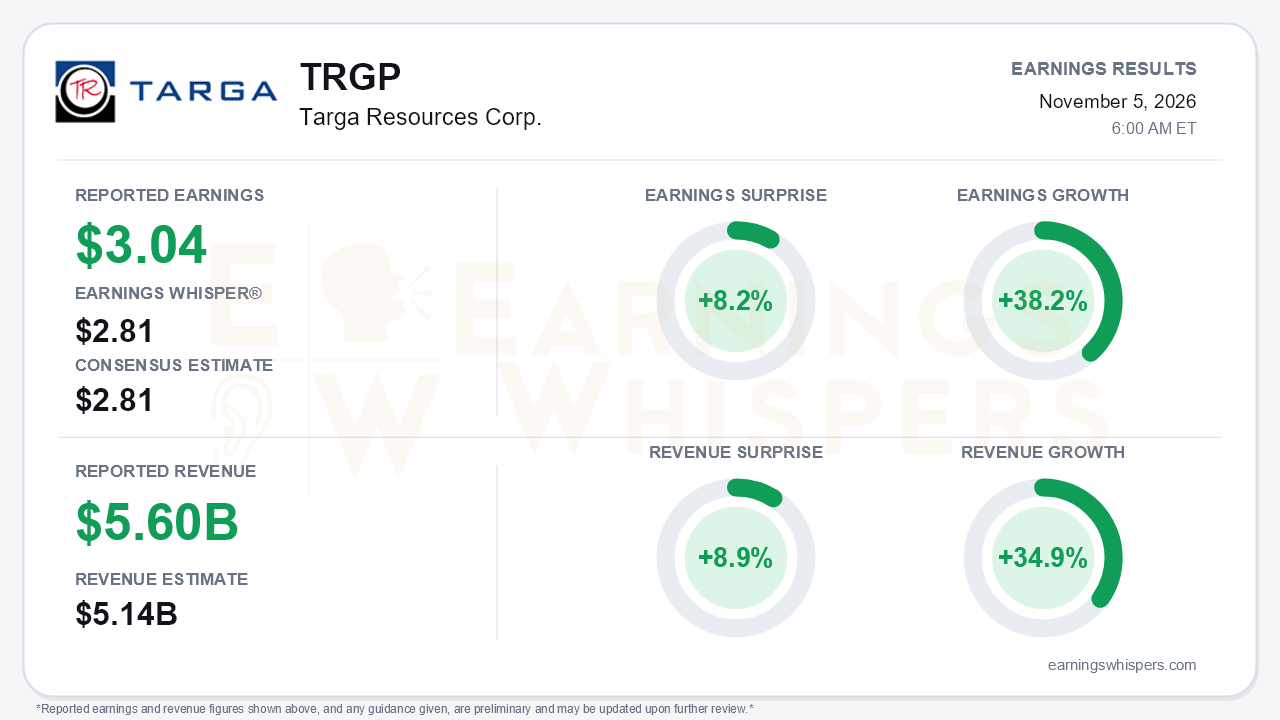
Targa Resources (NYSE: TRGP) delivered a clean headline beat for the third quarter. Earnings of $3.04 per share topped both the $2.81 consensus and the $2.81 Earnings Whisper number by 8.2%. Revenue of $5.599 billion exceeded the $5.14 billion consensus by 8.9%. Earnings grew 38.2% year over year and revenue rose 34.9%. Net income attributable to Targa climbed to $658 million from $478 million. The more consequential development, however, was not the quarter itself. It was the forward picture. Management lifted 2026 adjusted EBITDA guidance again, to at least $6.0 billion. It also unveiled a 20-year integrated agreement with ExxonMobil, sanctioned a 14th fractionation train, and signaled years of double-digit Permian growth. The central tension is that the long-term story strengthened just as the sequential quarter softened and the capital bill grew.
The quality of the beat deserves scrutiny. Revenue growth was flattered by commodity prices. Commodity sales jumped 36%, and $801.5 million of that increase came from higher NGL, natural gas and condensate prices. Much of it washed through product purchases, which rose 43%. Fee-based midstream revenue grew a still-healthy 29%, which is the better measure of underlying expansion. GAAP earnings also benefited from a $63.1 million unrealized mark-to-market hedge gain in the Other segment. That gain was partly offset by a $22.6 million charge tied to the Dovetail contingent consideration. On a cleaner basis, adjusted EBITDA of $1.504 billion rose 18% year over year. That trails the 25% pace for the first nine months and represents a 6% sequential decline from $1.603 billion in the second quarter. The headline beat therefore overstates the momentum in core cash earnings this quarter.
The sequential dip had identifiable causes. The core physical business did not soften. Permian inlet volumes hit a record 7.54 Bcf/d, up 14% from a year ago and roughly 5% sequentially. The Delaware led with 20% growth. On the call, management noted that year-to-date Permian growth of 13% compares with roughly 7% for the basin. NGL transportation and fractionation volumes also set records at 1.17 MMbbl/d and 1.26 MMbbl/d. Gathering and processing adjusted operating margin rose 22% year over year. Two things fell. Logistics marketing margin dropped as optimization opportunities faded; the call put first-half upside from those opportunities at roughly $250 million. LPG export loadings also slipped to 13.7 MMbbl per month from a record 14.8. Those are lower-quality, more volatile earnings streams. Their retreat matters less than the fee-based volume engine, which kept accelerating.
The catalyst slate is substantial. The ExxonMobil contracts underpin three new Delaware plants (Wrangler, Ranger and Ranger II). Targa is also ordering long-lead items for three more plants likely needed in 2028 or early 2029. Train 12, the Bull Run Extension and Copperhead all arrived ahead of schedule, and Yeti and Yeti II were pulled forward to mid-2027. Management also flagged possible margins above fee floors in late 2026 and 2027 on stronger Waha and NGL pricing. Bears have legitimate ammunition, though. Net growth capex rose to about $5.0 billion from $4.5 billion, and 2027 spending will stay elevated. That keeps the free cash flow inflection pointed toward 2028. Third-quarter adjusted free cash flow shrank to just $33.6 million from $172.8 million. Liquidity slipped to $2.9 billion from $3.2 billion, while leverage held at 3.4x. Management also conceded that ExxonMobil "drove a hard bargain" on pricing, and the finance chair changed hands. Even so, management plans to recommend a 20% dividend increase to $6.00 per share for 2027, a clear signal of confidence in cash generation.
Investor sentiment entering the report remained slightly negative but improved, moving from -0.09 to -0.04. That is a modest shift rather than a conversion. Shares have gained 6.2% since the open after the August report and sit about 9% above the 200-day moving average. The stock also pulled back roughly 10% from the 52-week high of $316.60 set on October 30, so it entered earnings mid-range rather than stretched at the highs. The Earnings Whispers trend signals are uniformly positive, with sequential growth and momentum both constructive.
The bottom line is that Targa's quarter was better than the 6% sequential EBITDA decline suggests and less pristine than the 8% EPS beat implies. Price-inflated revenue and hedge gains padded the headline, and volatile marketing income faded. The fee-based Permian franchise, however, posted record volumes and secured a marquee long-term customer. Management also raised the outlook for a fourth time this year. The debate now shifts from whether Targa can grow to whether investors will tolerate another two years of heavy spending before free cash flow catches up with the dividend ambitions.
Read our earnings preview for Targa Resources Corp.: https://www.earningswhispers.com/article/TRGP/22198
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-13 | |
| Sep-22 | |
| Sep-16 | |
| Aug-26 | |
| Aug-25 | |
| Aug-25 | |
| Aug-18 | |
| Aug-17 | |
| Aug-06 | |
| Jul-31 | |
| Jul-21 | |
| Jul-16 |
