AGNT Must Turn Breakeven Into Profit On Lighter Revenue As Expectations Swing Bullish
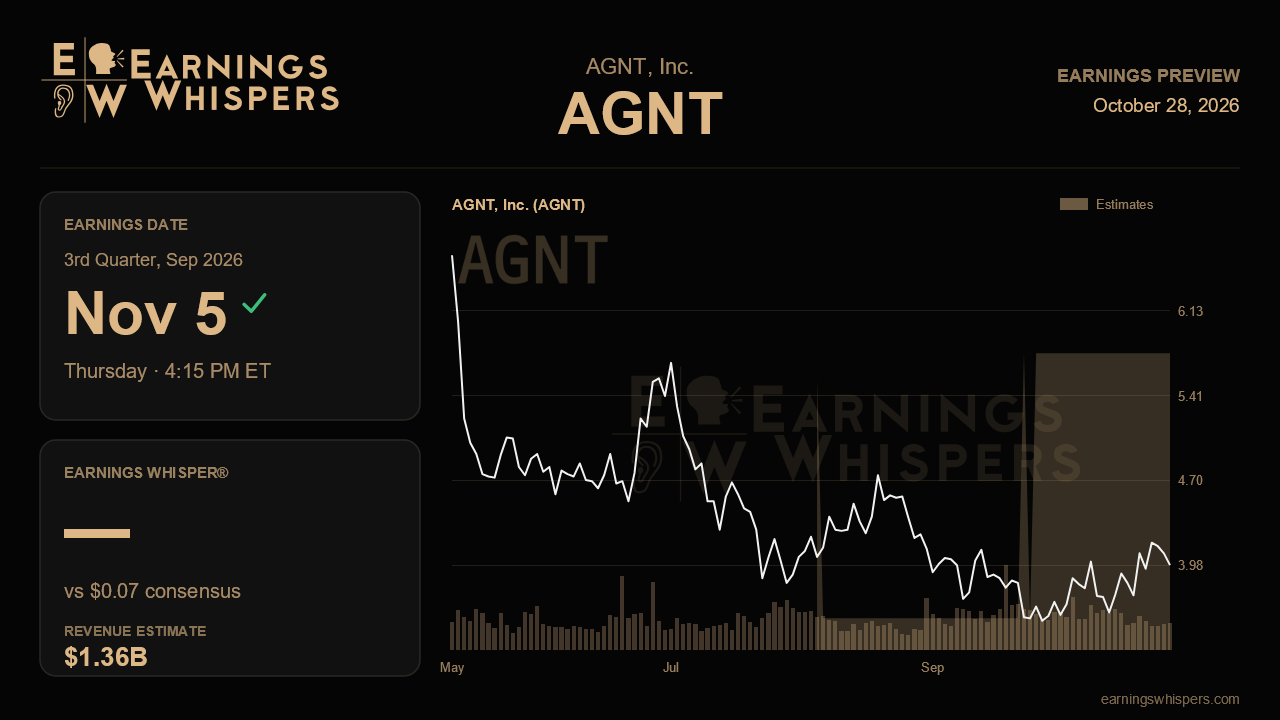
The puzzle heading into AGNT's third-quarter report is arithmetic. Last quarter the parent of eXp Realty generated $1.45 billion in revenue and essentially broke even, posting earnings of $0.00 per share. This time Wall Street is looking for less revenue and more profit: consensus calls for $1.36 billion in sales and earnings of $0.07 per share. For a brokerage whose model passes most commission dollars through to agents, squeezing a meaningful profit out of a smaller top line is not a trivial ask. That makes the report less about volume than about whether the company has real control over the costs that sit between gross commissions and the bottom line.
Management has given investors a clear frame. The company guided to third-quarter revenue of $1.35 billion to $1.45 billion and full-year 2026 revenue of $4.85 billion to $5.15 billion, an outlook the market read as in line. The Street's quarterly estimate sits just above the bottom of that range, which suggests analysts are leaning conservative on near-term transaction activity. The annual picture tells a different story. At $5.02 billion, the full-year consensus sits in the upper half of guidance, implying that analysts expect a stronger finish to the year than the quarterly number alone would suggest. Those two estimates are not contradictory, but they set up a specific test. A third-quarter print near the low end paired with an unchanged annual range would quietly lean more heavily on the fourth quarter, and any trimming of the full-year outlook would expose the gap between the Street's yearly figure and management's comfort zone.
Revenue, then, is likely to be judged against a forgiving bar, while profitability faces a stricter one. Moving from breakeven to $0.07 on roughly $90 million less revenue requires either a better split between what the company keeps and what it pays agents, tighter operating expenses, or both. Evidence that would validate the story includes a stable or improving revenue retention rate on each transaction, operating expenses that fall alongside revenue rather than lagging it, and commentary indicating that the agent network remains productive despite a softer quarter. Signs that challenge it would include profit landing near zero again, a margin that compresses as revenue dips, or guidance language that hints at higher spending on technology, franchising through NextHome, or the company's other ventures.
The mood around the stock has shifted noticeably. Sentiment going into the last report tilted slightly bearish; it now reads as strongly bullish. Shares have risen 4.2% since the prior release while the S&P 500 slipped 0.8%, a five-point edge that shows the market has rewarded the company modestly rather than punished it. At $3.98, the stock trades comfortably above its 200-day moving average of $2.61, a sign the longer-term trend remains constructive. Context matters, though. The post-earnings range of $3.40 to $4.79 is well below the prior quarter's band of $3.69 to $6.92, and the current price sits roughly in the middle of the newer range, nowhere near a breakout. The stock has stabilized after a steep retreat, not reclaimed its highs.
That combination of rebuilt optimism and a lower price base makes the profit line the decisive variable. Revenue near the bottom of guidance would likely be tolerated, since that is roughly what analysts already assume. What the improved sentiment is really betting on is operating leverage: proof that AGNT can turn a cyclical, low-margin brokerage business into consistent earnings even when transaction volume eases. If the company delivers a profit near or above consensus and holds its full-year range, the bullish turn has substance behind it. If earnings again hover around breakeven, the recent enthusiasm will look premature.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-27 | |
| Oct-24 | |
| Aug-04 | |
| Aug-04 | |
| Jul-14 | |
| Jul-02 | |
| Jun-11 | |
| May-27 | |
| May-18 | |
| May-11 | |
| May-11 |
