AGNT Misses On EPS And Cuts EBITDA Outlook As Acquired Growth Masks A Thinning Organic Core
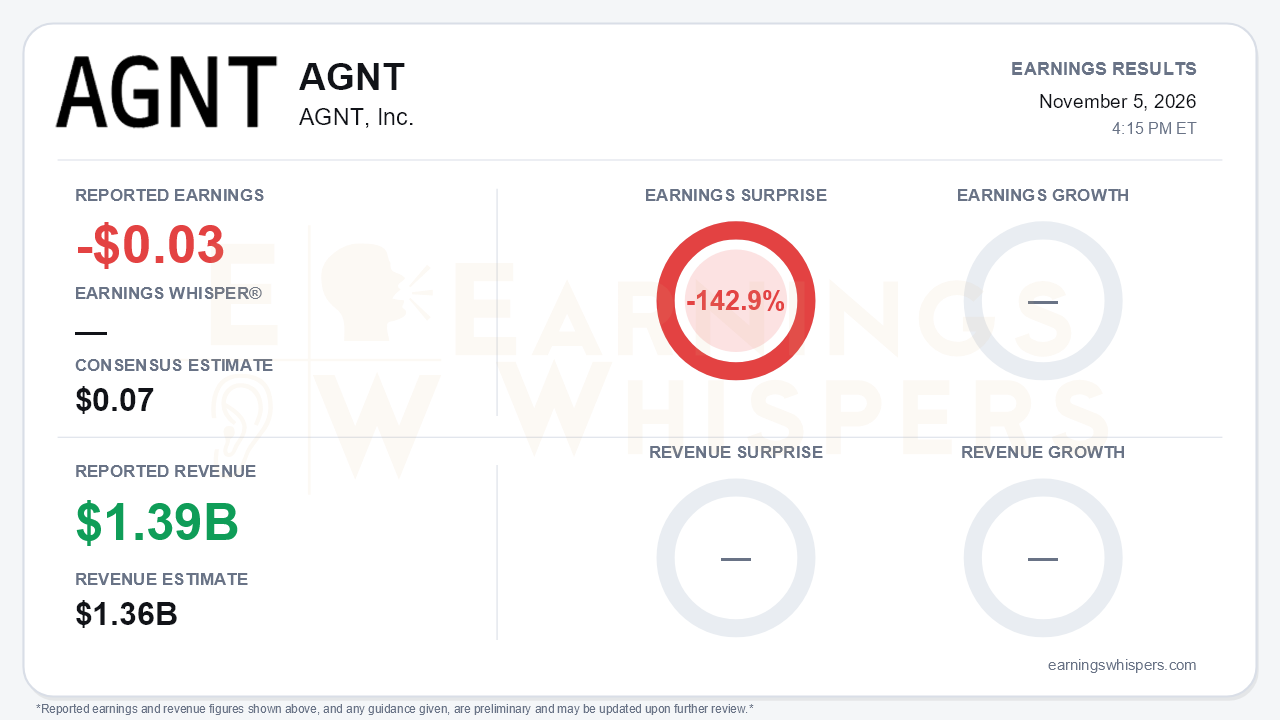
AGNT, Inc., the former eXp World Holdings, reported a third-quarter loss of $0.03 per share against a consensus estimate of a $0.07 profit, a 142.9% miss. Revenue of $1.393 billion beat the $1.36 billion consensus by 2.4%, and the top line rose 6% from a year ago. The beat did little for the investment case. AGNT swung from net income of $3.5 million, or $0.02 per share, to a net loss of $4.3 million. Management also lowered its full-year adjusted EBITDA outlook to $40-47 million from $50-60 million. The quarter landed inside prior guidance on both revenue and EBITDA, but nearly every growth rate slowed from the second quarter, and the outlook now assumes a loss-making fourth quarter.
The GAAP loss deserves a closer look before it is read as an operating collapse. Operating income was still positive at $3.1 million, down from $4.0 million. Most of the swing to a loss came from a $6.5 million charge in equity losses of unconsolidated affiliates. The nine-month cash flow statement attributes this largely to a loss on disposal of an unconsolidated affiliate. Excluding that item, however, the quarter would still have fallen well short of a $0.07 profit, so the miss is not purely a one-time accounting event. The operating picture was also soft. Gross margin was essentially flat at about 6.5% of revenue. Gross profit rose 6%, while operating expenses rose 7% to $87.9 million, which compressed operating leverage. Adjusted EBITDA slipped 3% to $17.1 million, a sharp reversal from Q2's $25.7 million, which had more than doubled year over year. Operating cash flow fell to $18.2 million from $28.9 million.
The call showed how much of the growth story now depends on acquisitions and international expansion. Transactions rose 8% and sales volume 10%, but transactions excluding the NextHome acquisition grew only 1.7%. Revenue growth slowed to 6% from 11% in Q2, transaction growth to 8% from 12%, and agent-count growth to 5% from 6%. North America Realty, the core business, saw adjusted EBITDA turn negative year over year, down 3% after rising 55% in the prior quarter. International remains the bright spot, with revenue up 27% and its adjusted EBITDA loss narrowed by 18%. Even there, growth decelerated from 44%. The company did report some stabilizers:
- Productivity per person rose 6%.
- Attrition remained concentrated among low producers.
- Team-based joiners rose to 44% of recruits.
One metric cuts the other way. The agent Net Promoter Score fell to 67 from 75, an awkward slide for a company whose identity rests on being agent-first.
The guidance is where the setup changed most. Earnings Whispers characterizes the update as a narrowing, and the revenue range technically did narrow, to $4.85-5.05 billion from $4.85-5.15 billion. But the narrowing came entirely from lowering the top end. Meanwhile, the EBITDA range dropped sharply and full-year operating expense guidance rose to $362-367 million. The fourth-quarter outlook calls for revenue of $1.0-1.2 billion and adjusted EBITDA between a $7 million loss and breakeven. Management's tone shifted accordingly, from Q2's "playing offense" posture to acknowledging a challenging market and planning around it. Management cited mortgage rates above 7.3% and legal costs it expects to peak in 2026. Management also described the cost base as roughly two-thirds fixed, which leaves limited room to protect margins if housing stays weak.
AGNT did announce several new initiatives:
- **Open Real Estate:** a listing-data consortium co-founded with Keller Williams, HomeServices and Real/RE/MAX. It is non-consolidated and not expected to be material.
- **AI tools:** an AI tool hub that has logged more than 1.2 million tool calls since its October 8 launch.
- **Agent OS:** a full-stack modernization of its agent operating system.
- **Revenos Mortgage:** a mortgage joint venture expected to launch in early 2027.
New CEO Leo Pareja has promised 2027 strategy and guidance on the Q4 call, which makes that report the next real test. None of these initiatives offsets near-term earnings pressure. The balance sheet, with $111.4 million in cash, no debt and a maintained $0.05 quarterly dividend, gives management time to execute.
The market context is harder to read cleanly. Shares closed at $4.27 the day before the report, up 11.8% from the open after the August release. That price sits about 11% below the inter-earnings high of $4.79 and about 26% above the September 24 low of $3.40, which was also a 52-week low. The supplied 200-day moving average of $2.75 is inconsistent with a 52-week low of $3.40, so the stock's reported 55% premium to that average should be treated with caution. Investor sentiment was roughly neutral before the prior report at -0.06. The current reading of 5.63 falls outside the -1 to +1 scale, so it cannot be reliably interpreted. The AVWAP trend reading remains negative and sequential growth is neutral, consistent with a stock that rallied into September weakness without establishing a durable trend.
The bottom line is that the revenue beat was the least informative number in the release. The EPS miss was inflated by a non-operating disposal loss, but the underlying story still weakened: organic transaction growth is barely positive, core North American profitability has rolled over, costs are rising faster than gross profit, and the EBITDA outlook was cut sharply. Shares had already rebounded off their September low heading into the report. Until the 2027 outlook shows the AI and platform investments translating into operating leverage, the burden of proof sits with management.
Read our earnings preview for AGNT, Inc.: https://www.earningswhispers.com/article/AGNT/22227
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-27 | |
| Oct-24 | |
| Aug-04 | |
| Aug-04 | |
| Jul-14 | |
| Jul-02 | |
| Jun-11 | |
| May-27 | |
| May-18 | |
| May-11 | |
| May-11 |
