Alpha And Omega's AI Server Ramp Faces Its First Real Test As Shares Slide
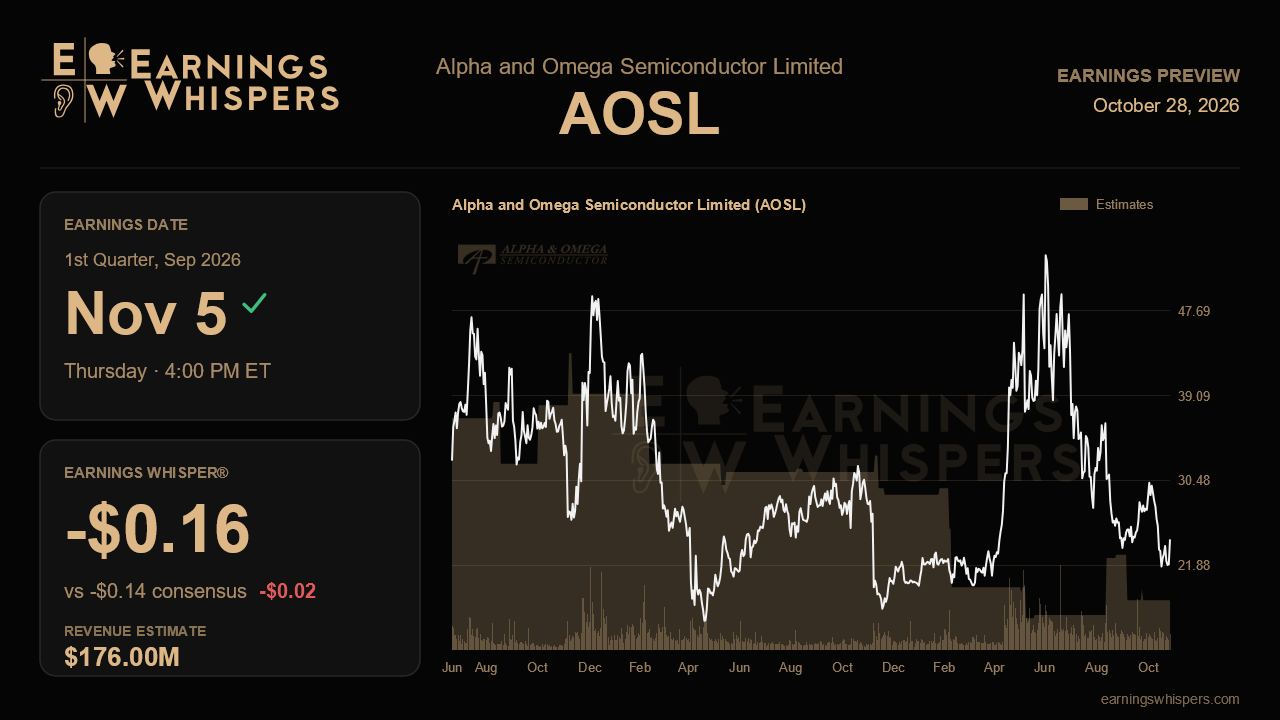
Alpha and Omega Semiconductor heads into its September-quarter report with a striking disconnect. Management used its last call to describe an AI and advanced-computing business that was inflecting faster than expected and pulling gross margin off the floor. Yet the stock has fallen 18.2% since then, trailing a roughly flat S&P 500 by more than 17 percentage points. The report due after the close on November 5 should show which side has it right: the improving operating story, or a market that doubts it can outrun weakness in PCs and consumer electronics.
The Street expects a non-GAAP loss of $0.14 per share on revenue of $176.0 million. That revenue figure sits exactly at the midpoint of management's $166 million to $186 million guidance range, and it is notably below the roughly $181 million consensus that prevailed when the outlook was issued. Analysts have walked their estimates back toward the company's own number rather than leaning on the upside. Revenue at that level would be up about 3% sequentially but down 3.6% from a year ago, so this is a recovery quarter, not a growth quarter. The Earnings Whisper of a $0.16 loss sits slightly below consensus. The gap is small, but it hints that the informal bar is a touch lower than the published one.
The heart of the quarter is the mix shift. Advanced computing grew from about a quarter of the computing segment to 31% last quarter. Management guided it up more than 40% sequentially, with AI and server revenue alone jumping more than 60% and becoming the majority of that business. Hitting those targets would validate the pivot. Falling short would undercut the main reason to look past continuing losses. The same goes for gross margin, which management guided to 24.5% from 23.7%, citing better mix and an improving pricing environment. Some simple arithmetic shows why the margin line matters. At guided revenue and margin, gross profit would land around $43 million against operating expenses guided to $46.5 million. That is why the Street still expects a loss even as the top line improves. Each additional point of margin narrows that gap meaningfully, and commentary on whether pricing gains carry into the December quarter could matter as much as the September print.
The offsets are real. Traditional PC was framed as being in an adjustment period because of memory and CPU shortages, which holds the overall computing segment roughly flat. Consumer was guided down about 25%. The flooding at the Shanghai back-end facility was estimated to cost a few million dollars of revenue plus some margin, and that hit is already embedded in guidance. A cleaner-than-feared recovery there would be a modest positive, while any lingering disruption would raise questions about execution. On the brighter side, communications was guided up about 10% on a Tier 1 US premium smartphone ramp, and the PowerIC rebound from last quarter needs to show it was not a one-off. Cash flow also deserves attention after operating cash flow came in at negative $10 million, as does any update on when elevated R&D spending tapers, which management expects largely by the end of calendar 2026.
Sentiment has soured. Readings have swung from mildly bullish before the last report to 21.1% bearish now. At $24.50, the stock trades well below its 200-day moving average near $30.41 and sits closer to the $21.40 low of its post-earnings range than the $34.13 high, a sharp step down from the prior quarter's $27 to $54 band. Expectations are not demanding, but the stock is clearly pricing in skepticism.
Ultimately, the quarter hinges on whether AI and server revenue delivered the outsized sequential jump management promised while gross margin kept climbing. If both hold and the December outlook points to further margin expansion, the improving narrative from last quarter stays intact, and the stock's slide looks overdone. If the AI ramp underwhelms or margin stalls, the PC and consumer drag becomes the story again, and continuing losses will be harder to excuse.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-28 | |
| Oct-13 | |
| Sep-28 | |
| Sep-08 | |
| Sep-08 | |
| Aug-13 | |
| Aug-12 | |
| Aug-12 | |
| Aug-12 | |
| Jul-14 | |
| Jul-10 | |
| Jul-07 | |
| May-18 | |
| May-06 |
