AOS Beats On AI And Server Mix Shift, But A Collapsing PC Business Keeps The Turnaround Unfinished
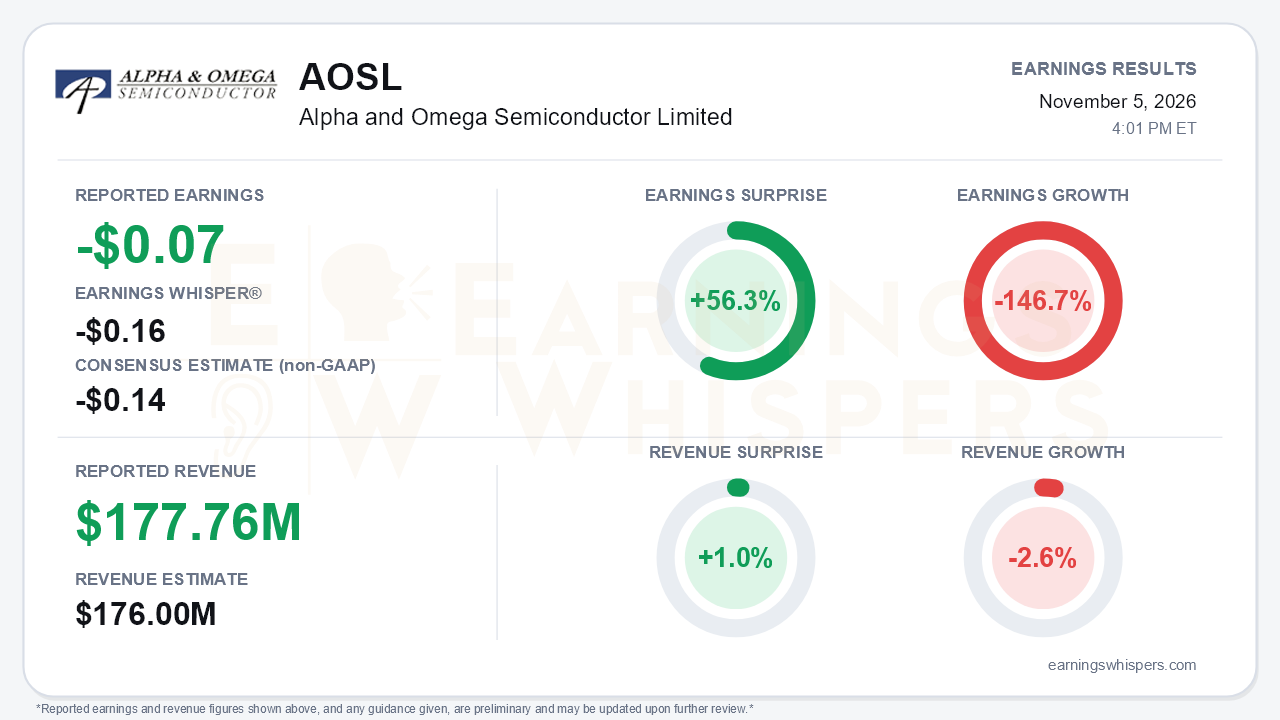
Alpha and Omega Semiconductor reported a non-GAAP loss of $0.07 per share for its fiscal first quarter, half the $0.14 loss analysts expected and better than the $0.16 Earnings Whisper. That is a 56.3% positive surprise. Revenue of $177.76 million edged past the $176.0 million consensus by 1.0%. The year-over-year comparison is still poor. Earnings fell 146.7% from a $0.13 profit a year ago, and revenue slipped 2.6%. The more important story is sequential. This was the third straight quarter of rising revenue and margins, and the business beneath it is being rebuilt around AI and server power. The central tension is whether that new engine can grow fast enough to outrun a traditional PC franchise that is deteriorating faster than management expected only three months ago.
The quality of the beat is mostly genuine. Revenue rose 4.3% sequentially, continuing a path of $163.8 million, then $170.4 million, then $177.8 million. Non-GAAP gross margin reached 25.2%. That beat the company's own 24.5% guide and compares with 23.7% last quarter and 21.7% two quarters ago. Management credited the improving mix, and pricing moved from neutral to slightly favorable. Operating cash flow turned positive at $5.6 million from a $10.0 million outflow, and EBITDAS improved to $12.2 million from $10.1 million.
The GAAP picture deserves some scrutiny. The GAAP net loss narrowed to $0.20 from $0.43, but that figure was flattered by $4.15 million of equity-method income tied to the restructuring of the Chongqing joint venture. In that restructuring, AOS's stake was diluted from 18.9% to 15.1%. Cost discipline is also not yet a tailwind. Non-GAAP operating expenses of $45.9 million were up roughly $4.5 million from a year ago, and EBITDAS remains well below the $19.4 million of the year-ago quarter.
The call made clear how quickly the revenue mix is shifting.
- **AI and server:** revenue grew more than 65% sequentially and more than 250% year over year. It now accounts for roughly 20% of total revenue, versus 5.5% a year ago.
- **Advanced computing:** grew more than 50% against a guide of more than 40%.
- **Communications:** rose 15%, ahead of a roughly 10% guide, on a Tier 1 U.S. smartphone battery-protection ramp.
- **Power supply and industrial:** jumped 29.2%, with record DC fan revenue tied to AI server cooling.
The offset is severe. Traditional PC revenue fell about 30% sequentially. Last quarter, management framed September as the main correction and did not expect a December leg down. It now expects continued weakness with no near-term recovery. Consumer revenue fell 31.4% year over year as the console cycle matures, and China smartphone demand remains pressured by memory costs.
Guidance reflects both forces. December-quarter revenue is guided to roughly $180 million, plus or minus $10 million. That is essentially in line with expectations but above the $176 million guide from the prior call, and it implies about 10% year-over-year growth in a seasonally soft period. The segment outlook is split:
- Communications is guided up mid-teens sequentially.
- Power supply and industrial is guided up high single digits.
- Total computing is guided down mid-to-high single digits.
Non-GAAP gross margin is guided to 25.7%, with operating expenses of about $46 million. At the midpoints, that points to roughly breakeven non-GAAP operating results rather than a clean return to profitability. The 30% mid-term gross-margin target remains distant. The 800V AI server opportunity had no meaningful update, and management's consideration of separately disclosing the AI and advanced computing business is a potential transparency catalyst rather than a fundamental one.
The market has been treating the stock as if the PC damage outweighs the AI progress. Shares closed at $21.17 ahead of the report, down 29.3% from the $29.94 open after the August release. That leaves them 30.4% below the 200-day moving average and 38% below the $34.13 inter-earnings high set the day after that report. The stock entered earnings just 2.3% above its quarterly low of $20.70, set the day before the release. Investor sentiment slipped from mildly positive at 0.06 to negative at -0.16, a meaningful deterioration that suggests expectations were reset lower. Earnings Whispers trend signals are mixed: momentum is positive, while price and AVWAP trends remain negative.
The bottom line is that AOS delivered a credible operating quarter. It beat on earnings, margins and segment targets, and its counter-seasonal guide shows the AI-driven mix shift is real. But the stock remains near its lows, sentiment has turned negative, and the company is still not profitable on a non-GAAP basis. Bears have legitimate ammunition in a PC business with no visible floor and an 800V story without a timeline. For now, the setup hinges on whether AI, communications and industrial growth can keep absorbing that erosion while margins move toward management's targets.
Read our earnings preview for Alpha and Omega Semiconductor Limited: https://www.earningswhispers.com/article/AOSL/22235
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-29 | |
| Oct-28 | |
| Oct-13 | |
| Sep-28 | |
| Sep-08 | |
| Sep-08 | |
| Aug-13 | |
| Aug-12 | |
| Aug-12 | |
| Aug-12 | |
| Jul-14 | |
| Jul-10 |
