AvePoint's AgentPulse Momentum Faces A Margin And FX Test After 32% Rally
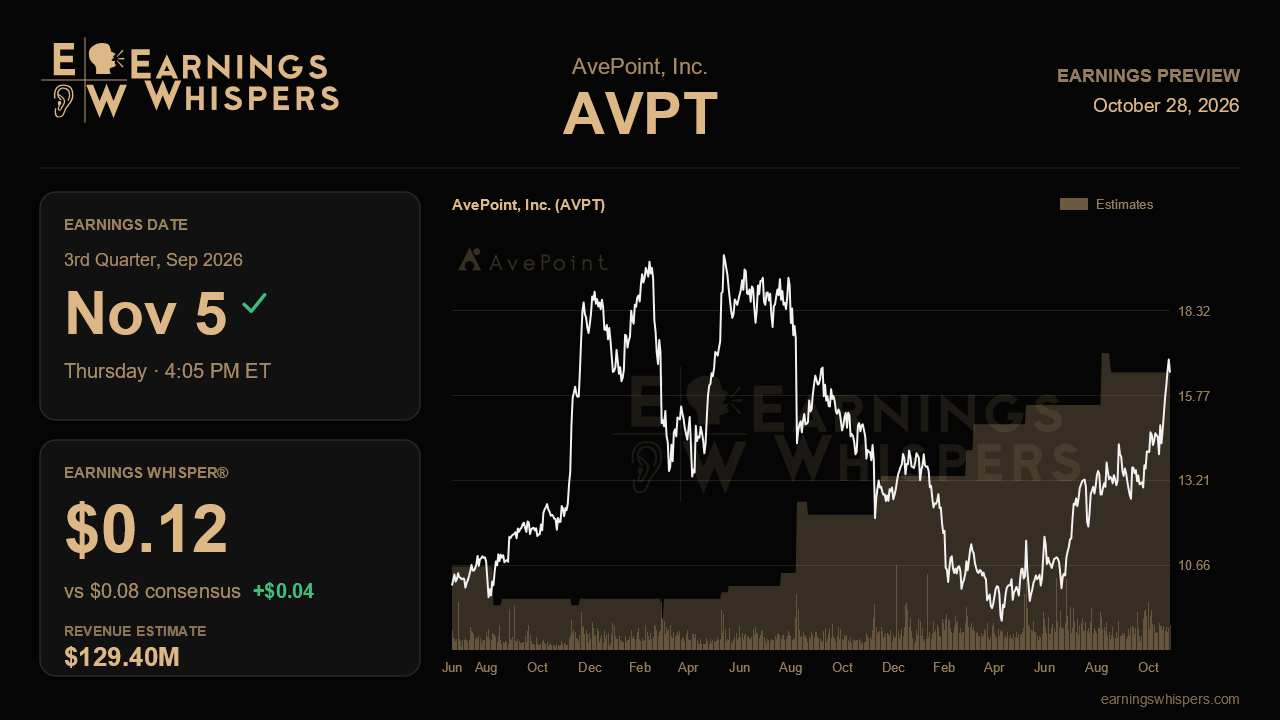
AvePoint enters its third-quarter report with an unusual split personality. Demand looks better than it has in years, with record net new annual recurring revenue last quarter and a fresh AI-governance product drawing larger deals. Yet management also trimmed its full-year revenue outlook and cut its operating income forecast. The stock has climbed about 32% since that report, so the market has clearly chosen to believe the demand story. The report due after the close on November 5 has to show that the choice was the right one.
The Street expects earnings of $0.08 per share on revenue of $129.4 million, which would be about 18% revenue growth from a year ago. That sits just above the midpoint of management's third-quarter range of $128.2 million to $130.2 million, so consensus is not stretching. The full-year picture is a bit tighter. Analysts' roughly $513 million estimate sits slightly above the top of the company's $508.5 million to $512.5 million range, which suggests some expectation that the currency headwinds behind last quarter's cut will ease or that the business will outrun them. The whisper number of $0.12 is well above consensus and matches last quarter's result. That points to a higher bar on profitability than the published estimate implies, even though management deliberately raised second-half spending.
The growth rate deserves context. Reported revenue rose 22% last quarter, and an 18% pace would look like a slowdown. Management flagged two reasons for caution in reported revenue: currency and an uncertain mix between SaaS and term-license sales in the back half. Recurring revenue metrics are therefore the better gauge. Net new ARR reached a record $29.9 million in the second quarter, up 35% from a year earlier, and total ARR growth sped up to 27%. The case would be strengthened by another solid net new ARR figure, even one below the record, along with continued growth in the 911 customers paying over $100,000 annually. A sharp drop in net new ARR would suggest the second quarter was lumpy rather than a turning point.
AgentPulse is the newest and most important variable. The product became available on a standalone basis in early July, so this is the first full quarter in which it can be judged on its own. Management said control-bundle packages roughly doubled quarter over quarter and that deals including AgentPulse were running two to three times larger. It also acknowledged that most of the opportunity was still in the pipeline. That makes net revenue retention the key figure to check. It held at 110% for two straight quarters, short of the 115% target. If governing AI agents is truly an expansion engine, retention should start to rise. A third flat reading would raise the question of whether the product is winning new logos without deepening existing accounts. Gross retention of 89%, with migration as a recurring drag, is also worth watching.
On margins, management has already told investors to expect pressure. Operating margin slipped to 16.3% last quarter as spending reached 57% of revenue. Holding margins near that level while ARR keeps growing would justify the investment. Further erosion without matching bookings would make the spending look less disciplined.
Sentiment has turned from modestly bearish before the last report to modestly bullish now. The stock trades far above its 200-day moving average of $11.83 and sits a few percent below its post-earnings high of $17.06, a much higher range than the prior quarter's $9.52 to $13.79. That rally leaves little room for a muddled report. In the end, the result depends on whether AgentPulse begins to show up in expansion metrics. If it does, the margin and currency trims will look like the cost of a growth cycle. If it does not, the rally will have run ahead of the evidence.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-19 | |
| Oct-13 | |
| Aug-07 | |
| Aug-06 | |
| Aug-04 | |
| Jul-30 | |
| Jul-21 | |
| Jul-13 | |
| Jun-29 | |
| May-18 | |
| May-07 |
