AvePoint Misses The Whisper As AI-Trust Spending Squeezes Margins, But A Third Straight ARR Acceleration Keeps The Growth Story Intact
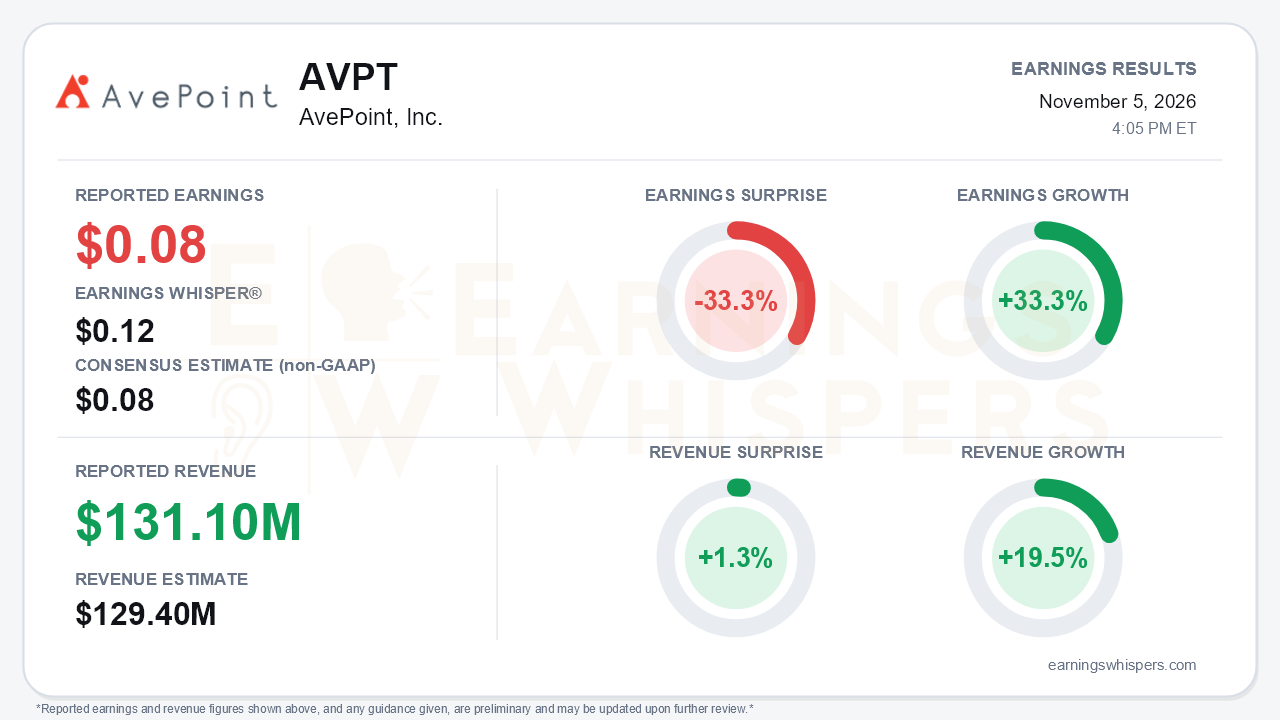
AvePoint's third quarter showed a company deliberately trading near-term profitability for growth, and the earnings line reflected that choice. The company reported earnings of $0.08 per share, in line with the $0.08 consensus but short of the $0.12 Earnings Whisper number, a 33.3% miss against the more demanding expectation. Earnings still grew 33.3% year over year. Revenue of $131.1 million rose 19.5% and beat the $129.4 million consensus by 1.3%. That is the central tension: every top-line and recurring-revenue indicator improved, while the margin structure that supports earnings moved in the wrong direction.
The quality of the quarter deserves scrutiny on both sides. On the positive side, SaaS revenue climbed 26% to $105.5 million, and GAAP operating margin expanded to 8.7% from 7.4%. Underneath that, however, non-GAAP operating income fell to $22.0 million from $24.1 million, and non-GAAP operating margin dropped to 16.8% from 22.0%. Non-GAAP sales and marketing jumped to 33.7% of revenue from 29.9%, which shows where the money went. Non-GAAP gross margin slipped to 72.8% from 75.1% a year ago and 73.7% last quarter, mainly because of weaker services margins. Term license and support revenue fell to $8.9 million from $12.0 million as the SaaS transition continues. GAAP net income of $17.9 million also benefited from a $2.6 million tax benefit, including a $1.1 million valuation-allowance release, so the bottom line was not purely operational.
The call made a credible case that the spending is working. FX-adjusted ARR growth accelerated for a second straight quarter, from 23% in Q1 to 24% in Q2 to 25% in Q3. Total ARR reached $495.1 million. Net new ARR hit a record $30.0 million, up 34% year over year. Gross retention reached the company's long-standing 90% target, up from 88% at the end of last year. FX-adjusted net retention improved to 111%. Customers paying more than $100,000 rose 28% to 976, with growth accelerating for a third quarter and a record 65 net additions. Management's tone was noticeably more emphatic. The CEO called AI trust "the largest market opportunity in our company's history."
The new catalysts are substantive:
- the AvePoint Trust Platform, which extends governance to AI models, MCP servers and Anthropic Claude;
- inclusion in Gartner's first Magic Quadrant for AI agent management platforms;
- AgentPulse customers up 50% sequentially, with managed agents more than doubling;
- a new $100 million revolver;
- addition to the S&P SmallCap 600.
Bears still have legitimate ammunition. Standalone AgentPulse revenue is mostly a 2027 story. Seat-based pricing is not tied to agent counts. The Microsoft ecosystem still accounts for roughly 90% of ARR. Competition is emerging from identity and cybersecurity vendors, and U.S. public sector demand has not fully recovered.
Guidance moved up, but modestly. The full-year ARR range rose by $1 million at the midpoint to $524.8 million to $528.8 million, the third consecutive raise. Revenue guidance increased to $511.3 million to $513.3 million, and Q4 revenue guidance implies 22% growth, faster than Q3's pace. Full-year non-GAAP operating income guidance edged up to $87.5 million to $88.5 million. That figure remains well below the $92.6 million to $96.6 million range the company issued in February, before the second-half investment step-up. The implied Q4 operating margin of about 18% also trails last year's roughly 20%. Investors are being asked to accept lower margins in exchange for faster ARR growth.
The market had already embraced that trade before the report. Shares rose 35.2% from the $12.50 open after the August report to $16.90. That leaves the stock about 41.5% above its 200-day moving average and only 3.5% below the 52-week high of $17.52 set on October 30. Investor sentiment moved from modestly negative (-0.18) to solidly positive (+0.48), a meaningful swing. The Earnings Whispers trend signals were uniformly positive heading into the release. The stock came in near the top of its range with elevated expectations, which helps explain why the bar was set at a $0.12 whisper rather than the $0.08 consensus. The buyback has also become a smaller cushion. The company spent $141 million repurchasing shares year to date, leaving roughly $89 million of authorization.
The bottom line is that AvePoint delivered the growth story but not the earnings upside a richly re-rated stock was priced for. Accelerating ARR, record net new bookings, improving retention and three straight ARR guidance raises suggest the AI-trust push is gaining traction. Shrinking non-GAAP margins and a profit outlook still below February's targets show the cost of that push. Whether the investment proves well-timed depends on AgentPulse and the Trust Platform turning pipeline into revenue in 2027.
Read our earnings preview for AvePoint, Inc.: https://www.earningswhispers.com/article/AVPT/22243
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 11 hours | |
| Nov-05 | |
| Nov-05 | |
| Nov-04 | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-19 | |
| Oct-13 | |
| Aug-07 | |
| Aug-06 | |
| Aug-04 | |
| Jul-30 | |
| Jul-21 |
