BCP Investment Must Prove $0.27 Dividend Is Covered As Income And NAV Keep Sliding
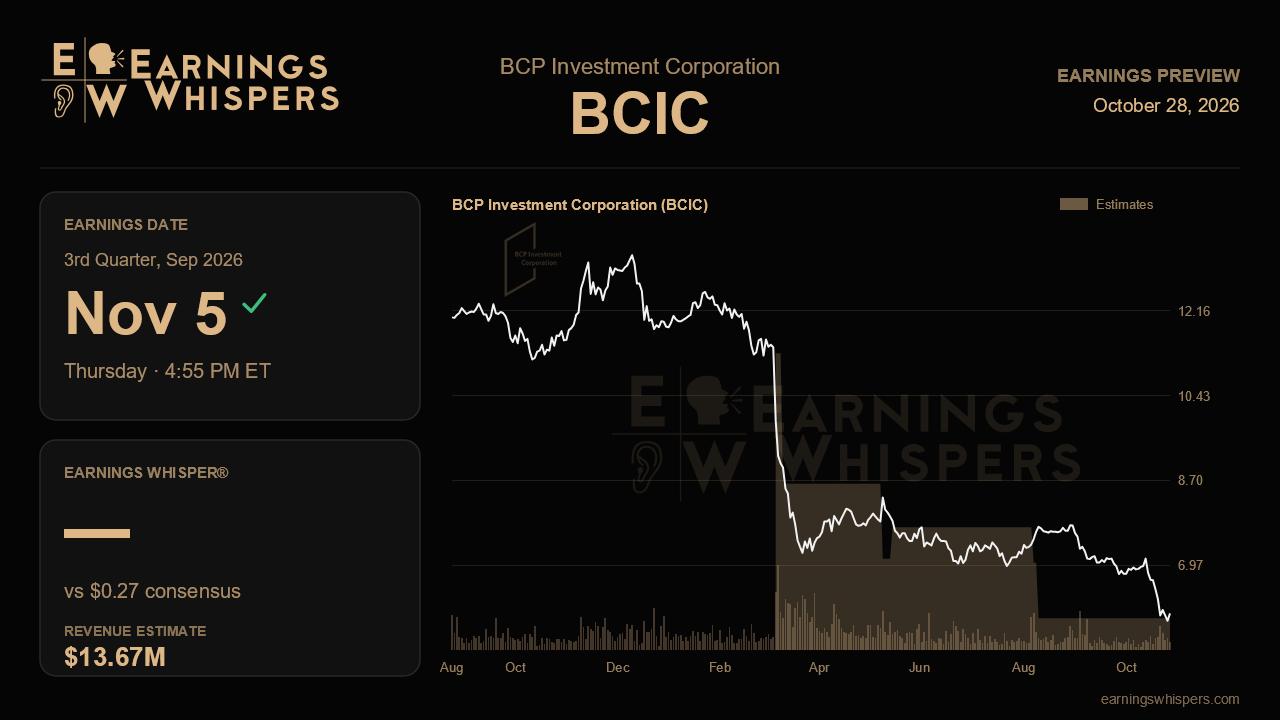
BCP Investment Corporation heads into its third-quarter report with a number that does a lot of work. Wall Street expects earnings of $0.27 a share, which matches the core net investment income the company produced last quarter and the $0.27 quarterly distribution it now pays in monthly installments of $0.09. Coverage of the dividend, with almost no cushion, is the whole story. The balance sheet has been getting safer for several quarters, but the earnings engine has been shrinking, and this report should show whether the shrinkage has stopped.
The Street is bracing for a steep contraction. Consensus revenue of $13.7 million would be down about 28% from $18.9 million a year ago and below the $15.2 million reported last quarter. The expected 61% drop in per-share earnings looks dramatic against last year's $0.70, but much of that gap reflects the reset that has already happened. Reported net investment income fell to $0.45 last quarter from $0.71 a year earlier, and core income was only $0.27, so the consensus effectively assumes core earnings simply hold. Management has not issued formal guidance, which leaves the dividend level as the clearest signal of what the company thinks it can sustainably earn.
The forces behind the slide have not obviously reversed. Total investment income has dropped for four straight quarters because repayments keep outpacing new loans, with net repayments of about $14 million last quarter and originations of just $20.9 million. Management described deal volume as meaningfully lower and said buying back its discounted stock is a better use of capital than new lending. That choice may make sense for per-share value, but it shrinks the portfolio and leaves less income to cover the distribution. A smaller decline in investment income, or a quarter of net growth in the portfolio, would show the base is stabilizing. Another drop well below consensus revenue would suggest the $0.27 payout is still too high.
The positives from last quarter also need follow-through. Net non-accruals fell to 5.7% of cost from 7.1% two quarters earlier, asset coverage rose to 162%, and gross leverage eased to 1.6 times. After quarter end, the company doubled its KeyBank facility to $150 million, cut the spread by 30 basis points, extended the maturity and retired its JPMorgan revolver. Lower borrowing costs should show up first in interest expense, which is one of the few ways to support earnings while assets shrink. New loans were also priced at 13.3%, up from 10.7%, which helps, but only if the company makes enough of them to matter.
The biggest risk is valuation. Net asset value per share has dropped from $17.55 to $14.49 in three quarters, and the average price of loans still accruing interest slipped to 88.6% from 93.1%. Nearly half of last quarter's markdowns came from software companies hit by worries about artificial intelligence, and a $10.5 million realized loss showed that resolving problem loans can be costly. Another sizable markdown would undercut the de-risking story even if credit metrics improve.
The market has turned harsher. The stock has fallen about 17% since the last report while the S&P 500 was flat, and at $5.98 it trades far below its 200-day average of $8.30 and only slightly above its post-earnings low of $5.78. That is well under half of last reported NAV per share. Sentiment has grown more bearish heading into the release. The low bar means a steady quarter could bring some relief. Still, the stock will turn on two questions: whether core earnings cover the $0.27 distribution, and whether NAV finally stops falling. If either answer is no, the market is likely to keep doubting the company's cleanup.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-08 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Jul-09 | |
| Jul-07 | |
| May-21 | |
| May-07 | |
| May-07 | |
| Apr-08 | |
| Mar-06 | |
| Mar-06 | |
| Mar-05 | |
| Mar-05 |
