BCP Investment Beats On NII, But Core Earnings Fall Below The Dividend As NAV Erosion Continues And The ICMB Merger Takes Center Stage
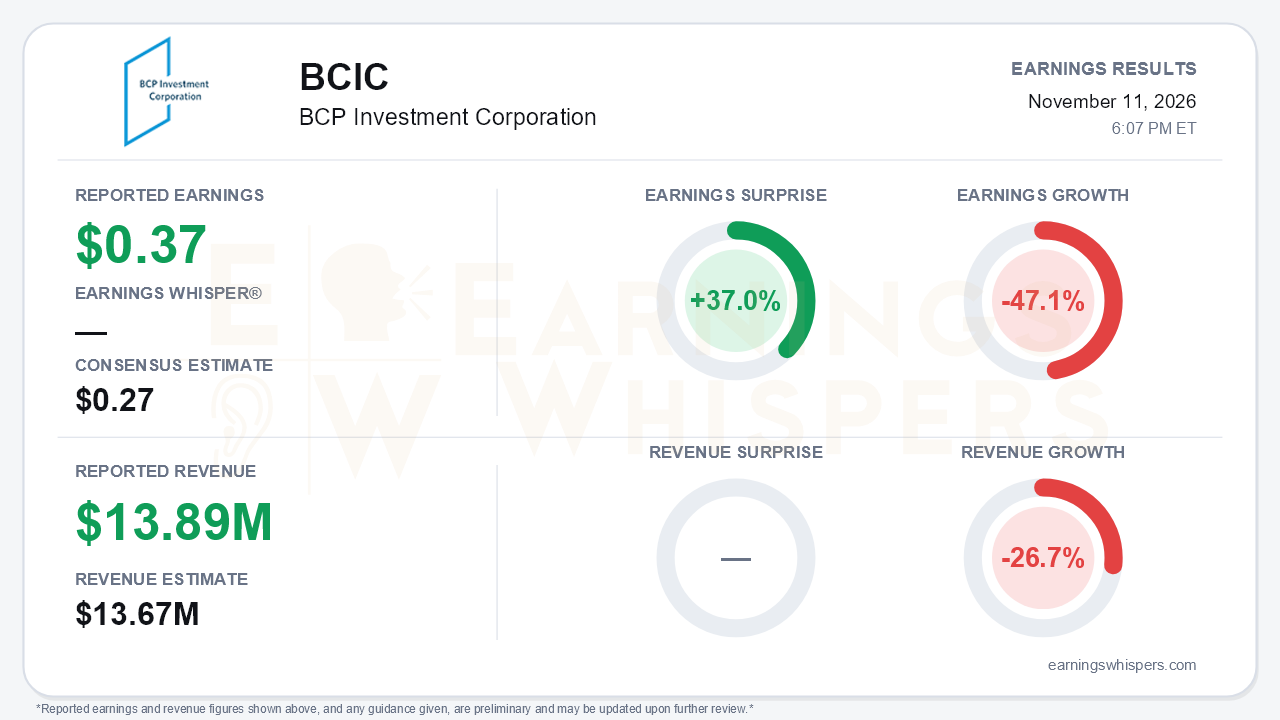
BCP Investment Corporation (NASDAQ: BCIC) reported third-quarter net investment income of $0.37 per share, beating the $0.27 consensus by 37.0%. Total investment income of $13.89 million topped the $13.67 million estimate by 1.6%. The beat, however, sits on a shrinking base. NII fell 47.1% year over year and revenue declined 26.7%, and the sequential slide continued, with NII per share moving from $0.57 in Q4 FY25 to $0.55, $0.45 and now $0.37. Management chose to lead the release with a subsequent-event merger agreement to acquire Investcorp Credit Management BDC (ICMB). That is the central tension: a deal pitched as accretive arrives while BCIC's own earnings power and net asset value keep deteriorating.
The quality of the beat deserves scrutiny. Purchase discount accretion from prior mergers contributed $1.66 million of income. Excluding it, core investment income was $12.2 million, down from $12.9 million in Q2 and $15.3 million a year ago. On the call, core NII was put at $0.24 per share, down from $0.27 in Q2 and $0.33 in Q1. That is now below the $0.27 quarterly base distribution, which the board just reaffirmed at $0.09 per month for the first quarter of 2027. The consensus figure roughly matched the dividend run-rate, so the headline beat owes much to accretion rather than recurring earnings.
The GAAP picture was harsher. BCIC recorded a net decrease in net assets from operations of $1.09 per share, driven by $8.9 million of realized losses and $8.5 million of unrealized depreciation. NAV per share fell to $13.13 from $14.49 in Q2, $15.60 in Q1 and $16.68 at year-end. That is the fourth consecutive sizeable decline.
The operating trends beneath the headline point the wrong way. Originations dropped to just $3.1 million with no new borrowers, down from $20.9 million in Q2, while repayments and sales totaled $8.9 million. New-money yield slipped to 11.4% from 13.3%. Management, which earlier in the year anticipated a pickup in 2026 M&A activity, now cites rising benchmark rates slowing deal flow in the lower middle market. It explicitly guided to a slower deployment pace.
Credit is mixed. Non-accruals fell to 10 investments and 2.8% of the portfolio at fair value from 3.1%, but they rose to 6.0% at cost from 5.7%. That pattern suggests improvement in the fair-value metric partly reflects deeper markdowns. The call flagged continued stress in 2021-22 vintages and select software credits. Asset coverage slipped to 157% from 162%, and leverage edged up to 1.7x as NAV shrank faster than debt.
The liability side is where management delivered genuine progress:
- The KeyBank facility doubled to $150 million, with the spread cut 30 basis points and maturity extended to 2031.
- The JPMorgan facility was retired.
- The remaining 2026 notes were redeemed in October, eliminating near-term maturities.
Management now plans to favor debt repayment and share repurchases over new investments, with a $10 million buyback through March 2027 and a deleveraging target of 1.25-1.4x. With the stock trading at roughly half of NAV, buybacks are arguably the most accretive use of repayment proceeds. Still, a shrinking income-producing portfolio makes covering the dividend harder.
The ICMB deal is the key catalyst. BCIC would pay 90% of ICMB's adjusted NAV, and management said on the call that BCIC shares would be issued at 100% of NAV. Stock consideration is capped at 19.99% of BCIC's shares, and cash at up to 60% of total consideration. Roughly 41% of ICMB holders have signed voting agreements. Management expects lower financing costs, reduced per-share public company costs and better trading liquidity, and guided to accretion to NAV per share at close and to NII over time. Bears have legitimate ammunition, though. ICMB brings a declining NAV, a suspended distribution and legacy restructuring positions. A cash-heavy structure would also draw on a balance sheet with $2.3 million of unrestricted cash and $49.6 million of revolver capacity.
The market has not been rewarding the story. Shares at $6.57 are down 9.1% since the open following the August report and sit 17.5% below the 200-day moving average of $7.97, and the AVWAP trend remains negative. The investor sentiment reading cannot be interpreted reliably. The current value of 4.81 falls outside the -1 to +1 scale, against a prior reading of -0.18 that was modestly negative. It should not be read as evidence of a sentiment swing until the data are clarified.
The bottom line is that BCIC's headline beat obscures a business with declining core earnings, a dividend no longer covered on a core basis, minimal new origination and steadily falling NAV. The balance sheet repair is real, and the ICMB merger offers a plausible path to scale and cost relief. However, the deal's benefits are prospective and carry integration risk. Until core NII stabilizes and NAV stops eroding, the stock's discount reflects concerns the quarter did little to resolve.
Read our earnings preview for BCP Investment Corporation: https://www.earningswhispers.com/article/BCIC/22247
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-11 | |
| Nov-11 | |
| Nov-11 | |
| Nov-11 | |
| Nov-05 | |
| Oct-28 | |
| Oct-08 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Jul-09 | |
| Jul-07 | |
| May-21 | |
| May-07 |
