CarGurus Must Prove Dealer Caution Is Temporary As Revenue Growth Slows Toward 7%
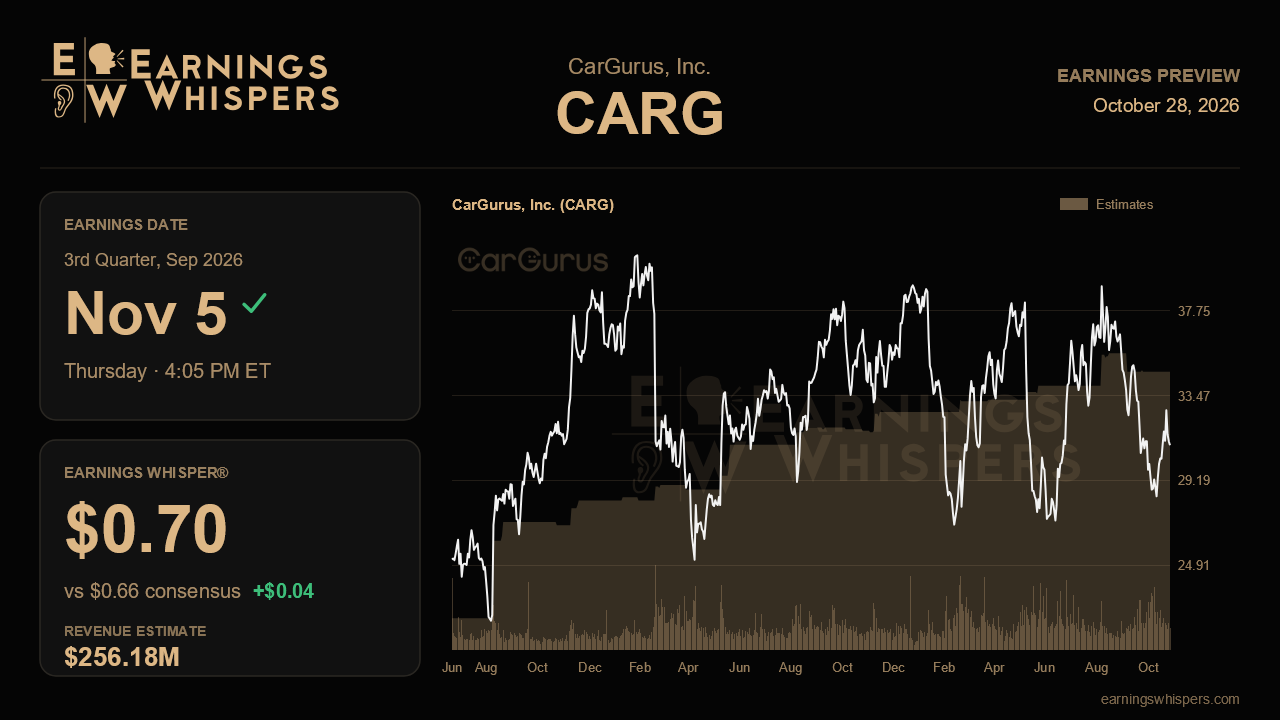
CarGurus heads into its third-quarter report with a credibility test. Three months ago, management told investors that dealers had grown more deliberate about spending, but described the pullback as a passing phase rather than a structural shift. The market did not wait to find out. Shares have fallen about 23% since that report while the S&P 500 was essentially flat. When results arrive after the close on November 5, the question is whether the slowdown is leveling off or still gathering speed.
The numbers on the table are modest by CarGurus standards. Analysts expect non-GAAP earnings of $0.66 per share on revenue of $256.2 million, which would be growth of roughly 7% over the $238.7 million reported a year earlier. That is a clear step down from the 13% pace in the second quarter and the 15% growth posted in the two quarters before that. Consensus sits at the midpoint of management's $0.63 to $0.69 earnings guidance and slightly above the middle of its $253.5 million to $258.5 million revenue range. The Earnings Whisper of $0.70 is a little more demanding. It sits just above the top of the company's earnings range, suggesting some investors expect the cost discipline on display last quarter to show up again on the bottom line.
That profitability story is the main thing working in CarGurus' favor. Management narrowed its expected full-year adjusted EBITDA margin compression to about 50 to 150 basis points, compared with the 150 to 250 basis points it had guided for two straight quarters. It credited AI-driven efficiencies such as automated customer support and lower software costs. Yet second-quarter adjusted EBITDA rose only 7% and margin slipped about 200 basis points to around 34%. This report should show whether those savings are actually reaching the income statement, or whether the raised outlook depends too heavily on the fourth quarter.
The top line is where the narrative is most exposed. U.S. paying dealer additions have shrunk each quarter, from 1,357 year over year in the fourth quarter of 2025 to 963 and then 673. Management linked the caution to squeezed dealer gross profit per unit, shorter days on lot, and the cost of complying with FTC all-in pricing rules. It also explicitly cited softer dealer decision-making as the reason for the lighter third-quarter guide. If dealer additions stabilize and revenue lands near the top of the range, the temporary framing gains credibility. Another sharp drop in dealer adds, or revenue near the low end, would suggest the headwinds are lasting longer than management thought. It would also put the reaffirmed full-year revenue outlook of 10% to 13% growth under pressure.
The product pipeline is the counterweight. PriceVantage bookings rose 50% sequentially last quarter. Leads driven by the new Guru consumer AI brand climbed 60% in the U.S., and early VinMax users saw promoted listings sell 23% faster. Sessions per dealer were up 28%, and international revenue grew 28%. What matters now is whether that engagement turns into spending. Dealers who are getting more value but paying the same rates do little for revenue, so evidence of upselling into the new suite would carry real weight.
Sentiment has moved from 22.3% bearish before the last report to 4.2% bullish, though that is hardly enthusiasm. The stock, at $30.96, trades below its 200-day moving average of $32.96 and closer to the $27.79 low of its post-earnings range than the $41.22 high. That setup lowers the bar. Even so, a clean beat may not be enough if the outlook implies dealer caution is persisting. The verdict on this report will rest less on earnings per share than on one question: is dealer spending stabilizing, and are the AI products turning into revenue fast enough to restore double-digit growth?
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Oct-19 | |
| Sep-29 | |
| Sep-03 | |
| Sep-01 | |
| Aug-26 | |
| Aug-11 | |
| Aug-06 | |
| Aug-06 | |
| Jul-20 | |
| Jul-20 | |
| Jun-23 | |
| May-26 | |
| May-11 | |
| May-07 |
