CarGurus Hits The Whisper And Lifts Profit Outlook, But Q4 Guide Shows Revenue Growth Slowing To 7%-9%
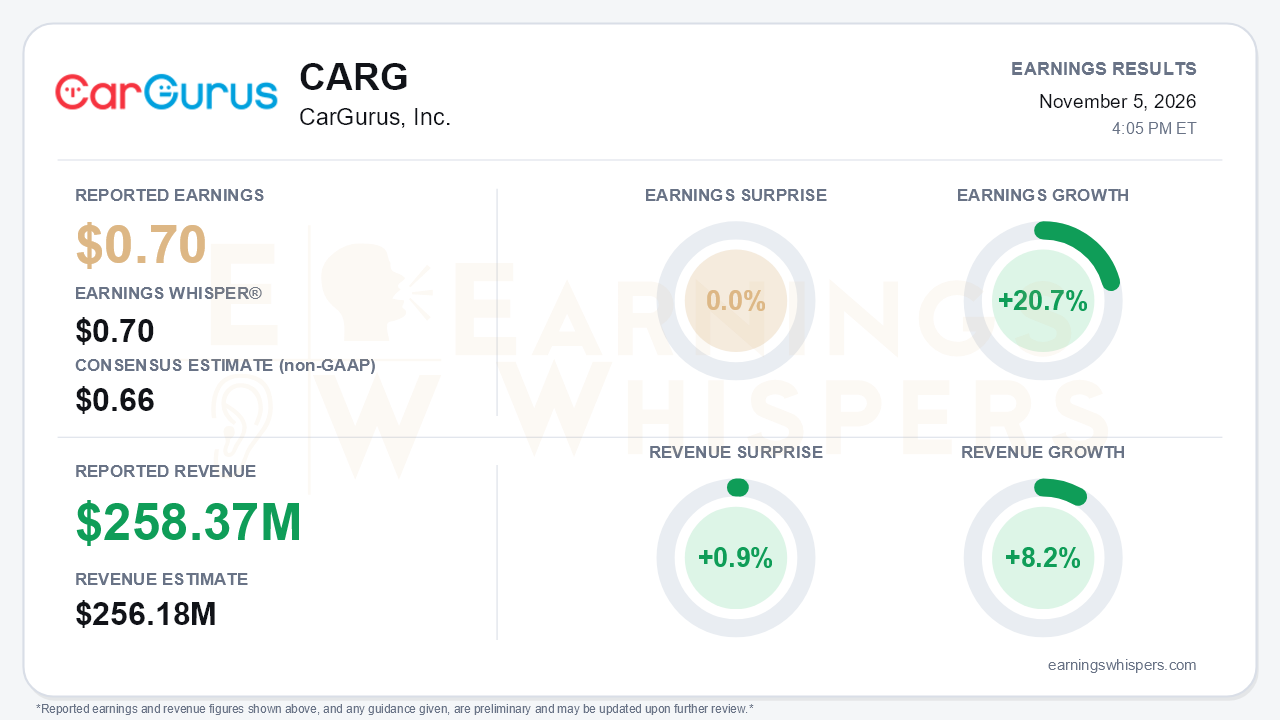
CarGurus delivered almost exactly what the most informed expectations demanded. Third-quarter non-GAAP earnings of $0.70 per share matched the Earnings Whisper number and topped the $0.66 consensus. Revenue of $258.37 million beat consensus by 0.9%. Earnings Whispers calculates earnings growth of 20.7% and revenue growth of 8.2% year over year. The company's own continuing-operations presentation, which excludes the wound-down CarOffer business, shows revenue up 12% and non-GAAP EPS up 17%. Investors should note the difference in bases. Neither framing changes the central tension. CarGurus is squeezing more profit out of its investment year than it planned, while its top line is losing speed heading into the fourth quarter.
The quality of the earnings beat deserves scrutiny. GAAP net income from continuing operations rose just 2% to $52.8 million, and the GAAP net margin slipped about 200 basis points to 20%. Several factors held back GAAP profit:
- Gross margin eased roughly 90 basis points to 92% as depreciation in cost of revenue nearly doubled.
- Interest income fell by about half.
- Operating expenses grew 12%, in line with revenue.
Per-share growth came largely from the shrinking share count. Diluted shares fell to 90.1 million from 99.7 million a year earlier, after heavy buybacks. Adjusted EBITDA rose 9% to $89.7 million, near the high end of guidance, though it included a $1.3 million one-time real estate tax true-up. Operating cash flow of $80.8 million and free cash flow of $73.9 million were both up year over year. However, free cash flow conversion fell to 82% from 103% in the second quarter.
The call made the deceleration hard to ignore. Revenue growth has stepped down from 15% in Q1 to 13% in Q2 and 12% in Q3. U.S. CarSID growth eased from 9% to 8% to 7%. International revenue growth slowed from 39% to 28% to 22%, with dealer churn tied to CarGurus holding price amid tariffs and Chinese EV disruption in the U.K. Fourth-quarter revenue guidance of $258.5 million to $263.5 million implies only 7.2% to 9.3% growth. Management blamed lighter first-half bookings, persistent dealer margin pressure, and softer consumer demand from higher gas prices, interest rates, and stretched affordability. The tone also shifted. Last quarter management called the headwinds temporary rather than structural. This quarter it acknowledged that dealer enthusiasm has not returned to 2025 levels.
The call still preserved a credible profitability story. Management raised its margin outlook for the second straight quarter. Full-year Adjusted EBITDA margin compression is now expected at just 20 to 80 basis points, versus 150 to 250 basis points at the start of the year. Full-year revenue guidance was narrowed to $1,011.5 million to $1,016.5 million, the upper half of the prior range. New full-year Adjusted EBITDA guidance of $347.5 million to $355.5 million and non-GAAP EPS guidance of $2.66 to $2.72 came in above estimates. Product engagement offers the bull case its best evidence:
- Net U.S. dealer adds reaccelerated to 251 sequentially, the best quarter of the year.
- Multi-product U.S. dealers grew about 16%.
- VinMax ranks among the fastest-adopted add-ons ever.
- Guru usage rose 24% sequentially.
- StockVantage launched in the inventory pillar.
CarGurus also added a Claude connector alongside its ChatGPT app. Bears have legitimate ammunition here too. U.S. uniques and sessions slowed versus Q2, and analysts pressed on AI search disintermediation and lead attribution.
Capital return remains a meaningful support. The board authorized a new $250 million buyback running through 2027. Cash rose to $165 million from $122 million in Q2, partly because third-quarter repurchases slowed to $22.9 million from $110.3 million a year ago. A new CFO, Matt Mandel, joined in October.
The market setup is more complicated than the in-line result implies. Shares entered the report at $36.52, 8.7% below the open after the August report and 11.4% below the $41.22 52-week high set that day. Over the quarter the stock slid to $27.79 in early October before rebounding 31.4% to sit about 11% above its 200-day moving average. Investor sentiment improved notably over the period, from -0.22 to -0.03. That leaves sentiment roughly neutral rather than enthusiastic. The Earnings Whispers trend readings are mixed, with sequential growth positive while price and AVWAP trends remain negative.
The bottom line is that CarGurus executed well on what it controls. It delivered margins, cash generation, buybacks, and product adoption, and matched the whisper while guiding profits above estimates. But the Q4 guide confirms revenue growth decelerating toward the high single digits amid dealer caution and soft consumer demand. Unless dealer adds and multi-product momentum translate into reaccelerating revenue, margin upside and share shrinkage will have to carry the earnings story.
Read our earnings preview for CarGurus, Inc.: https://www.earningswhispers.com/article/CARG/22254
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-19 | |
| Sep-29 | |
| Sep-03 | |
| Sep-01 | |
| Aug-26 | |
| Aug-11 | |
| Aug-06 | |
| Aug-06 | |
| Jul-20 | |
| Jul-20 | |
| Jun-23 |
