Conduent's Leaner Revenue Base Faces First Real Test As Bookings And Margins Diverge
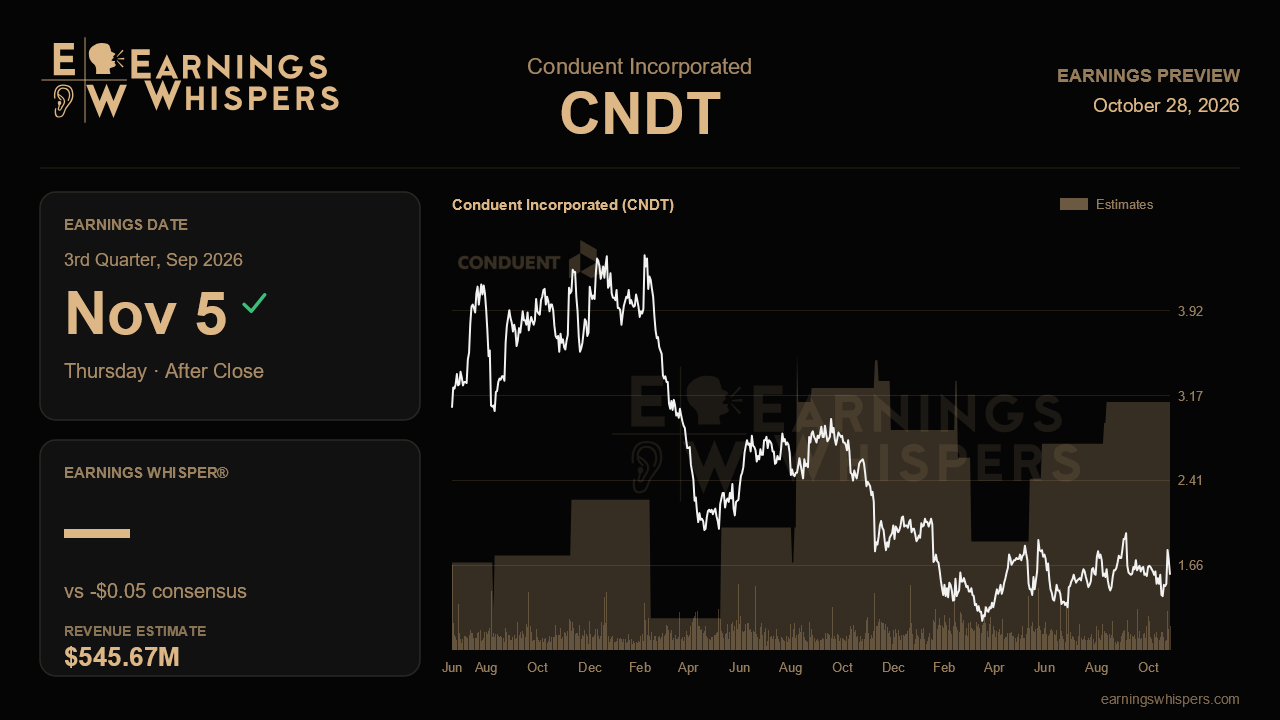
Conduent heads into its third-quarter report as a noticeably smaller company, and the question is whether that is a feature or a flaw. Management has spent the year selling off its entire transportation business, cutting costs and pushing margins higher. Yet the revenue line keeps shrinking and new bookings slipped last quarter. The November 5 release, due after the close, is the first clean look at the slimmed-down company's revenue run rate after its transportation exit, and that makes it more revealing than the headline numbers suggest.
Wall Street expects a loss of 5 cents a share on revenue of about $545.7 million. On the surface, that revenue figure is a 28.9% year-over-year collapse from $767 million. Much of that drop reflects accounting rather than lost business, because transportation, which generated roughly $609 million in 2025, now sits in discontinued operations. The more useful comparison is sequential. Consensus implies a modest step up from the $531 million reported last quarter, and an annualized pace near the middle of management's re-based 2026 outlook of $2.15 billion to $2.25 billion. That range replaced earlier guidance of $2.80 billion to $2.90 billion, which included transportation. Some full-year consensus figures still reflect the old basis, so the Street's quarterly number is the better gauge, and it looks reasonably aligned with the new guide rather than stretched. The expected loss would also be a clear improvement from the 9-cent loss a year ago and the 18-cent loss last quarter.
That earnings improvement leans heavily on the cost story. Management has promised $100 million in annualized savings, with most of it landing this year, and adjusted EBITDA margin has climbed from 5.2% to 6.8% over recent quarters. Executives also warned that stranded costs from the divestitures and early consulting spend would weigh on near-term results before the savings fully kick in. A loss near consensus, paired with continued margin gains, would show the savings are arriving faster than the stranded costs linger. A wider loss would suggest the cleanup is costing more than expected.
The tougher test is demand. New business annual contract value fell to $99 million last quarter, down from $111 million a year earlier and $114 million in the first quarter. That snapped a run of year-over-year growth that management had highlighted. Executives pointed to a qualified pipeline of about $3 billion and the strongest commercial new-capability bookings in several years. They also cited a string of wins, including a pension risk transfer engagement with Securium, Trillium Health Resources adopting its platform, an expanded Avis fleet-citation offering and the New Mexico Medicaid go-live. A rebound in signings would support the claim that last quarter was timing noise. Another soft print would make the sign-to-revenue lag look less like a delay and more like a lasting gap. Commercial revenue, which has been dragged down by volume declines at its largest client, is the segment most likely to expose that gap.
The balance sheet offers a steadier thread. The transit and tolling sales were set to bring in roughly $234 million in gross proceeds plus a 7% Quarterhill stake, earmarked for debt reduction, with net leverage at 2.8x. Progress on closing those deals and paying down debt would reinforce the most concrete part of the turnaround.
The market has turned more cautious. Sentiment has slid from solidly bullish before the last report to essentially neutral. Shares are still up 5.4% since then, beating a flat S&P 500, but at $1.57 they have given back much of a run to $2.01 and now hover just above the 200-day moving average of $1.55. In the end, this report hinges on whether bookings and commercial trends can stabilize enough that a smaller, more profitable Conduent also looks like one that can eventually grow again.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-27 | |
| Oct-23 | |
| Oct-20 | |
| Oct-01 | |
| Sep-30 | |
| Sep-24 | |
| Sep-14 | |
| Aug-27 | |
| Aug-20 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Aug-06 | |
| Aug-03 |
