Conduent Misses As Cost Cuts Lift Margins, But Shrinking Bookings And A $117 Million Cash Drain Keep The Turnaround Unproven
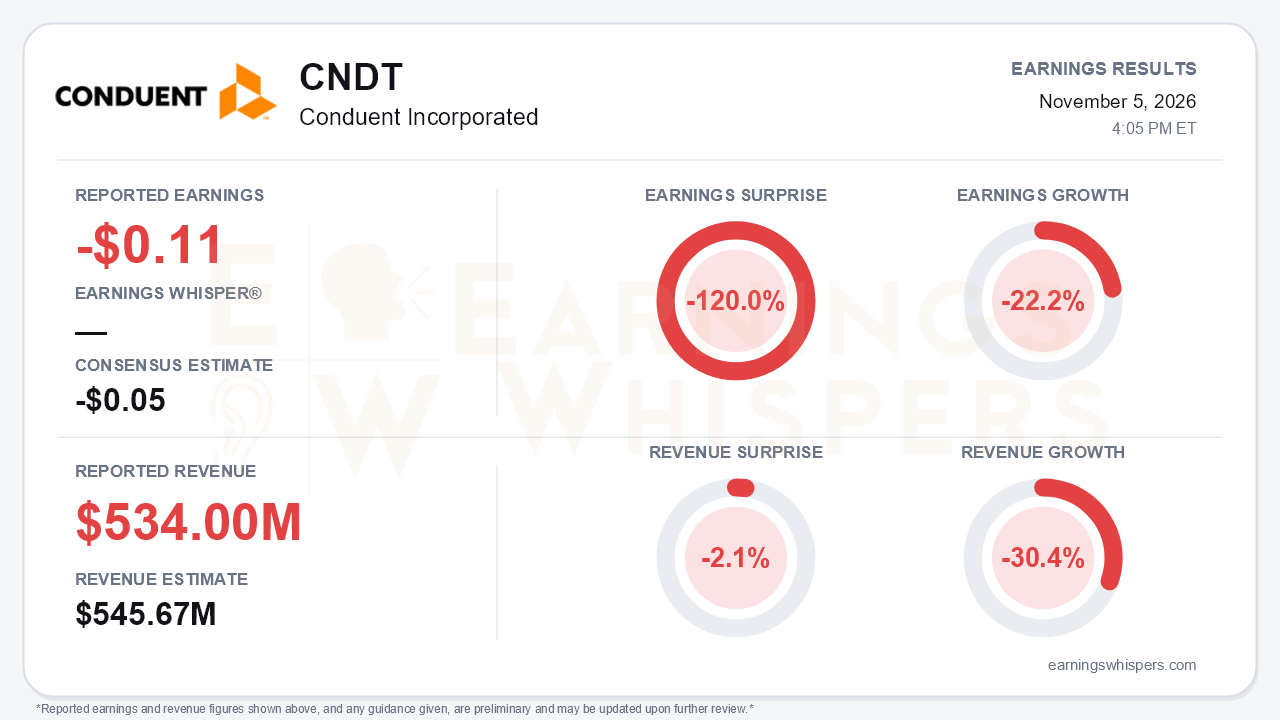
Conduent's third quarter split cleanly into two stories. The cost story is working. The growth story is not. The company reported an adjusted loss of $0.11 per share from continuing operations, against a consensus estimate of a $0.05 loss. That is a 120.0% earnings miss. Revenue of $534.0 million came in 2.1% below the $545.67 million consensus. On Earnings Whispers' normalized basis, earnings fell 22.2% year over year and revenue fell 30.4%. Management reaffirmed full-year guidance of $2.15 billion to $2.25 billion in revenue and $140 million to $170 million in adjusted EBITDA. That kept the quarter from becoming a guidance event. Still, the central tension is unchanged: Conduent is shrinking its way to better margins, and it has not yet shown it can convert its pipeline into growth.
Investors should note a reporting gap. The company's own continuing-operations presentation shows revenue down 11.7%, from $605 million, and adjusted EPS flat at -$0.11 against the restated prior-year figure. The steeper normalized declines appear to reflect comparison with prior-year results before the Public Transit and Tolling businesses were moved into discontinued operations. Either way, the top line is contracting. On the profit side, adjusted EBITDA rose 16.1% to $36 million and margin expanded to 6.7%. That compares with 5.1% a year ago and only 3.0% in Q2. Adjusted operating income turned slightly positive at $1 million, versus a $10 million loss a year earlier. The GAAP picture is weaker. The pretax loss narrowed only modestly to $35 million, because restructuring costs nearly doubled to $22 million and interest expense rose. The net loss widened to $49 million once discontinued operations are included.
The call explained where the margin gains are coming from. The cost-savings target was raised to $120 million from roughly $100 million, with $106 million identified and $55 million realized. Unallocated costs fell 16%. Government segment margin reached 27.9%, up 230 basis points. Commercial is the weak spot:
- **Commercial revenue** fell 16% to $308 million after the largest commercial client's contract ended.
- **Commercial EBITDA margin** slipped 70 basis points to 9.4%.
- **Government revenue** declined to $226 million from $238 million, citing completed implementations, lost business and lower volumes.
Management argued that churn has bottomed now that the large client is fully off, and revenue did rise sequentially. That claim is the hinge for 2027.
The forward indicators give bears legitimate ammunition. New business ACV fell to $61 million, down from $99 million in Q2, $114 million in Q1 and $152 million in Q4 of last year. Government ACV was just $16 million, as award timing slipped around elections. The qualified pipeline eased to about $2.9 billion, from roughly $3 billion in Q2 and $3.5 billion in Q1, partly because of the transportation exit. Cash flow was the sharpest negative. Adjusted free cash flow was -$117 million, versus -$54 million a year earlier, because the receivables factoring program was paused. Net leverage rose to 2.9x, and the current portion of debt jumped to $191 million.
Management can point to several offsets:
- The Transit sale closed for $164 million.
- Tolling is expected by year-end, bringing gross proceeds to about $234 million.
- The revolver was refinanced to $447 million, with maturity extended to May 2029. That removes near-term refinancing risk.
- Roughly 30 government proposals worth about $380 million await award.
- Management cited around 10 additional states interested in its Medicaid suite, building on the up-to-14-year Virginia contract.
- The cyber-event class action is expected to be fully insurance-funded.
- The investor-day targets for 2028 call for double-digit EBITDA margins, positive free cash flow and 1.5x net leverage.
Investor expectations had already cooled sharply. Earnings Whispers sentiment fell from 0.58 to 0.08, a substantial drop that leaves it barely positive. Price action has been volatile rather than directional:
- Shares closed at $1.65 on the eve of the report, up 10.7% from the $1.49 open after the August release.
- That was 7.3% above the 200-day moving average of $1.54.
- The stock sat 17.9% below the September 3 high of $2.01, set around the investor day.
- It was 22.2% above the October 19 low of $1.35.
In short, the stock gave back much of its investor-day enthusiasm before partially recovering. The negative AVWAP reading points to a weak buying trend since the August report.
The bottom line is that Conduent delivered on what it controls. It cut costs, expanded margins, cleaned up its portfolio and pushed out its debt maturities. It missed on what the market ultimately needs: bookings, revenue and cash. The reaffirmed outlook and the refinancing lower the risk of a near-term blow-up. But with ACV falling for three straight quarters and leverage moving the wrong way, the turnaround now depends on pending government awards turning into signed contracts and on factoring-related cash flows normalizing.
Read our earnings preview for Conduent Incorporated: https://www.earningswhispers.com/article/CNDT/22262
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-27 | |
| Oct-23 | |
| Oct-20 | |
| Oct-01 | |
| Sep-30 | |
| Sep-24 | |
| Sep-14 | |
| Aug-27 | |
| Aug-20 | |
| Aug-10 | |
| Aug-10 |
