Microsoft Tops Consensus But Falls Just Short Of The Whisper As Azure Accelerates To 48% And Windows OEM Collapses
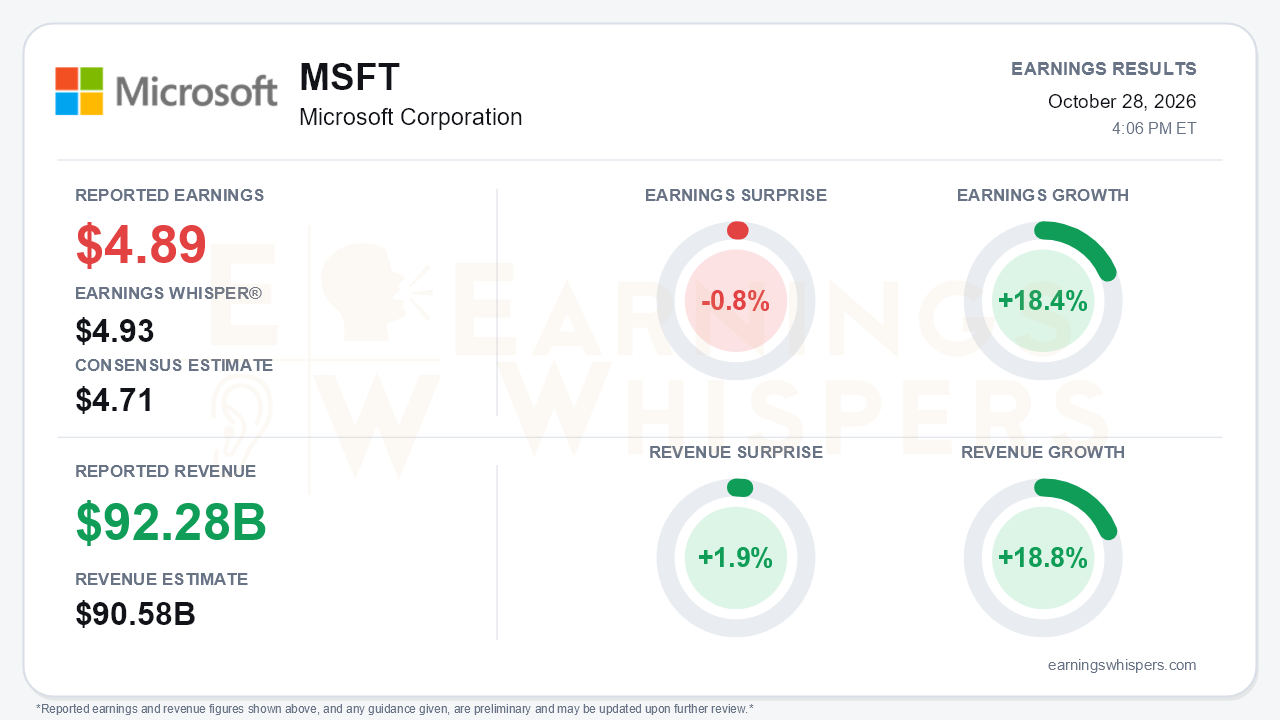
Microsoft delivered a quarter in which the cloud engine accelerated sharply, yet the headline still landed as a technical miss. Fiscal first-quarter earnings of $4.89 per share cleared the $4.71 consensus but fell 0.8% short of the $4.93 Earnings Whisper number. Revenue of $92.28 billion beat the $90.58 billion consensus by 1.9% and grew 18.8% year over year, ahead of management's own 16-17% growth guide. Earnings grew 18.4%. The narrow whisper shortfall matters less than what sits beneath it. Azure growth hit 48%, and guidance pointed to further acceleration. Against that, the legacy Windows and seat-based franchises are deteriorating faster than management expected. That is the central tension of the report.
The quality of the quarter deserves scrutiny in both directions. The headline release only pointed investors to the full results, so the detailed figures come from the call, and the GAAP versus non-GAAP basis of the EPS figure was not spelled out. Operating margin of roughly 50% compared with 45% in the fourth quarter of fiscal 2026 and a guide for flat year-over-year margins. Operating cash flow rose 29% to $58 billion. Even so, earnings growth trailed revenue growth slightly. That suggests the operating leverage did not fully reach the per-share line and that something below operating income absorbed part of the gain. Free cash flow also slipped to $18.6 billion from $19.6 billion in the prior quarter.
The cloud trajectory is the strongest part of the story. Azure growth has stepped up every quarter: 39%, then 40%, then about 43%, and now 48%. The latest figure beat a roughly 45% guide despite delayed third-party GPU capacity, and the second quarter is guided to 49-50% in constant currency. Microsoft Cloud revenue reached $63.9 billion, up 30% versus 27% last quarter. M365 commercial cloud grew 18% adjusted against a roughly 16% guide, with about 19% expected next quarter. The AI platform metrics broadened as well:
- Foundry customers rose to 120,000 from 100,000, and Foundry revenue more than tripled.
- Fabric paid customers reached 44,000.
- Agent 365 surpassed 50 million agents.
- Customers with 50,000-plus Copilot seats grew 8x.
Remaining performance obligation reached $677 billion, up 73%, with the portion beyond 12 months up 98%. Satya Nadella said he has 'never been more confident.'
Bears still have legitimate ammunition:
- **Windows OEM:** Revenue fell 27%, below a low-20s guide and versus a 5% decline last quarter. Management guided to a mid-30s decline in the second quarter, citing elevated channel inventory and weak PC demand.
- **Seat execution:** Microsoft acknowledged weaker execution in E3 and standalone SKUs. Paid commercial seat growth slowed to 5% from 6%, and the Copilot seat count, last given as 30 million-plus, was not updated.
- **Bookings:** Commercial bookings fell 12% versus a 10% gain last quarter. Management attributed the drop to a tough OpenAI-driven comparison, a decline that sits uneasily beside the surging RPO.
- **Consumer:** M365 consumer cloud growth is decelerating from 24% to 17%, with a low-teens guide next.
- **Margins:** Cloud gross margin is guided to about 65%, down from 66%.
Capital spending is a two-sided signal. Calendar 2026 capex has drifted from about $190 billion to about $170 billion, partly because of a lease reclassification and partly because of supply delays. The lower figure flatters near-term cash flow but reflects capacity Microsoft wanted and could not get. Management also signaled openness to debt and lease financing as spending accelerates. Upcoming catalysts include NVIDIA Vera Rubin deployments, Maia 300, a new segment structure, and GTA VI on Xbox.
The market setup is more complicated than the narrow miss implies. Shares entered the report at $531.33, up 21.3% since the open following the July report and 21.5% above the 200-day moving average. The stock sat just 3.6% below its October 13 inter-earnings high of $551.15, after rallying almost 23% off the low set the day after the prior release. Investor sentiment remained negative but improved modestly, from -0.24 to -0.21. That leaves a skeptical crowd behind a stock already priced for strength. The Earnings Whispers trend readings were uniformly positive heading into the report, consistent with that run-up.
The bottom line is that Microsoft's growth story is getting stronger where it matters most. Azure, Microsoft Cloud, and the revenue guide of 18-19%, or $96-97.1 billion, all moved higher. The whisper miss reflects how elevated expectations had become rather than a fundamental stumble. Still, collapsing Windows OEM, slowing seat growth, falling bookings, and supply-constrained capex mean the quarter was not a clean sweep. With shares near their highs, investors will need the 49-50% Azure guide to hold.
Read our earnings preview for Microsoft Corporation: https://www.earningswhispers.com/article/MSFT/20961
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 37 min | |
| 38 min | |
| 53 min | |
| 1 hour | |
| 1 hour | |
| 1 hour | |
| 1 hour | |
| 2 hours | |
| 2 hours | |
| 2 hours | |
| 2 hours | |
| 2 hours | |
| 2 hours | |
| 2 hours | |
| 2 hours |
