CVRx Faces A Credibility Test As Sales-Force Repairs Meet A Lowered Revenue Bar
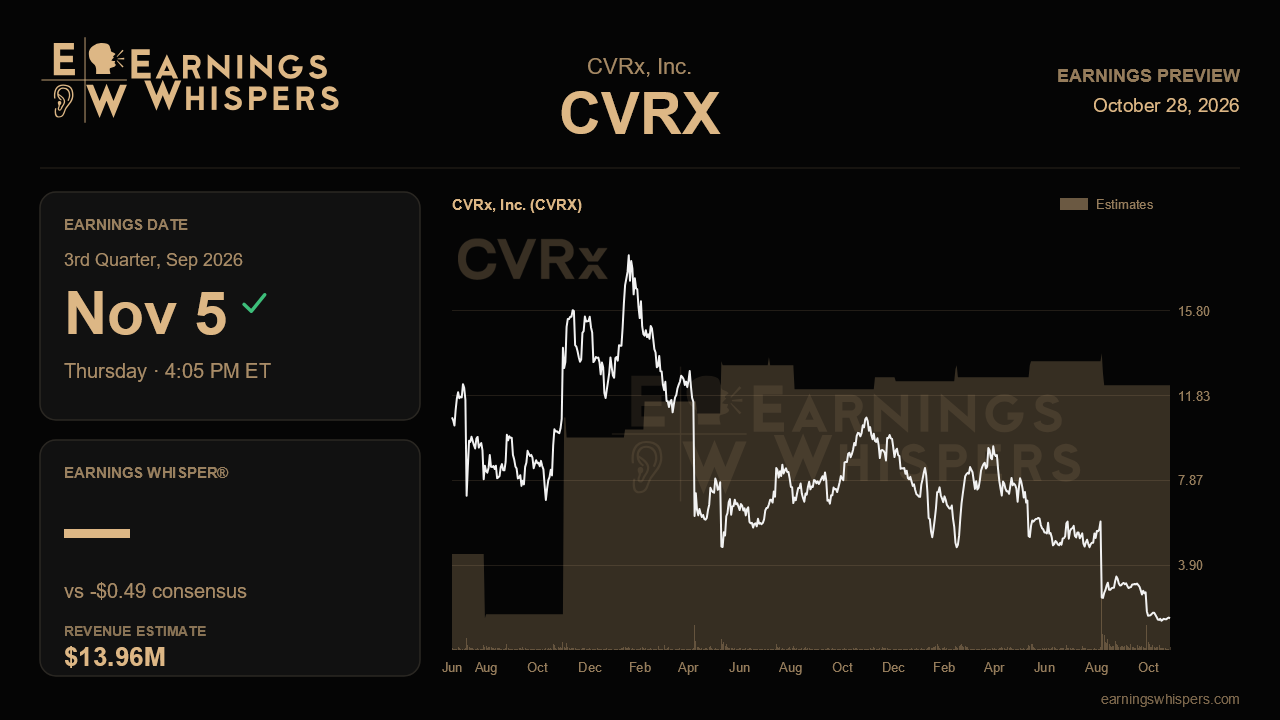
CVRx enters its third-quarter report with a problem it built itself. Three months ago, after three straight calls promising a return to mid-teens growth in 2026, management cut its full-year revenue outlook and blamed its own sales organization rather than weak demand for Barostim. The stock has since lost more than half its value. The question now is not whether CVRx can impress. It is whether the company can show that the damage was contained to the quarter it was disclosed.
Wall Street expects a loss of $0.49 per share, matching the year-ago result and slightly narrower than the $0.53 loss last quarter. Revenue is forecast at $14.0 million, about 5% below the $14.7 million reported a year earlier and a clear step down from the second quarter's $15.7 million. That consensus sits at the midpoint of management's $13.5 million to $14.5 million guidance, so analysts have fully adopted the company's reset. Full-year guidance now stands at $58 million to $60 million, down from the $63 million to $67 million range set at the start of the year and reaffirmed only one quarter earlier. With the Street exactly in line with guidance, a print near the top of the range would suggest management set a cautious bar. A result near the bottom would raise doubts that the reset went far enough.
The sales force is the most important issue. Management said roughly 60% of quota-carrying reps joined within the past 18 months, that onboarding capacity was overwhelmed, and that turnover topped 50% in certain regions led by the least experienced managers. Those regions posted negative implant growth, offsetting solid double-digit gains in areas with seasoned leadership. Territory expansion is frozen at 56, and active centers grew by only one to 258. Clear signs of improvement would include lower turnover, better productivity among newer reps, and an early indication that the weaker regions have stopped shrinking. If management instead describes continued attrition or further reorganization, the problem will look larger than a single bad quarter.
The reimbursement picture is mixed and deserves close attention. Overall 30-day Medicare Advantage prior-authorization approvals rose to 60% from 44% in 2025. Humana's written coverage policy is producing approvals above 90%, and traditional Medicare is paying about 96% of claims. Against that, the largest Medicare Advantage payer's AI-driven review tools have pushed its approval rate below 30%, which management said has made some physicians hesitant. Any update on that payer could affect fourth-quarter expectations. Margins look steadier. Gross margin reached 87% last quarter, and lowering the operating expense outlook to $99 million to $101 million should help keep losses in check even with soft revenue. Updates on the DOJ civil investigative demand and the CFO search could also move the stock.
Sentiment has changed noticeably. Earnings Whispers readings have gone from strongly bearish before the last report to roughly neutral now. That probably reflects the sense that the worst news is already priced in after a 53% decline, compared with a roughly flat S&P 500. At $1.42, the shares trade far below the 200-day moving average of $5.37 and sit nearer the post-earnings low of $1.26 than the $3.42 high. That positioning leaves room for a relief rally but offers little protection if the guidance proves too optimistic.
The key question is whether CVRx can show that its sales-execution problems are stabilizing. Encouraging items such as BENEFIT-HF enrollment running ahead of plan, real-world evidence publications expected this fall, and a higher inpatient payment rate support the long-term case. They will carry little weight until the company delivers a quarter that confirms its lowered guidance and shows the weaker regions are no longer losing ground.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-22 | |
| Sep-29 | |
| Sep-21 | |
| Aug-25 | |
| Aug-24 | |
| Aug-24 | |
| Aug-24 | |
| Aug-11 | |
| Aug-07 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 | |
| Jul-28 |
