CVRx Cuts Guidance Again As Payer Friction Pushes Growth Into Reverse And Implied Q4 Plunges
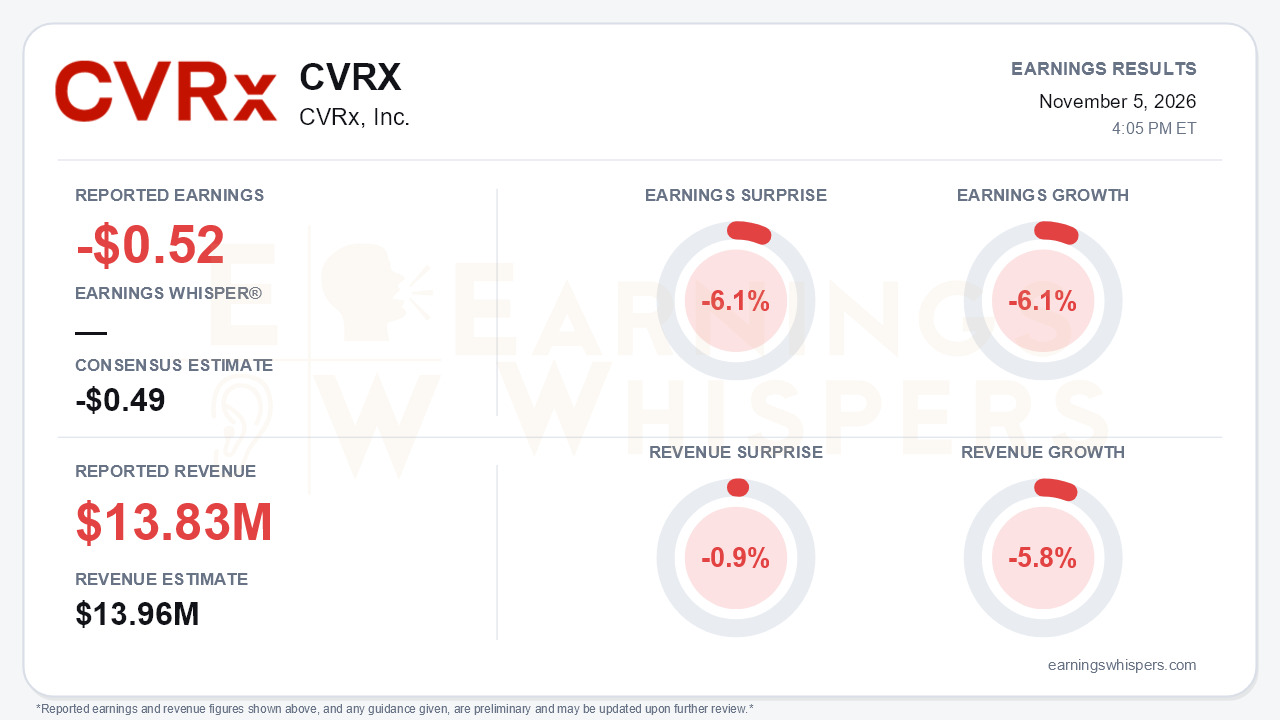
CVRx reported a third-quarter loss of $0.52 per share, missing the consensus estimate of -$0.49 by 6.1%. Revenue of $13.83 million came in 0.9% below the $13.96 million consensus and fell 5.8% from a year ago. The modest revenue miss is not the main story. The trajectory is. Revenue growth went from roughly +20% in the first quarter and +16% in the second to a decline in the third. Management also cut full-year 2026 revenue guidance for the second consecutive quarter, to $56.0-$57.0 million from $58.0-$60.0 million. Entering the year, the target was $63-$67 million. The implied fourth-quarter range of $11.7-$12.7 million compares with $16.0 million a year ago, which signals a sharp year-over-year decline is coming.
The quality of the quarter deserves scrutiny, because even the reported $13.8 million was flattered. The company said a larger annual purchase it would otherwise have expected in the fourth quarter landed in the third. That pull-forward more than offset higher-than-usual implants at centers drawing down existing inventory. U.S. revenue fell 4% to $13.0 million, and U.S. revenue units slipped to 412 from 420. Management attributed the declines to lower sales force productivity and a prolonged problem with one of its largest payers. Europe fell 27% on 38 units versus 50. Gross margin held at 87%, and the full-year margin guide of 86-87% is up from 84-86% at the start of the year. That is the clearest bright spot, but margin stability on a shrinking revenue base does not fix the problem. Operating expenses were essentially flat at $25.0 million, and the net loss widened to $14.2 million from $12.9 million as interest income fell and interest expense rose.
The call showed that reimbursement friction has moved from an execution issue to an entrenched headwind. UnitedHealthcare's Medicare Advantage approval rate collapsed to roughly 12%, versus 83.5% a year ago and the sub-30% cited last quarter. The company said the payer is denying essentially all prior authorizations and appeals. The overall MA 30-day approval rate fell to 51% from 60% in the second quarter. Management also described two newer headwinds as structural:
- **Physician champion turnover.** About 57% of heart-failure fellowships are unfilled, and rebuilding a program takes three to four quarters.
- **Health-system pauses.** Some systems are holding implants until payment is confirmed across payers, including one system with more than a dozen approved patients on hold.
The tone shift across 2026 is telling. Management went from describing positive momentum across the business in the first quarter, to an execution problem in the second, to headwinds that are "more impactful and more persistent" now.
The call did preserve some credible pieces of a longer-term story:
- **Coverage gains.** A second top-10 Medicare Advantage payer issued a written coverage policy. Together with Humana, these policies cover about 21% of MA lives, and Humana approvals run around 80-90%.
- **Reimbursement.** The inpatient payment rate rose to $45,000 from $43,000, and all first-quarter traditional Medicare outpatient claims were paid.
- **Sales force stability.** Sales turnover hit its lowest level in over two years, and five of nine regions are growing procedures above 20%.
- **Clinical evidence.** REBALANCE registry data presented at HFSA showed ejection fraction gains of 4.8 points at 12 months and 8 points at 24 months.
- **Label expansion.** BENEFIT-HF is enrolling, and FDA discussions on a real-world-evidence label-expansion pathway are underway, with protocol agreement hoped for in 2027.
These are genuine catalysts, but they are slow-moving ones against near-term revenue erosion.
The balance sheet gives bears legitimate ammunition. Cash fell to $58.7 million from $64.6 million last quarter and $75.7 million at year-end, with $11.0 million burned in the third quarter alone. Long-term debt rose to $58.7 million, and stockholders' equity shrank to $13.8 million from $39.3 million. The company tapped roughly $6 million through its at-the-market program after previously saying it did not need to raise. That is a dilution signal, and share count rose to 28.5 million from 26.3 million at year-end. Restructuring and severance were taken, the DOJ civil investigative demand remains outstanding, and legal expense rose $0.7 million. The CFO seat is also turning over. The release says John Landry's appointment takes effect November 6, while the call described him as having joined in October.
The market had already priced in much of the damage. Shares closed at $1.58 heading into the report, down 47.5% from the $3.01 open after the August release. That leaves them about 70% below the $5.23 200-day moving average. The stock hit a 52-week low of $1.26 on October 16 and entered the print about 26% above that level. Investor sentiment improved notably, from -0.42 to -0.06, but it remained slightly negative. That suggests some investors saw capitulation, not that confidence was restored. Price, momentum and AVWAP trend readings remain negative.
The bottom line is that CVRx's quarter was worse than the small headline misses suggest. Revenue was propped up by a pulled-forward order, guidance was cut again, and management now characterizes its payer and physician headwinds as persistent. Coverage wins, higher reimbursement rates and the label-expansion path keep a long-term thesis alive. But with cash declining, debt rising, equity thin and dilution underway, the burden of proof sits squarely on the company to show that payer friction is stabilizing before the balance sheet forces harder choices.
Read our earnings preview for CVRx, Inc.: https://www.earningswhispers.com/article/CVRX/22270
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-02 | |
| Oct-28 | |
| Oct-22 | |
| Sep-29 | |
| Sep-21 | |
| Aug-25 | |
| Aug-24 | |
| Aug-24 | |
| Aug-24 | |
| Aug-11 | |
| Aug-07 | |
| Aug-07 |
