CareTrust Heads Into Q3 With Record Deals Behind It And An 11% Stock Slide To Explain
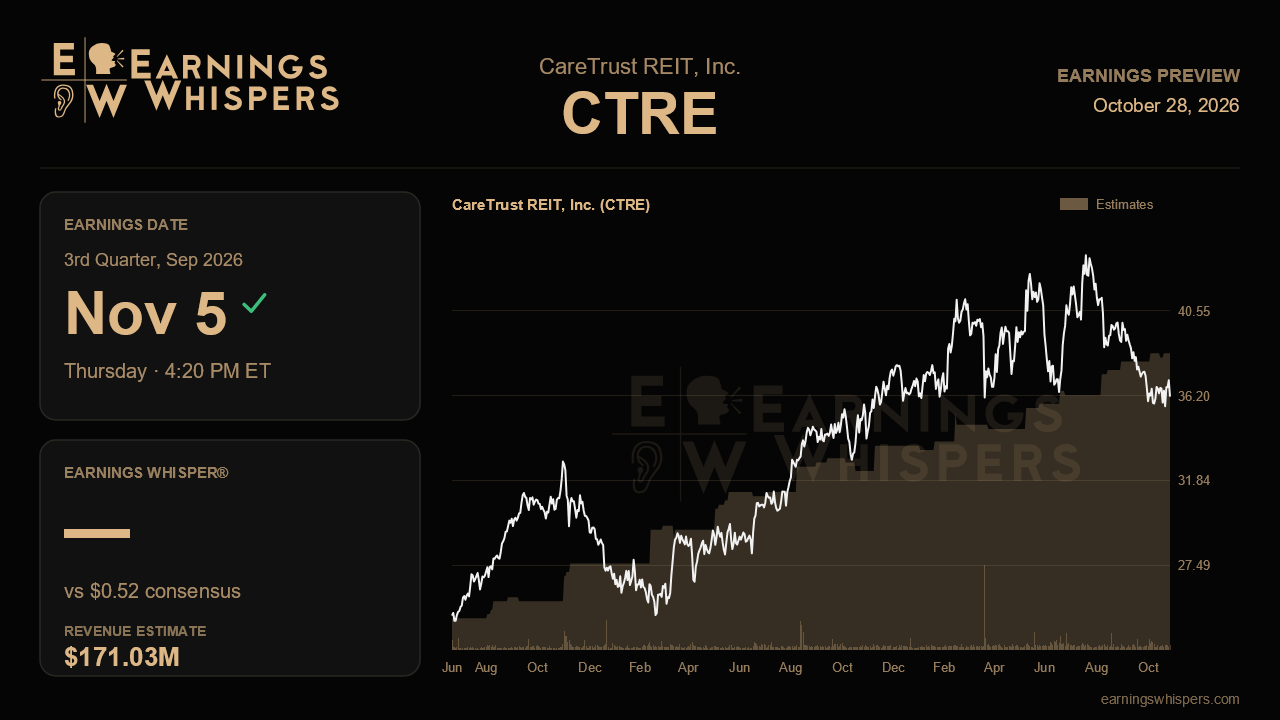
CareTrust REIT has spent 2026 doing almost everything a growth-minded landlord could ask for: record acquisition volume, two straight guidance increases and a balance sheet that barely carries any debt. Yet the stock has fallen nearly 12% since the last report while the S&P 500 went essentially nowhere. That gap frames the third-quarter release due after the close on November 5. The question is less whether CareTrust can keep growing and more whether the market will keep paying for growth that is increasingly bought at thinner yields.
The Street expects earnings of $0.52 per share on revenue of about $171.0 million. That works out to roughly 15.6% per-share growth and a 29.1% jump in revenue from a year ago, which is strong by any REIT standard. The difference between those two figures matters. Revenue is growing almost twice as fast as per-share earnings, a reminder that the acquisition machine has been financed partly with new equity. The sequential step from $0.51 last quarter is modest, which is about what a full quarter of contribution from the record second-quarter deal haul should produce. Management lifted its full-year normalized FFO outlook to $2.03 to $2.06 per share, up from $2.00 to $2.04 and well above the initial $1.90 to $1.95. The consensus of $2.05 sits in the upper half of that range. Analysts already assume CareTrust delivers near the top, so a third consecutive raise would need real substance to impress.
The main test is whether the second quarter's surge in deals turns into earnings as cleanly as management suggested. CareTrust put about $900 million to work in that quarter at an 8.9% blended yield, which management described as a full year's worth of investing in three months. It then closed another roughly $308 million after quarter end, including a 16-property UK care home portfolio with a new operator. That UK deal was pitched as a beachhead, backed by a London-based team that is widening the search for opportunities. Investors should want early signs that the new operator relationship is performing and that the UK pipeline is producing follow-on deals rather than a single trophy transaction.
Yield is the pressure point. The post-quarter tranche priced at 7.8%, about a full percentage point below the 8.8% to 8.9% yields of earlier quarters, reflecting the UK and senior housing mix and tighter cap rates. Management treats this as discipline rather than deterioration, and it has avoided the all-in senior housing operating push some peers made, citing private capital crowding into a market where top assets trade at cap rates in the fives. A reloaded pipeline that holds near 8% or better, with skilled nursing still the core, would support the story. A pipeline that leans further into lower-yielding assets would suggest spread compression is becoming structural. Tenant purchase options are another swing factor. Management considers their exercise highly likely, so any update on timing and on how the proceeds will be redeployed will affect next year's run rate.
Sentiment has cooled slightly, from 15.1% bullish to 12.6%, and the stock at $36.14 sits below its 200-day moving average near $39 and close to the $35.28 low of its post-earnings range. That is well off the $43.62 peak of the prior quarter. Expectations on the fundamentals look full, while the share price reflects real skepticism, a combination that leaves room for a relief rally if the yield story steadies.
In the end, the report hinges on spread durability. If CareTrust can show that its record deployment is lifting per-share results on schedule, and that new investments can still clear the company's cost of capital by a healthy margin, the acceleration narrative stays intact. If yields keep sliding while growth relies on issuing more equity, the market's recent doubts may prove justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-25 | |
| Oct-09 | |
| Oct-02 | |
| Oct-02 | |
| Sep-17 | |
| Sep-15 | |
| Sep-15 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Jul-23 | |
| May-18 | |
| May-18 |
