CareTrust REIT Beats And Raises Again, But Lower Deal Yields And Rising Leverage Leave The Stock Behind
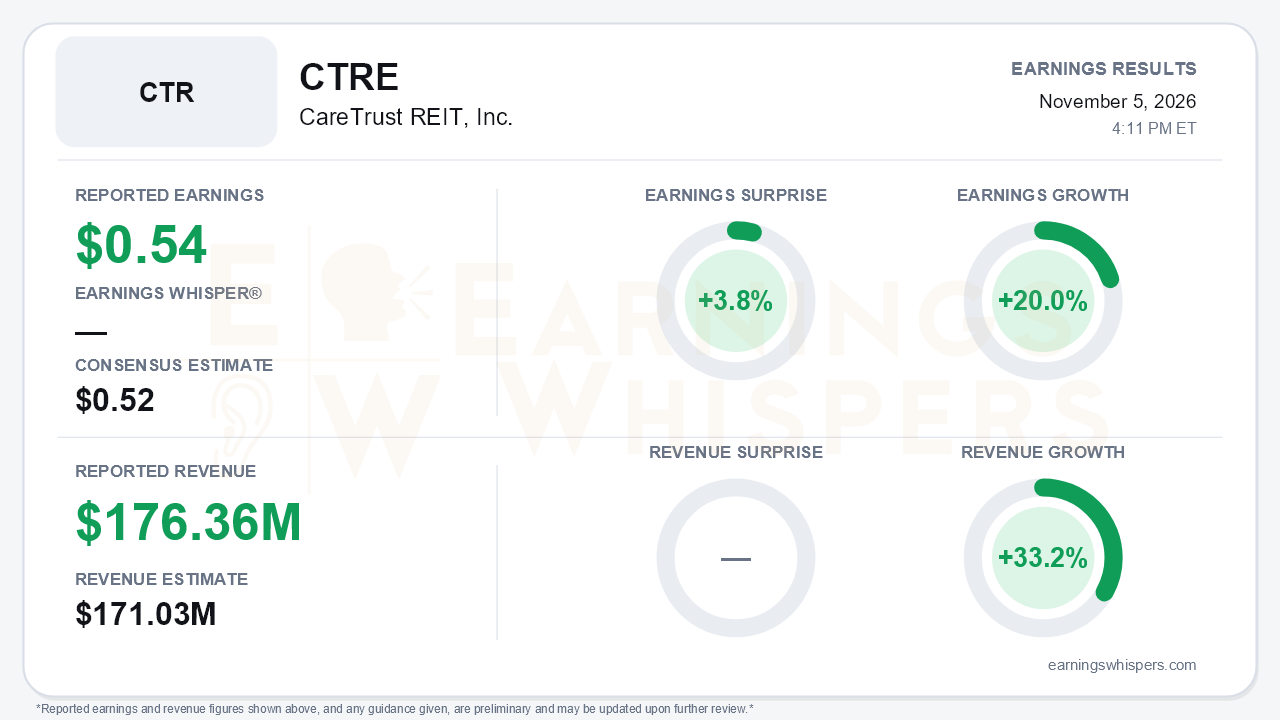
CareTrust REIT delivered another quarter of accelerating per-share growth. Normalized FFO came in at $0.54 per share, ahead of the $0.52 consensus by 3.8% and up 20.0% from a year ago. Revenue of $176.36 million beat the $171.03 million estimate by 3.1% and grew 33.2% year over year. The company also raised full-year guidance for a fourth time. Even so, the stock has fallen 9.3% since the opening after the August report and sits below its 200-day moving average. That gap is the central tension. The operating machine is accelerating, while the market is questioning the cost and quality of the capital fueling it.
The per-share trajectory is the strongest part of the story. Normalized FFO has stepped up from $0.45 a year ago to $0.47, $0.48, $0.51 and now $0.54. Year-over-year growth has accelerated from 14% in the first quarter to 19% in the second and 20% in the third. That progress came despite a diluted share count roughly 13% larger than a year ago, so the external growth model is producing real accretion rather than simply a bigger balance sheet.
GAAP results tell a flatter story. Net income per diluted share was $0.35, unchanged from the prior year. That figure was weighed down by $8.9 million of transaction costs tied to the U.K. deal and a $7.3 million unrealized loss on other real-estate-related investments. Investors focused on normalized metrics can reasonably look past both items. Still, interest expense rose about 40% year over year to $17.7 million, which signals that the funding mix is shifting toward debt.
The raised guidance now calls for Normalized FFO of $2.08 to $2.09 per share, up from $2.03 to $2.06 in August. That implies roughly $0.55 to $0.56 in the fourth quarter. The company lifted the low end of the range, and management framed the midpoint as 18.5% growth over 2025. The guide excludes any investments not yet made or announced.
The call reinforced how much the platform is changing. Year-to-date investments reached about $2.9 billion, compared with $1.8 billion for all of 2025. The pipeline more than doubled from $540 million last quarter to roughly $1.2 billion. The centerpiece is the LNT Care Developments partnership, under which CareTrust is acquiring 45 newly built U.K. care homes for about £1.1 billion. The first 23 homes closed October 1 for $733 million. They are leased triple-net, with a planned conversion to an operating (SHOP) structure at a high-7% to low-8% first-year yield.
- **Timing discrepancy:** The release describes 22 remaining homes closing on a rolling basis through 2027. The call analysis cites 21 homes closing January through September 2027.
- **Further optionality:** Management discussed a possible acquisition of the full development company, which would bring a 150-plus site pipeline, and buying operating companies at roughly 20% yields on in-place EBITDA later in 2027.
- **U.S. SHOP:** U.S. senior housing operating deals now make up about 20% of the pipeline, up from none last quarter.
- **Skilled nursing credit:** SNF EBITDAR coverage reached a record 2.62x, up from 2.25x in the first quarter.
- **2027 outlook:** Management guided to double-digit 2027 FFO-per-share growth funded by existing capacity, and its tone was notably bullish.
Bears have legitimate ammunition, however. Blended investment yields slipped to 8.3% this quarter from 8.9% last quarter as the mix shifted toward U.K. and SHOP assets, and the year-to-date blend is 8.1%. The LNT price of about $500,000 per unit appears to exceed replacement cost, so returns hinge on lease-up and execution of the SHOP conversion. Net debt to EBITDA rose from 1.0x to 1.4x and is about 2.7x pro forma. That remains well below the 4x to 5x target, but the direction is clear. Analysts also pressed on growth durability into 2028 as rates rise, noting that higher rates could slow roughly $340 million of tenant purchase-option exercises. Additional risks include currency exposure, U.K. tax leakage and post-midterm skilled-nursing policy.
The new $700 million term loan and a $2.0 billion revolver push liquidity to about $2.3 billion, which addresses near-term funding concerns. The dividend remains well covered at about 74% of Normalized FAD.
Investor sentiment improved meaningfully into the report, rising from 0.15 to 0.29. That is still moderately positive rather than euphoric. The price action tells a cooler story: shares at $37.18 sit 4.6% below the 200-day average of $38.99, and the call analysis noted the stock was flat on the results. The market appears to be pricing the rate sensitivity of a model that depends on cheap equity and spread investing more than it is pricing the earnings acceleration itself.
The bottom line is that CareTrust posted a high-quality beat-and-raise quarter. Normalized FFO growth is accelerating, guidance is moving steadily higher and the LNT relationship extends the runway well into 2027. The debate has shifted from whether CareTrust can grow to what that growth will cost. Thinner going-in yields, higher leverage and greater operating and international exposure explain why a stronger fundamental story has not yet lifted the shares.
Read our earnings preview for CareTrust REIT, Inc.: https://www.earningswhispers.com/article/CTRE/22269
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-06 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-25 | |
| Oct-09 | |
| Oct-02 | |
| Oct-02 | |
| Sep-17 | |
| Sep-15 | |
| Sep-15 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 |
