EOG Heads Into Q3 Needing International Follow-Through As Earnings Cool From Record Q2
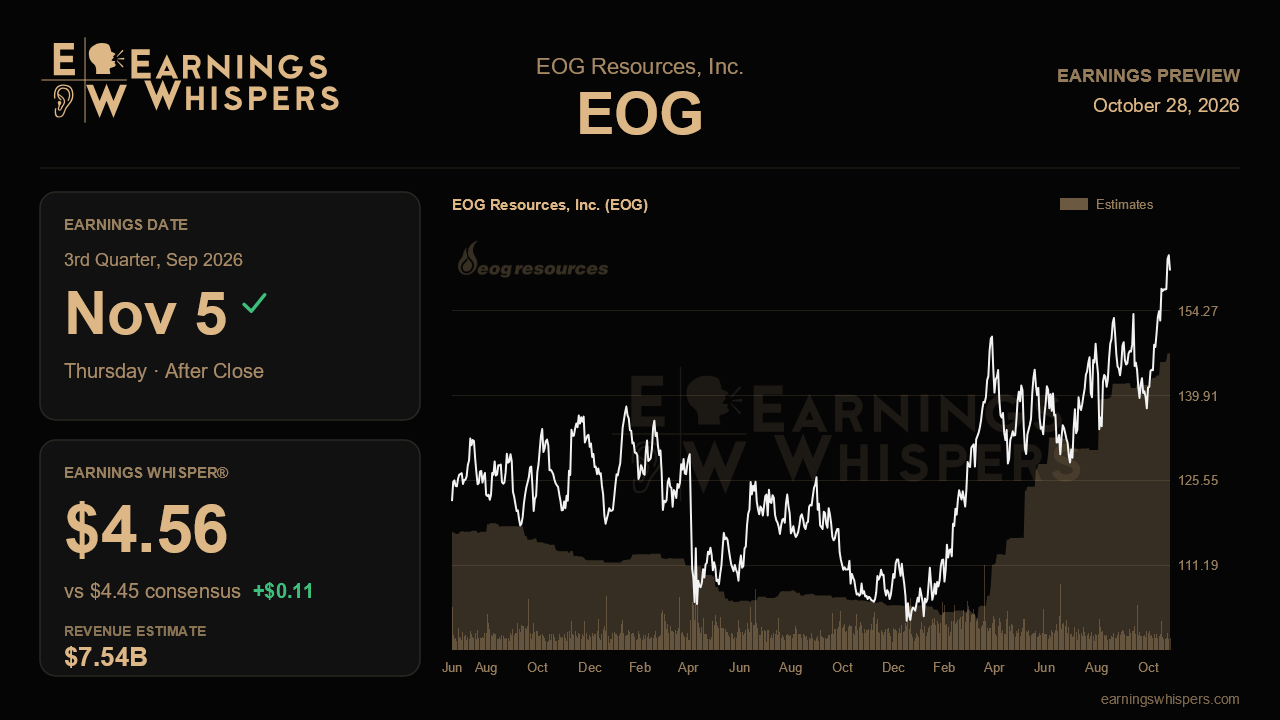
EOG Resources enters its third-quarter report with an unusual mix of momentum and moderation. Last quarter the company posted record results and, more importantly, turned its international unconventional strategy from a slide-deck promise into hard data. This time the Street expects earnings to come in below that peak. That makes the November 5 release, due after the close, less about the headline number and more about whether the operational story keeps compounding while commodity tailwinds ease.
Consensus calls for earnings of $4.45 per share on revenue of $7.54 billion. That is a step down from the $5.07 and $8.62 billion EOG delivered in the second quarter, which implies analysts are modeling softer realized pricing rather than any operational slippage. On a year-over-year basis the picture is still very strong: EPS would be up roughly 64% from $2.71 and revenue up 29%. The Earnings Whisper of $4.56 sits modestly above consensus, a signal that the informal bar is somewhat higher than the published one, though not dramatically so. Management did not issue fresh quarterly guidance, so the reference points are its full-year framework: 14% total production growth, raised from 13%, oil growth of 5%, and capital spending held at $6.5 billion.
The most important test is international. In the second quarter EOG reported that two one-mile wells in the United Arab Emirates averaged more than 25,000 barrels of oil per day each over their first 30 days, well ahead of expectations, after earlier calls had seen those results slip. Management said it would move to laterals longer than two miles in the second half using locally sourced sand. Any early read on those longer wells, and whether the initial rates are holding up, would go a long way toward validating management's newly assertive stance that the overseas opportunity is real. Bahrain is the counterweight. Operations there were intermittent because of regional conflict and results were pushed into the second half, so another delay would temper enthusiasm without breaking the thesis.
Domestically, the newly disclosed Austin Chalk position in Lavaca County deserves attention. EOG described roughly 60,000 net acres picked up cheaply, with payouts under a year at $65 oil and enough locations to extend its San Antonio-area inventory by about a year. Additional well results or a sense of development pace would show whether this is a meaningful growth lever or simply a nice option. Costs are the other swing factor. Management cited record-low well costs in the Eagle Ford, Delaware and Utica, but also acknowledged slight service inflation for the first time this year. Holding the line on low-single-digit well-cost reductions would confirm that efficiency gains are outrunning price pressure.
Cash returns round out the checklist. EOG returned $1.8 billion in the second quarter, including $1.3 billion of buybacks, and has $11.7 billion left on its authorization. Its full-year free cash flow estimate at strip prices was trimmed to about $8 billion from $8.5 billion, so a further cut tied to prices would be understandable, but one tied to costs or volumes would not.
The market has already rewarded the story. Shares have gained about 12% since the last report while the S&P 500 slipped, and at $161.10 the stock trades well above its 200-day moving average and within roughly 2.5% of its post-earnings high of $165.11, putting a breakout within reach. Sentiment remains mildly bearish but slightly less so than before last quarter, suggesting skepticism is fading rather than gone. The central question is whether EOG can show that its edge lies in execution, not just oil prices: steady volumes near the raised production target, contained costs and fresh evidence from the UAE would keep the narrative intact even if earnings come in below the record set in the second quarter.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-16 |
Oil Stocks To Buy: EOG Resources Attempts A New Breakout, But Beware This Risk
EOG
Investor's Business Daily
|
| Oct-14 | |
| Oct-13 | |
| Oct-12 | |
| Oct-08 | |
| Oct-07 | |
| Sep-24 | |
| Sep-23 | |
| Sep-22 | |
| Sep-19 | |
| Sep-16 | |
| Sep-15 | |
| Sep-01 | |
| Aug-22 |
