EOG Resources Beats Handily, But Sequential Cooling And Creeping Costs Temper A Record-Volume Quarter
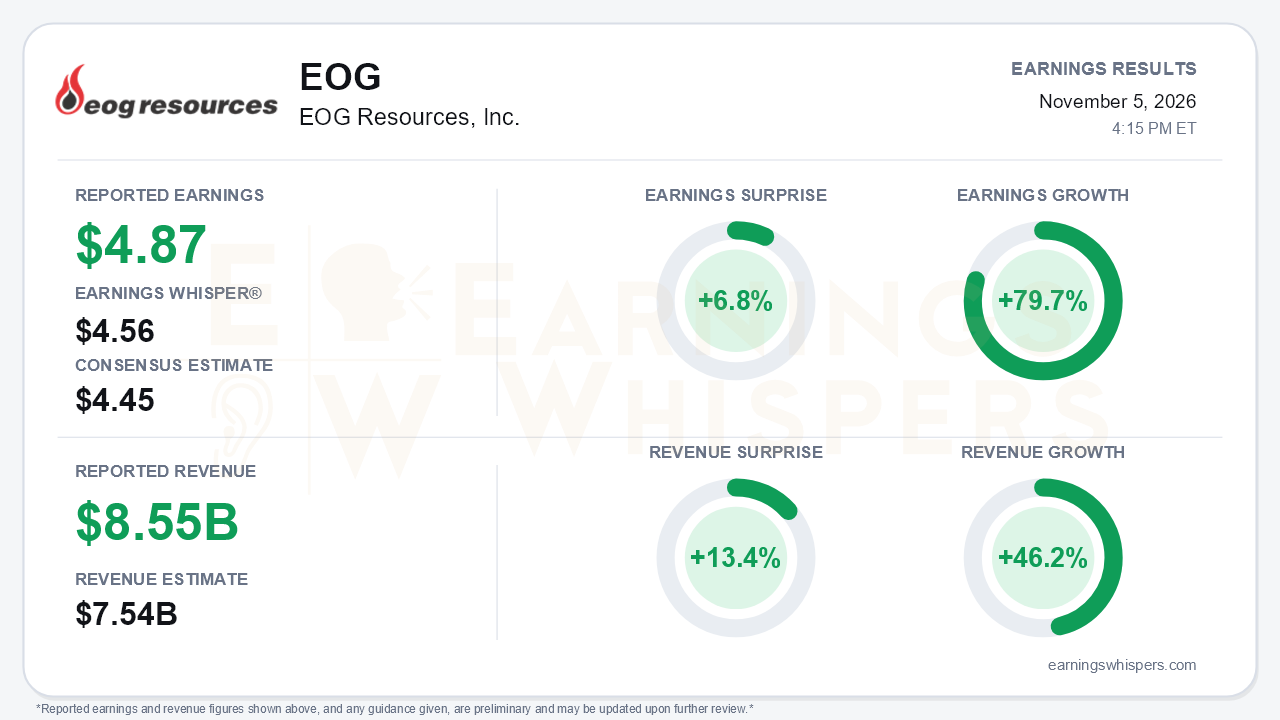
EOG Resources delivered a clean beat in the third quarter. Adjusted earnings of $4.87 per share topped the $4.45 consensus by 6.8% and cleared the $4.56 Earnings Whisper number. Revenue of $8.549 billion beat the $7.54 billion consensus by 13.4%. Year-over-year comparisons are striking: earnings grew 79.7% and revenue grew 46.2%, helped by a full year of Encino volumes and far higher oil prices than a year ago. The central tension is that this was a strong quarter that still stepped down from the second-quarter peak. Adjusted EPS fell from $5.07, adjusted cash flow from operations fell from $4.39 billion to $3.77 billion, and free cash flow dropped from a record $2.8 billion to $2.2 billion as WTI eased from $92.85 to $85.68.
The quality of the beat holds up well, though the headline figures need some care. GAAP EPS of $5.33 includes $242 million of pre-tax gains on asset dispositions, tied to the Barnett and Woodford divestiture. Adjusted EPS strips those gains out, so the adjusted beat rests on operations. Reported revenue is a different matter. It includes that $242 million gain and $105 million of mark-to-market derivative gains, which inflate the top-line surprise somewhat.
Operationally, the details are excellent:
- Total production reached a record 1,433.1 MBoe/d, 20.9 MBoe/d above the guidance midpoint.
- NGLs alone ran 10.1 MBbl/d ahead of guidance.
- Cash operating costs of $10.49 per Boe came in $0.21 below guidance.
- DD&A came in $0.20 below guidance.
- Capex of $1.597 billion was $53 million under plan.
The sequential earnings decline is a price story, not an execution story. EOG's own bridge attributes $0.49 per share of drag to lower realizations, partly offset by volume growth.
The call added substance beyond the numbers:
- **Delaware Basin:** Well results moved from "in line" at the second-quarter call to "above expectations."
- **Drilling efficiency:** Utica drilled feet per day rose 24%, and Eagle Ford completed lateral footage improved 15% versus 2025.
- **Guidance:** Full-year targets of roughly 5% oil growth, 14% total growth and $6.5 billion of capex were held despite divesting about 16 MBoe/d.
- **Free cash flow outlook:** 2026 free cash flow at strip rose to $9.7 billion from $8.0 billion a quarter ago.
- **2027 preview:** Management framed low single-digit oil growth as the base case, replacing earlier "too early" language.
The cost narrative, however, has drifted the wrong way across three calls. It went from no significant inflation, to slight inflation, to modest 2027 drilling-and-completion inflation plus steel and diesel pressure. Fourth-quarter guidance points to cash operating costs of $11.05 per Boe at the midpoint, well above the third-quarter level, and to production of 1,408.8 MBoe/d after the asset sale.
The forward catalysts are mostly gas-weighted and long-dated:
- **LNG exposure:** A 10-year, JKM-linked supply agreement with Engie for 140,000 MMBtu/d lifts EOG's premium-priced LNG feedgas exposure above 1 Bcf/d by 2030.
- **Gas processing:** The Janus plant expansion doubles capacity to 600 MMcf/d at roughly $300 million, with a targeted return above 30%. It also adds about $200 million of 2027 capex outside the three-year scenario.
- **International:** UAE wells averaging about 700 bopd each have management talking about a path to commerciality.
- **Exploration and new demand:** Alaska, the Pearsall and discussions with data-center and power customers add optionality.
Bears have legitimate ammunition as well. Bahrain operations remain intermittent amid Middle East conflict. Delaware processing capacity is tightening. CFO Ann Janssen is retiring, with Jeff Hibbert taking over January 1.
Capital returns are robust but deserve scrutiny. The 8% dividend increase to $1.10 quarterly ($4.40 annualized) signals confidence. Net debt fell to about $2.2 billion, and cash climbed to $5.7 billion. Buybacks, however, slowed to $1.0 billion from $1.3 billion, at an average price of $143. That leaves roughly $1.5 to $1.6 billion to repurchase in the fourth quarter to meet the minimum 70% return commitment. The commitment itself has narrowed from the 90% to 100% framing used in late 2025.
The market has not rewarded the year's operating momentum. Shares at $144.89 are up just 1.0% from the $143.50 open following the August report, essentially where EOG was buying back stock. The stock sits about 5.1% above its 200-day moving average, a constructive but unremarkable position. Investor sentiment remained negative and weakened modestly, slipping from -0.17 to -0.26. That suggests investors are focused more on the sequential step-down, cost inflation and commodity risk than on the beat itself.
The bottom line is that EOG executed nearly flawlessly on volumes, costs and capital, and it backed that execution with a dividend increase and a credible gas-marketing growth story. Still, the quarter marks a cooling from the second-quarter peak, and cost pressures are building into 2027. With the stock flat since the last report and sentiment souring, investors appear to be treating EOG as a well-run commodity proxy rather than a re-rating candidate. The fourth-quarter buyback pace and the 2027 cost guide are the next tests.
Read our earnings preview for EOG Resources, Inc.: https://www.earningswhispers.com/article/EOG/22280
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-16 |
Oil Stocks To Buy: EOG Resources Attempts A New Breakout, But Beware This Risk
EOG
Investor's Business Daily
|
| Oct-14 | |
| Oct-13 | |
| Oct-12 | |
| Oct-08 | |
| Oct-07 | |
| Sep-24 | |
| Sep-23 | |
| Sep-22 | |
| Sep-19 |
