HASI's Raised Earnings Target Meets A Skeptical Market As SunZia Funding Hits The Books
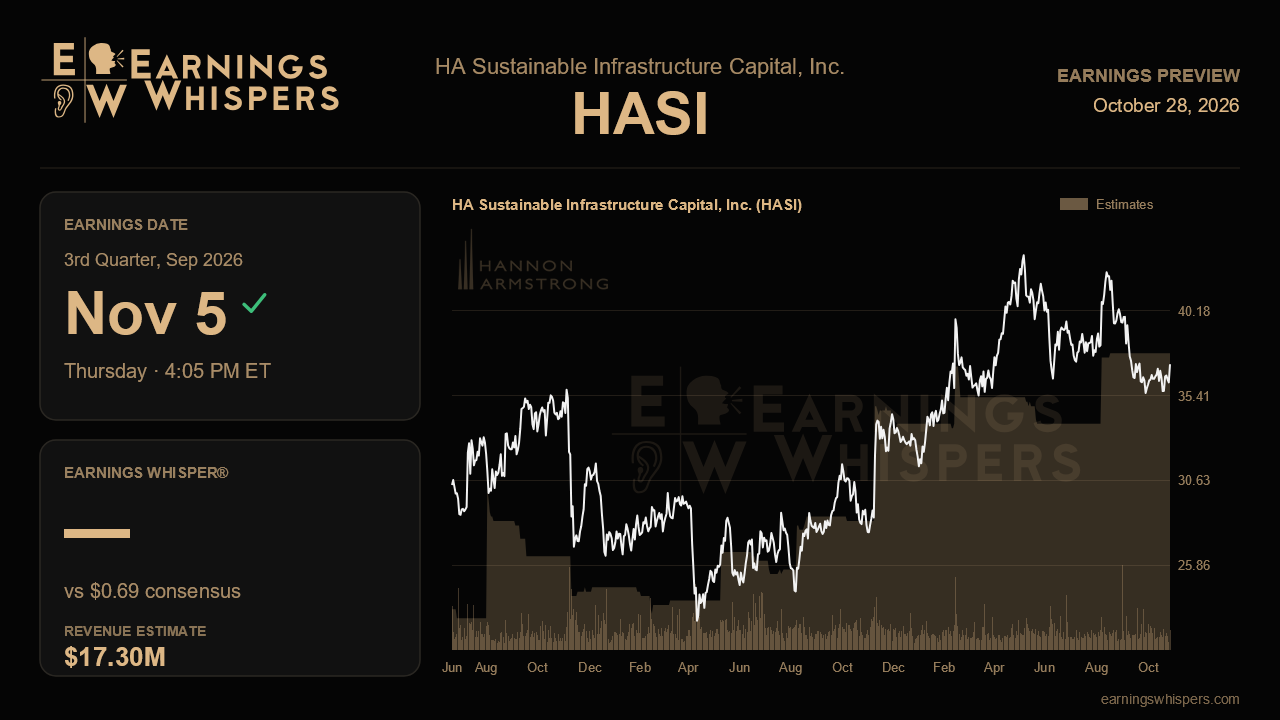
HA Sustainable Infrastructure Capital heads into its third-quarter report with an odd disconnect. Last quarter management delivered its first guidance increase in years, record profitability and a self-funding story that required no new stock sales. The market's response since then has been a shrug that turned into a slide. That gap between an improving operating narrative and a fading share price is what makes the November 5 release, due after the close, worth close attention.
The Street is looking for earnings of $0.69 per share, a touch below the $0.71 posted last quarter and the $0.76 reported a year ago. On the surface that reads like a modest step backward, although HASI's results are quoted on more than one basis and the adjusted figure management highlighted last quarter was $0.75, up 25% from a year earlier. The revenue consensus of $17.3 million, implying an 83% year-over-year decline from $103.1 million, looks more like a definitional mismatch than a collapse in the business, so the headline revenue line deserves skepticism. For a specialty lender and investor like HASI, recurring net investment income is the number that tells the real story, and it grew 27% in the first half of the year.
Management lifted its adjusted EPS target to $3.55 to $3.65 from $3.50 to $3.60, describing it on the call as a 2028 objective, and reaffirmed a return on equity goal above 17%. The full-year consensus of $2.99 for 2026 implies a quarterly run rate near $0.75, which fits the trajectory toward that longer-range target as long as growth continues compounding. The issue this quarter is not whether HASI hits an annual number but whether the building blocks behind the raise keep stacking up.
Several of those blocks should show up in this report. The $1.2 billion SunZia investment was fully funded in July, which should swell the portfolio from the $8.2 billion reported at midyear and begin feeding recurring income. Managed assets reached $17.6 billion last quarter, up 20%, and a further climb would confirm that origination remains robust. New investments closed in the first half carried yields above 11%, up from the 10.5% pace cited earlier, and evidence that those returns are holding would support the claim that wider spreads are outrunning higher funding costs. Adjusted ROE has topped 15% for two straight quarters; a third would make that level look structural rather than lucky. The first water infrastructure deal, a contracted wastewater plant, also closed during the quarter, and any color on follow-on opportunities or progress in sustainable agriculture would show whether diversification is real or ceremonial.
The risks are narrow but worth tracking. One renewable natural gas project slipped into a weaker credit category after construction problems; HASI took control and expects full recovery, so any additional deterioration or credit loss would undercut that confidence. The CCH1 co-investment vehicle nears capacity in early 2027, making a concrete update on CCH2 important for funding flexibility. Continued avoidance of at-the-market equity issuance would reinforce the self-funding thesis, while gain-on-sale income, expected roughly flat, could add noise to the quarter.
Investor mood has cooled sharply. Bullish sentiment fell to 4.8% from 36.3% heading into the last report, and the shares are down 6.6% since then against a flat S&P 500. At $37.17, the stock sits below its 200-day moving average and closer to the $35.37 low of its post-earnings range than the $43.05 high. That lowered bar cuts both ways. The central question is whether SunZia and higher-yielding deployments translate into visibly stronger recurring income and sustained mid-teens ROE. If they do, the market's doubts may look misplaced; if credit issues or funding questions creep in, the recent selling will look prescient.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Oct-28 | |
| Oct-27 | |
| Oct-15 | |
| Oct-02 | |
| Sep-11 | |
| Sep-10 | |
| Sep-04 | |
| Aug-31 | |
| Aug-25 | |
| Aug-18 | |
| Aug-13 | |
| Aug-06 | |
| Jul-20 | |
| Jun-16 |
