HASI Beats On Adjusted EPS, But A One-Time Fair Value Gain Carried The Quarter While Underlying Growth Cooled
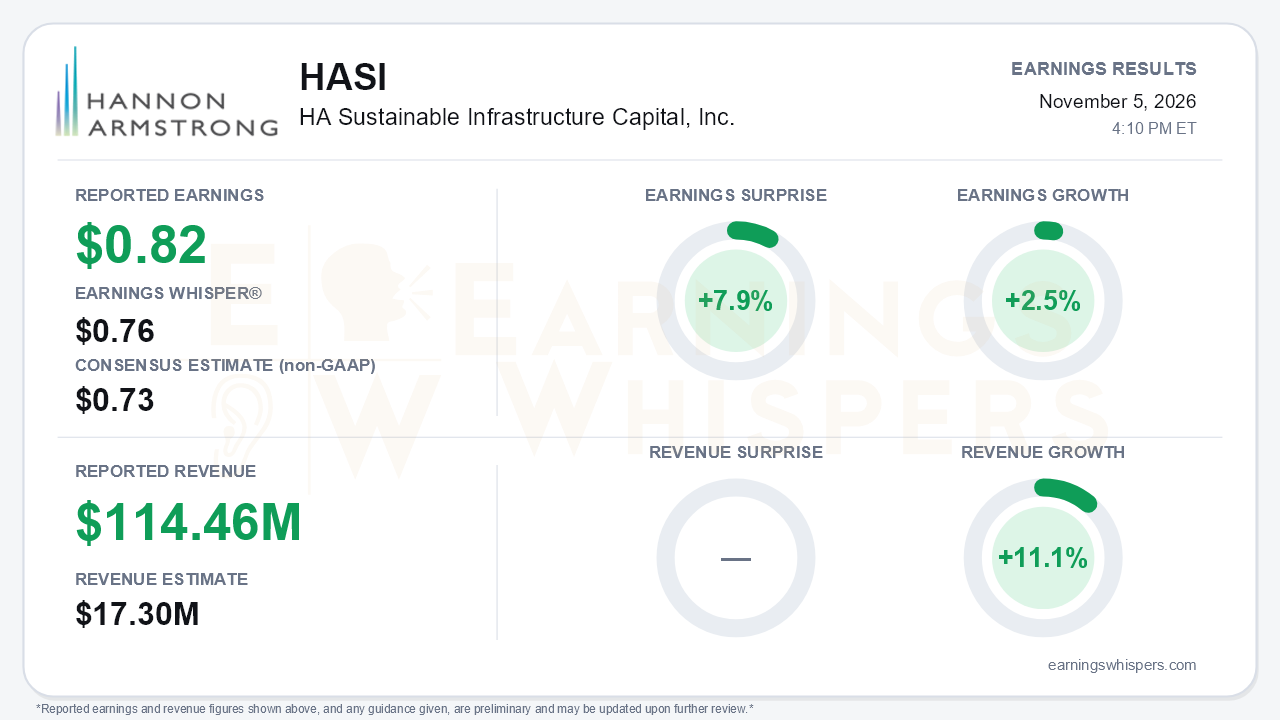
HA Sustainable Infrastructure Capital (NYSE: HASI) reported third-quarter adjusted EPS of $0.82, ahead of the $0.73 consensus and the $0.76 Earnings Whisper number, for a 7.9% surprise. Revenue of $114.46 million rose 11.1% year over year and cleared the $17.3 million consensus. The headline growth rate tells a different story. Adjusted EPS rose only 2.5% from $0.80 a year ago, a sharp slowdown from the 15% year-to-date pace. That is the central tension. Origination volume, managed assets and funding access all moved in the right direction, but the quarter's earnings beat rests heavily on a non-recurring mark.
The quality of the beat deserves scrutiny. Adjusted Recurring Net Investment Income rose 15% to $121 million, but it included a $35 million unrealized gain on HASI's investment in the SunStrong solar servicing platform, which is carried at fair value. That gain was partly offset by a $21 million economic loss on a consolidated renewable natural gas project. The net benefit of roughly $14 million, spread over about 132 million adjusted shares, is worth around a dime per share, which is most of the margin over consensus. Elsewhere, gain on sale of assets fell $17 million year over year to $7.5 million, and interest expense rose $25 million to $96 million. The weighted cost of debt climbed to 6.2% from 5.9% as junior subordinated notes grew. A $9 million jump in origination fee and other income helped fill the gap. GAAP EPS of $1.04, up from $0.61, reflects HLBV equity-method accounting and says little about run-rate economics. More meaningful is that cash collected from equity-method investments reached $306 million, versus $93 million a year earlier.
The call preserved a credible growth story. Q3 closings exceeded $1 billion, anchored by a 2.7 GW, 10-project common-equity investment with Invenergy. Year-to-date balance sheet and CCH1 closings reached $2.5 billion, and management now expects the high end of its $2-3 billion 2026 range, an upgrade from the second quarter's "well on track." New asset yields stayed above 11%, and portfolio yield rose 70 basis points year to date. Managed assets climbed to $19.0 billion from $17.6 billion last quarter, while CCH1 assets reached roughly $4 billion. Funding costs also improved:
- CCH1's $400 million 20-year notes priced at 195 basis points.
- A new secured term loan came in 100 basis points tighter.
- Commercial paper costs fell.
- HASI made no ATM issuance.
Management framed demand as unaffected by the election and pointed to intact data center load growth. HASI also added carbon removal and water exposure through its TerraDot and wastewater investments.
Bears have legitimate ammunition, though. The consolidated RNG asset moved from Category 2 to Category 3, about 1% of the portfolio. Last quarter, management cited a "reasonable likelihood" of full recovery; it now flags recovery of invested capital as at risk. The 2026 gain-on-sale outlook was trimmed to $50-60 million, below the roughly $65 million implied in Q2. Growth is also moderating on a year-to-date basis:
- Adjusted Recurring Net Investment Income growth slowed to 23%, from 27% at the half.
- Adjusted earnings growth slowed to 21%, from 31%.
Liquidity slipped to $2.0 billion from $2.2 billion, and the floating-rate share of debt rose just as the 10-year Treasury pushed above 5%. Management says it is hedging that exposure. Renewable-policy uncertainty adds another variable. The reaffirmed 2028 targets ($3.55-$3.65 in adjusted EPS, adjusted ROE above 17%, and a payout ratio below 50%) were held, not raised.
Investor expectations had already cooled heading into the print. Earnings Whispers sentiment fell from 0.36 at the prior report to 0.05, a meaningful retreat to roughly neutral. Shares closed at $40.38 ahead of the release, up just 1.5% from the $39.78 open after the August report. The stock traded 5.7% above its 200-day moving average and sat in the upper-middle of its inter-earnings range, 6.2% below the August 14 high of $43.05 and 14.2% above the September 29 low of $35.37. The trend readings are mixed, with momentum positive while price and AVWAP trends remain negative. That suggests a stock that recovered from its autumn low but has not reclaimed its post-August highs.
The bottom line is that HASI's franchise is expanding: volumes are at the top of guidance, yields are above 11%, and co-investment fees and funding spreads are improving. However, the third-quarter beat was largely manufactured by a fair value mark, and the underlying growth rates, gain-on-sale outlook and one credit exposure all moved the wrong way. With sentiment already deflated, the setup hinges less on this headline surprise than on whether recurring income can carry the 2028 targets without help from one-time gains.
Read our earnings preview for HA Sustainable Infrastructure Capital, Inc.: https://www.earningswhispers.com/article/HASI/22301
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-29 | |
| Oct-28 | |
| Oct-27 | |
| Oct-15 | |
| Oct-02 | |
| Sep-11 | |
| Sep-10 | |
| Sep-04 | |
| Aug-31 | |
| Aug-25 | |
| Aug-18 | |
| Aug-13 |
