Grindr Faces Its Promised Slowdown As Shares Sit Near Post-Earnings Lows
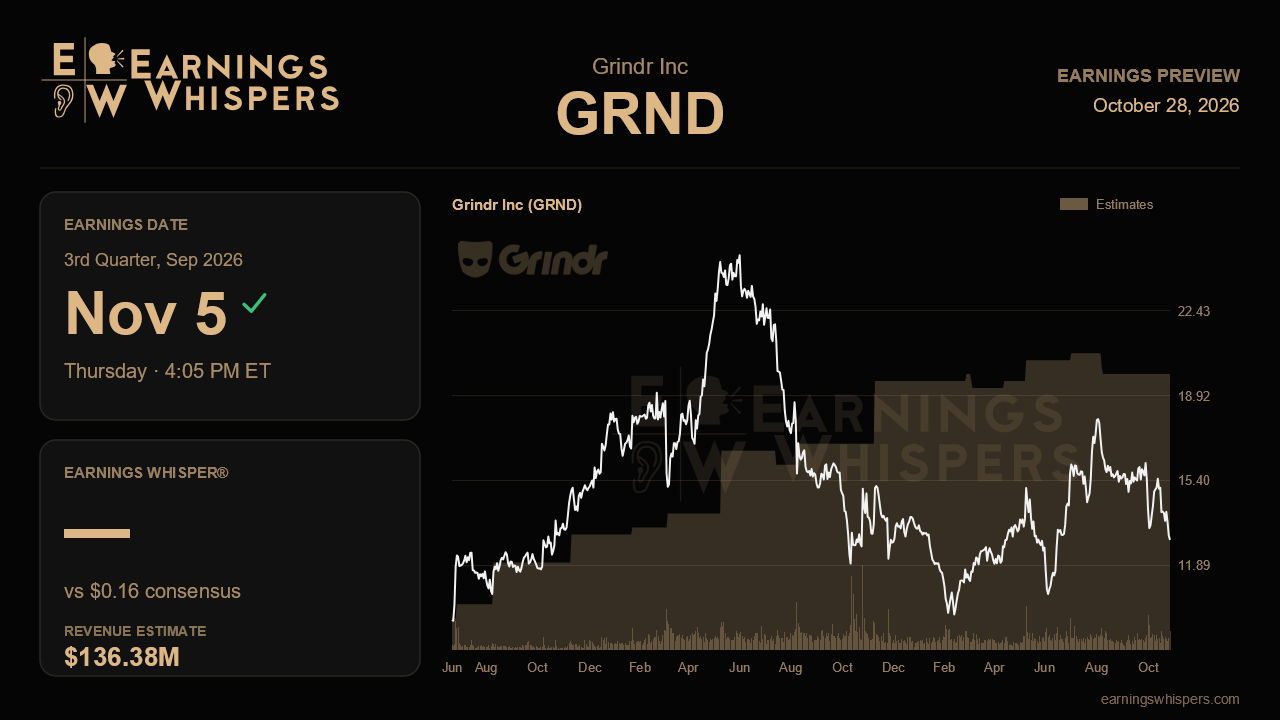
Grindr enters its third-quarter report with an unusual setup: management has already told the market that growth will slow, and the stock has sold off anyway. After three straight increases to its full-year outlook, the company framed the second half of 2026 as a period of deliberate deceleration as last year's subscription price increases anniversary and comparisons stiffen. The report on November 5, after the close, is the first real test of whether that slowdown is as orderly as management described, or something the market should worry about.
The Street is looking for earnings of $0.16 per share, flat with the year-ago quarter, on revenue of roughly $136.4 million. That revenue figure implies growth of about 17.8%, healthy by most standards but a sharp step down from the 33% pace Grindr posted in the second quarter. It also sits slightly below the $138.1 million the company booked last quarter, which tells you analysts are taking management's caution at face value. Full-year consensus of about $539.3 million lines up almost exactly with the company's guidance of approximately $540 million, so the Street is neither stretching above the outlook nor hedging below it. Management also lifted its adjusted EBITDA target to roughly $232 million, a figure that will frame how the quarter's profitability is judged.
The most important nuance from the last call is where the guidance raise came from. Nearly all of it reflected first-half outperformance, chiefly because subscribers tolerated the late-2025 price increases better than A/B testing had predicted, with churn and conversion both beating plan. Management did not raise its view of the back half. That means a result merely in line with consensus would validate the story, while a meaningful revenue beat would suggest pricing durability is outlasting the anniversary effect. Conversely, a shortfall would raise the uncomfortable question of whether the strong retention was a temporary cushion. Advertising deserves attention too. It surged 44% last quarter to $25 million, and management expects it to drift back toward its historical share of revenue next year, so any early sign of that normalization arriving ahead of schedule would matter.
Margins are the other pillar. Grindr credited AI-driven engineering productivity, now pegged at roughly two and a half times prior output, with avoiding about 200 hires and around $60 million in annual cost. Yet operating expenses jumped to $71 million in the second quarter, partly on one-time marketing tied to the Madonna album launch and Times Square event. Flat EPS against high-teens revenue growth hints that costs remain elevated, so evidence that spending eased after that promotional burst would reinforce the efficiency narrative. Management also reaffirmed a long-term margin target of 39% to 42%, signaling that current levels near 43% are not the new baseline. Finally, the Edge AI premium tier was slated for a fall launch and positioned as the main 2027 growth engine, with early testing showing even non-payers converting. Any color on launch timing and early uptake could shape the 2027 conversation more than the quarter itself.
The market has not been generous. Shares are down about 18% since the last report while the S&P 500 was essentially flat, and at $12.94 the stock is pinned near its post-earnings low of $12.91 and below its 200-day moving average. Sentiment has softened its bearish lean compared with the prior quarter but remains slightly negative, which suggests skepticism rather than capitulation.
That combination of improving operations and a falling stock lowers the bar in one sense, but the central question is narrow: does the second-half deceleration look like a managed handoff from pricing gains to Edge, or the start of a longer fade? Revenue holding near guidance, contained expenses, and a credible Edge launch would keep the narrative intact.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-22 | |
| Oct-13 | |
| Oct-01 | |
| Oct-01 | |
| Oct-01 | |
| Sep-30 | |
| Sep-21 | |
| Sep-17 | |
| Sep-04 | |
| Aug-30 | |
| Jul-27 | |
| Jul-23 | |
| Jul-01 | |
| Jul-01 |
