Grindr's $33 Million Legal Charge Buries A Raised Outlook, But Slowing Growth And A Thinner 2027 Margin Complicate The Story
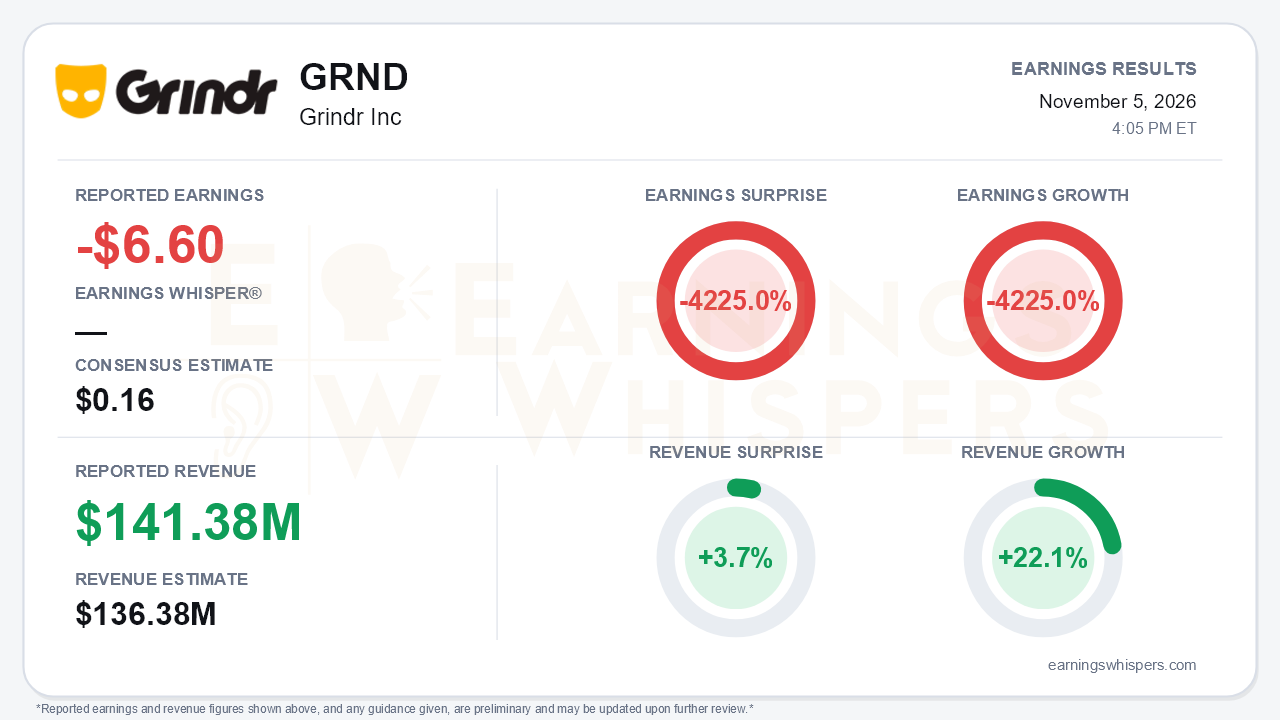
Grindr (NYSE: GRND) posted a quarter where the headline miss and the operating picture point in opposite directions. On Earnings Whispers' normalized basis, the company reported a loss of $6.60 per share against a $0.16 consensus, a 4225.0% shortfall that also equals a 4225.0% year-over-year decline. The release shows a GAAP net loss of $6.6 million, compared with net income of $30.8 million a year earlier. The per-share and dollar figures are numerically identical, so investors may want to reconcile the per-share loss against the share count in the quarterly filing. Either way, the swing to a loss came almost entirely from $32.3 million in litigation-related costs, mainly a one-time UK data-practices settlement. Revenue of $141.38 million beat consensus by 3.7% and grew 22.1%. Management raised full-year guidance for a third straight quarter and issued a 2027 outlook early. The central tension is that the forward numbers keep rising while the growth rate and margin structure are both moving down.
The quality of the quarter deserves scrutiny beyond the settlement. Adjusted EBITDA rose to $61.7 million from $54.8 million. However, the adjusted EBITDA margin fell to 43.7% from 47.4% a year ago, though it improved from roughly 42% in the second quarter.
The company's own measures that exclude litigation and transaction costs are less flattering:
- Operating margin excluding those items dropped to 28.7% from 39.8%.
- Net income excluding those items fell to $21.0 million from $31.6 million.
- Operating expenses excluding cost of revenue and those charges jumped to $66.2 million from $40.8 million.
- Stock-based compensation more than tripled to $19.3 million.
- Net interest expense climbed to $6.8 million, consistent with a balance sheet that has funded about $180 million of buybacks (13 million shares) year to date.
The settlement is non-recurring. The heavier cost base is not.
The deceleration is the part bears will focus on. Revenue growth slowed to 22% from 33% in the second quarter, and advertising growth fell to 23% from 44%. The subscription engine still looks healthy: paying users rose 11% to 1.4 million and ARPU increased 10% to $27.15. Management also cited roughly 70 minutes of daily engagement and monthly active users up 13% since 2024. Guidance has climbed steadily all year:
- Full-year revenue guidance moved from above $528 million to at least $560 million.
- Full-year adjusted EBITDA guidance moved from above $217 million to at least $236 million.
Management says that puts Grindr within its Investor Day targets nearly a year early.
The 2027 outlook calls for revenue of at least $705 million, roughly 26% growth, and adjusted EBITDA of at least $275 million. Much of that growth relies on two new bets.
- **Edge.** The AI-native premium tier launches globally November 17 at $120 per month. It drew about 400,000 early-access registrations in 72 hours, against roughly 100,000 expected over seven days. Management frames it as a $100 to $150 million long-term opportunity.
- **Freddie.** The newly closed PurposeMed acquisition brings in Freddie's PrEP telehealth business. Management expects about 12,000 U.S. patients by year-end and targets 50,000 over the medium term, which it equates to about $240 million of revenue at 40%-plus margins.
The costs of these bets are visible now. The implied 2027 adjusted EBITDA margin is about 39%, down from roughly 42% this year, because of the pharmacy and clinical buildout. Advertising is expected to moderate, including about $10 million of telehealth ad revenue lost as Freddie is internalized. This is also Grindr's first acquisition, in an operationally different and heavily regulated business, and management is deliberately slowing patient growth in 2027. The 2027 guide was set before current core-app tests have read out.
The market came into the report skeptical. Investor sentiment edged lower, from -0.10 to -0.13, a modest move that kept expectations slightly negative rather than signaling capitulation. As of the pre-report snapshot, shares sat at $14.01:
- down 11.3% since the open after the August report;
- 18.7% below the inter-earnings high of $17.23 set August 10;
- just 2.7% above the 200-day moving average;
- 11.6% above the October 29 low.
The trend readings are split. Sequential growth and momentum are positive, while price and AVWAP trends remain negative, which fits a stock whose fundamentals keep improving on paper but which has lost ground since August.
The bottom line is that Grindr's GAAP miss is mostly a legal-accounting event, while revenue, subscriber monetization, and guidance all moved the right way. The harder question is whether Edge and Freddie can offset decelerating core and advertising growth, along with a cost structure that is pushing 2027 margins lower. Bulls have a raised outlook and a strong early Edge signal. Bears have legitimate ammunition in the slowdown, rising expenses, and integration risk.
Read our earnings preview for Grindr Inc: https://www.earningswhispers.com/article/GRND/22297
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-02 | |
| Oct-28 | |
| Oct-22 | |
| Oct-13 | |
| Oct-01 | |
| Oct-01 | |
| Oct-01 | |
| Sep-30 | |
| Sep-21 | |
| Sep-17 | |
| Sep-04 | |
| Aug-30 | |
| Jul-27 |
