Globus Medical's Margin Machine Faces A Revenue Test As Q3 Bar Sits Below Guidance
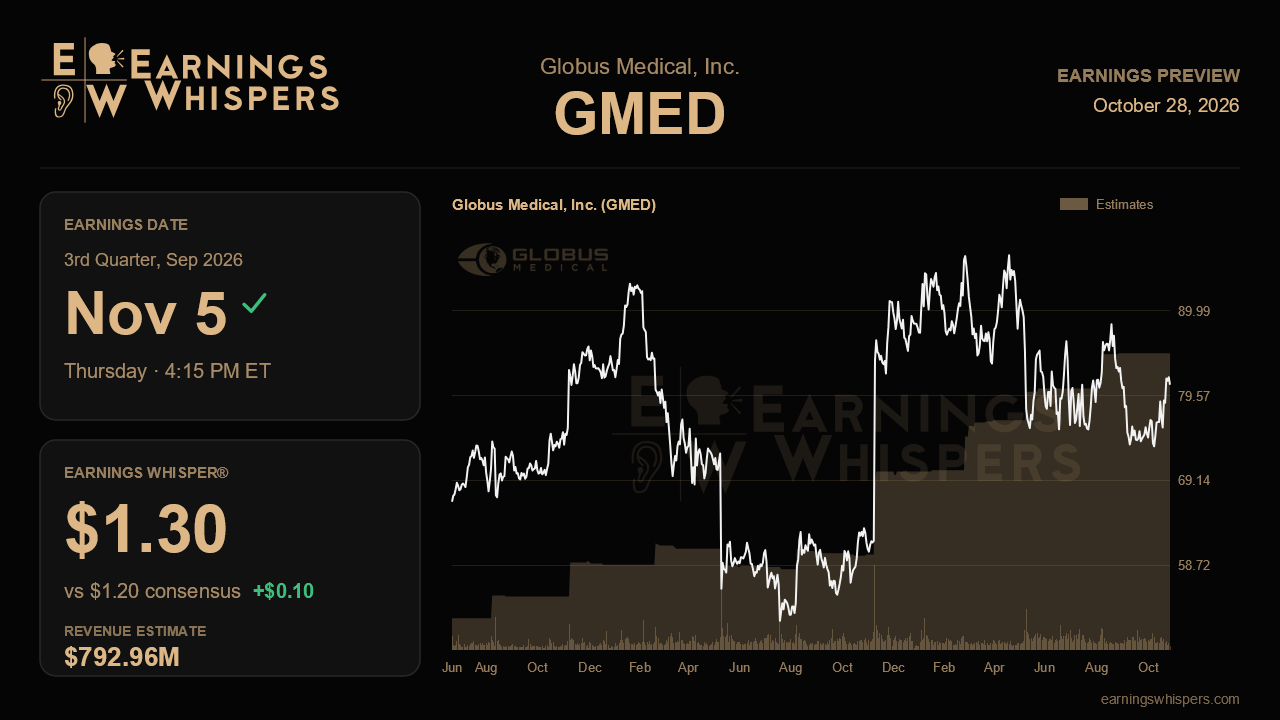
Globus Medical has spent the past year turning a modest top line into a steadily rising earnings outlook, lifting its full-year profit forecast four straight times while leaving its revenue target untouched. That split is the crux of the third-quarter report due after the close on November 5. The company has shown it can squeeze more profit from every dollar of sales. What it has not yet shown is that its weaker revenue streams, robotics and the Nevro neuromodulation business, have stopped leaking.
The Street's numbers look strikingly cautious. Consensus calls for earnings of $1.20 per share on revenue of $793.0 million, which would mean growth of just 1.7% and 3.1% from a year ago. That EPS figure is also well below the $1.34 Globus earned last quarter on nearly identical revenue of $789.6 million. Management now guides full-year earnings to $4.95 to $5.05 per share, yet the full-year consensus sits around $4.74, below the bottom of that range. Some of that gap likely reflects estimates that have not caught up, but it still suggests analysts are not fully crediting the margin story. The Earnings Whisper of $1.30 is a meaningful 10 cents above consensus, a sign that the informal bar is set closer to last quarter's run rate than published forecasts imply. On revenue, the Street's $3.20 billion annual estimate sits squarely at the midpoint of the $3.18 billion to $3.22 billion guide.
Margins are where the bull case lives. Adjusted gross margin reached 69.4% last quarter, a seventh consecutive quarter of expansion, and management said it expects to touch the low 70s by year end. Adjusted EBITDA margin jumped to 35.4% from 32.3% in the first quarter, helped by Nevro's standalone margin nearly doubling. Another step up in gross margin would validate that trajectory. The complication is spending: management flagged a second-half ramp in research and development to 5% to 6% of sales, with more than 60 projects underway and competitive sales hires running at double the first-quarter pace. If gross margin keeps climbing while operating expenses rise, the earnings line can hold up. If gross margin stalls, the R&D ramp will show up quickly in EPS, which may be exactly what the low consensus is bracing for.
The revenue mix deserves equal scrutiny. U.S. Spine growth slowed to 7.3% last quarter from roughly 10% in the prior three, and management warned that comparisons get tougher in the back half. Holding growth anywhere near that level would ease concerns that the core franchise is losing share. Enabling Technologies revenue fell 26% to $26.1 million as the company pushes customers toward leases and rentals instead of upfront purchases, a deliberate shift that depresses near-term sales. Nevro, at about $81 million, remains well below its fourth-quarter 2025 level, with management pointing to a trial-volume recovery only by late in the year. Early signs of stabilization there would matter more than a large beat elsewhere. Continued strength in Trauma, up 31%, and International Spine, up 14%, plus initial traction for the newly launched Script patient-specific implants, would bolster the argument that growth is broadening.
The market has not been patient. Shares have fallen 8.2% since the last report while the S&P 500 was roughly flat, and at $80.90 the stock trades below its 200-day moving average of $83.71, sitting in the lower half of its post-earnings range of $72.54 to $88.89. Sentiment has also cooled, moving from barely bearish to modestly more bearish.
That sets up a report in which another strong margin print may not be enough by itself. The narrative stays intact if Globus delivers earnings near the whisper, reaffirms or lifts its profit guide, and offers credible evidence that Enabling Technologies and Nevro are bottoming. A fifth EPS raise paired with yet another unchanged revenue forecast would keep the debate about earnings quality alive.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-14 | |
| Oct-12 | |
| Oct-06 | |
| Oct-02 | |
| Sep-29 | |
| Sep-24 | |
| Sep-21 | |
| Sep-18 | |
| Sep-17 | |
| Sep-14 | |
| Sep-09 | |
| Sep-04 | |
| Sep-03 | |
| Sep-02 |
