Globus Medical Protects Its EPS Outlook With Margins And Spending Restraint, But The Revenue Story Breaks As Spine Slows And Nevro Slips
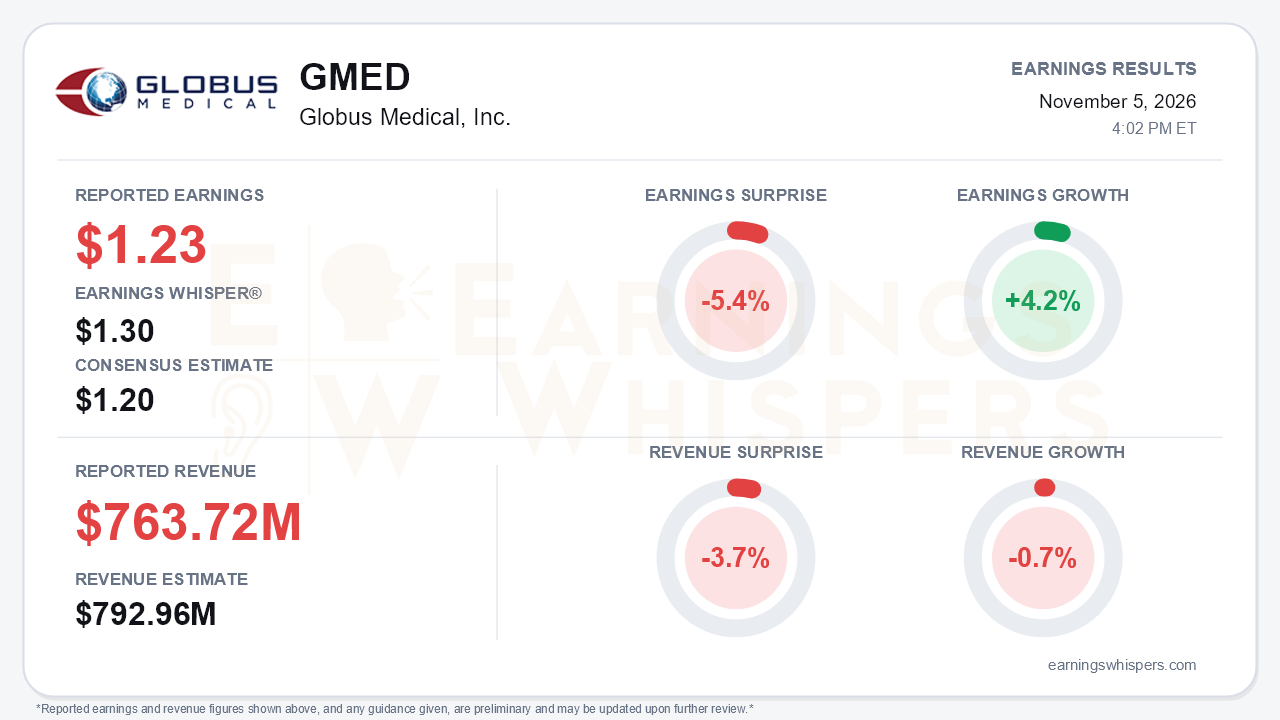
Globus Medical delivered a quarter in which the bottom line held up and the top line cracked. Non-GAAP EPS of $1.23 edged past the $1.20 consensus but fell 5.4% short of the $1.30 Earnings Whisper number. Earnings grew only 4.2% year over year, a sharp deceleration from the much faster growth earlier in 2026, when the Nevro acquisition was still inflating comparisons. Revenue of $763.7 million missed consensus by 3.7% and slipped 0.7% from a year ago. The more consequential news was the first revenue guidance cut of the year. Full-year 2026 sales are now expected at $3.09 billion, down from $3.18 billion to $3.22 billion, cutting implied growth to 5.1% from roughly 8% to 10%. Non-GAAP EPS guidance of $4.95 to $5.05 was reaffirmed. That split is the central tension: profitability is intact while growth is visibly stalling.
The quality of the earnings beat deserves scrutiny. Profitability is genuinely strong. Adjusted gross margin reached 69.5%, the eighth straight quarter of sequential expansion. Adjusted EBITDA margin rose to 34.3% from 32.8%, and free cash flow hit a record $225 million. But part of the earnings resilience came from spending less:
- R&D fell to $34.5 million from $38.1 million.
- SG&A dropped about $25 million.
- Management lowered its full-year R&D outlook to 4.5% to 5% of sales from 5% to 6%.
- Net interest income climbed to $8.4 million from $1.5 million.
GAAP EPS rose 18.2% to $1.04, but that comparison is flattered by a much smaller litigation provision than a year ago. The reaffirmed EPS range implies fourth-quarter non-GAAP EPS of roughly $1.26 to $1.36, above Q3's level, even as revenue is guided to a mid-single-digit decline. Delivering that will depend heavily on continued cost discipline rather than sales momentum.
Beneath the headline, the deceleration is broad:
- **U.S. Spine:** Growth slowed to about 1.8%, from 7.3% in Q2 and 9.6% in Q1. Management cited delayed launches, production issues and weaker recruiting of competitive sales reps. That is an awkward reversal from Q2 commentary about doubling hires. Management framed the quarter as a tough comparison and pointed to mid-single-digit two-year growth.
- **Nevro:** Sales fell 25.7% year over year and 9% sequentially to $73.7 million. The trial-volume recovery once targeted for late Q4 has been pushed into 2027.
- **International:** Sales fell 5.7%, with the business excluding Nevro flat to down, Japan soft and integration disruption cited.
- **Base business:** Sales excluding Nevro grew just 3.0%.
The tone on the call shifted noticeably, from talk of a record-breaking year to acknowledgment of 'bumps and air pockets.'
There are genuine bright spots. Enabling Technologies revenue rebounded 24% to $34.9 million after a 26% decline in Q2, and robot and navigation placements rose 73%. The FDA closed the eGPS warning letter, and trauma grew 19%. The pipeline is active:
- Script patient-specific implants are now in cases.
- The X-LIF prone solution and Maxxis Air retractor arrive later in Q4.
- The EIQ pedicle fixation suite is in final stages.
- Nevro's HFX Elite is slated for the first half of 2027.
- The Higgs Boson and Synaptive deals add surgical intelligence and an entry into cranial neurosurgery.
Bears still have legitimate ammunition. Revenue from Script and X-LIF prone has slipped from the second half of 2026 into 2027. Enabling Technologies faces a tough Q4 comparison, and a shift toward leases reduces upfront revenue. Management also flagged higher R&D in 2027 that will absorb some gross-margin gains. Inventories have climbed to $824 million from $759 million at year-end while sales have flattened. Competitors have also described spine-market softness, though management declined to attribute its slowdown to the market.
The market setup is more complicated than the narrow consensus beat implies. Shares closed at $87.10 ahead of the report, essentially flat (-1.2%) from the open after the August release. They had rallied about 20% from the October 8 low of $72.54 to sit just 2% below the inter-earnings high of $88.89 and 4.5% above the 200-day moving average. In other words, the stock entered the print near the top of its range, leaving little cushion for a revenue cut. Investor sentiment had already drifted from roughly neutral to modestly negative, at -0.07 from -0.01, a small move but in the wrong direction. Earnings Whispers trend readings were mostly positive, though AVWAP remained negative. The capital return story offers some cover: the company holds $871 million in cash and securities, has repurchased $279 million of stock year to date and added $500 million to its buyback authorization.
The bottom line is that Globus showed it can defend earnings and cash flow through margin expansion and spending restraint, but the revenue narrative has clearly weakened. The quarter brought slowing U.S. Spine growth, a Nevro recovery pushed into 2027 and a guidance cut that implies a declining fourth quarter. Until new launches convert into measurable spine growth and Nevro stabilizes, the reaffirmed EPS target will look more like the product of cost control than of a healthy growth engine.
Read our earnings preview for Globus Medical, Inc.: https://www.earningswhispers.com/article/GMED/22294
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-03 | |
| Oct-28 | |
| Oct-14 | |
| Oct-12 | |
| Oct-06 | |
| Oct-02 | |
| Sep-29 | |
| Sep-24 | |
| Sep-21 | |
| Sep-18 | |
| Sep-17 | |
| Sep-14 |
