Helios Faces A Prove-It Quarter As Stock Slumps Despite Raised Guidance And Data Center Hopes
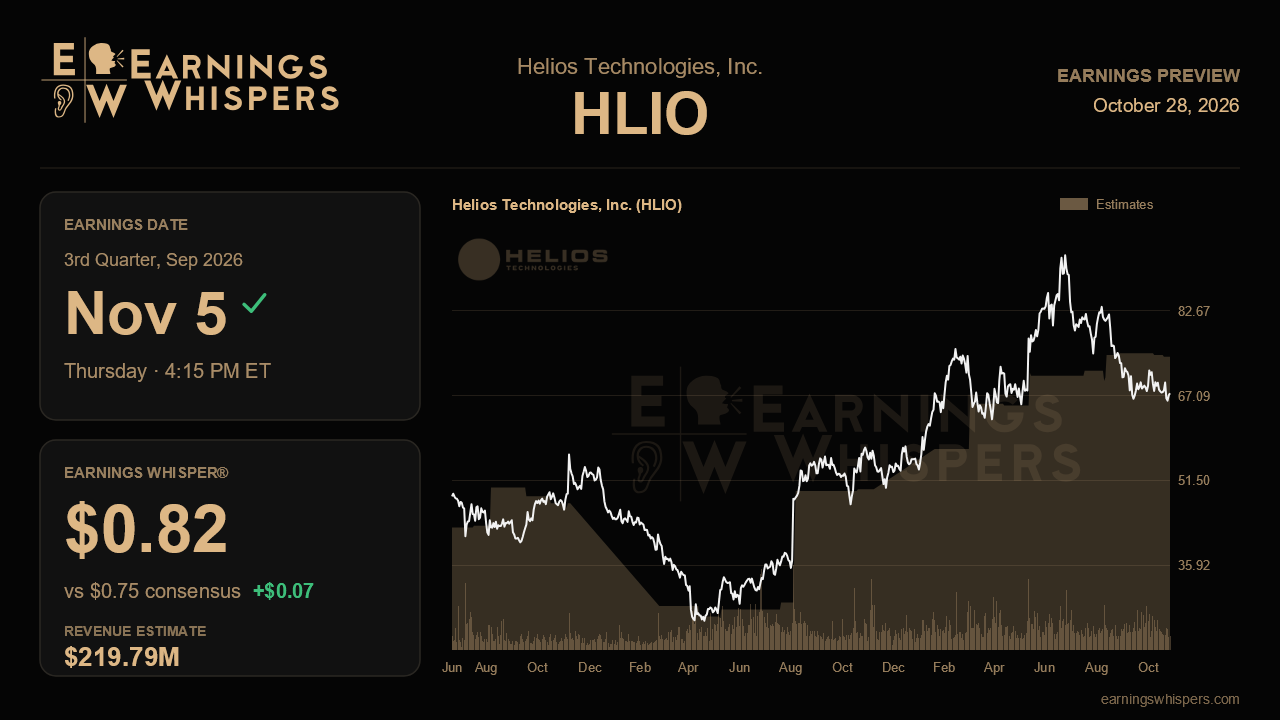
Helios Technologies enters its third-quarter report with a striking disconnect. Three months ago management declared its turnaround finished, raised full-year guidance for the second straight quarter and described the business as gaining altitude faster than expected. Since then the stock has fallen 17.7%, trailing the S&P 500 by about 17 percentage points. When the company reports after the close on November 5, the question is less whether Helios can hit a modest quarterly number and more whether it can show that the growth story management outlined still holds as comparisons get harder.
The quarterly bar itself is not demanding. Consensus calls for EPS of $0.75, up about 4% from $0.72 a year ago, on revenue of $219.8 million, essentially flat year over year. Management guided to EPS of $0.70 to $0.77 on sales of $215 million to $222 million, so the Street sits in the upper half of both ranges without exceeding them. The Earnings Whisper of $0.82 is more telling. It sits above the top of the company's range, which suggests the more engaged investors expect Helios to keep its habit of beating. Last quarter it topped its own EPS guidance by a nickel. Matching the formal consensus may therefore feel like a letdown to that crowd.
The full-year outlook carries more weight than the quarter. Helios lifted its 2026 sales guidance from an initial $820 million to $860 million, then to $840 million to $870 million, and now to $880 million to $900 million. EPS guidance rose to $3.05 to $3.25, and the adjusted EBITDA margin floor moved up to 20.2%. After two raises in a row, simply reaffirming may disappoint, and any trim would undercut management's case. The best support would be evidence that order intake kept growing at a double-digit pace for a fifth straight quarter. Management said July set records for both sales and orders, so August and September need to show that the record was not a one-month spike.
Margins are the main swing factor. Gross margin expanded for a fourth straight quarter to 34.6%, and adjusted EBITDA margin has held above 20% for four quarters. Yet management flagged rising energy and fuel costs along with inflation in circuit boards, memory chips and aluminum, and its own Q3 outlook assumed slightly lower EBITDA margin than a year ago. Footprint consolidation, including the Toledo build-out and the closure of a Canadian facility, should start offsetting those pressures in the second half. Holding margins near 21% would suggest the savings are arriving on schedule. The electronics segment, which rose 19% last quarter, is the place to watch for chip inflation, while soft recreational marine demand remains a weak spot.
Then there is the data center opportunity, which management called the single largest in the company. Last quarter couplings went from a positioning story to samples with roughly a dozen prospective customers, and a first order was described as imminent for the second half. A confirmed order would give the stock a tangible new growth driver. Further delay would not hurt near-term numbers, but it would make the narrative harder to defend.
Sentiment has cooled, slipping to 25.1% bullish from 32.4% before the last report. At $67.53, the stock trades below its 200-day moving average of $73.27 and sits about 4% above its post-earnings low of $64.80, well beneath the prior quarter's $72.56 to $95.05 range. The market is clearly pricing in doubt about second-half durability. That lowers the hurdle for a relief move if Helios delivers, but the central test remains plain. Orders, margins and the full-year outlook need to show that the business is still climbing even as comparisons stiffen and costs rise.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-22 | |
| Oct-21 | |
| Oct-19 | |
| Oct-16 | |
| Oct-05 | |
| Oct-01 | |
| Sep-28 | |
| Sep-09 | |
| Sep-01 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Aug-05 | |
| Jul-28 |
