Helios Beats Consensus But Misses The Whisper As Record Sales Mask A Margin Stall And A Softer Q4
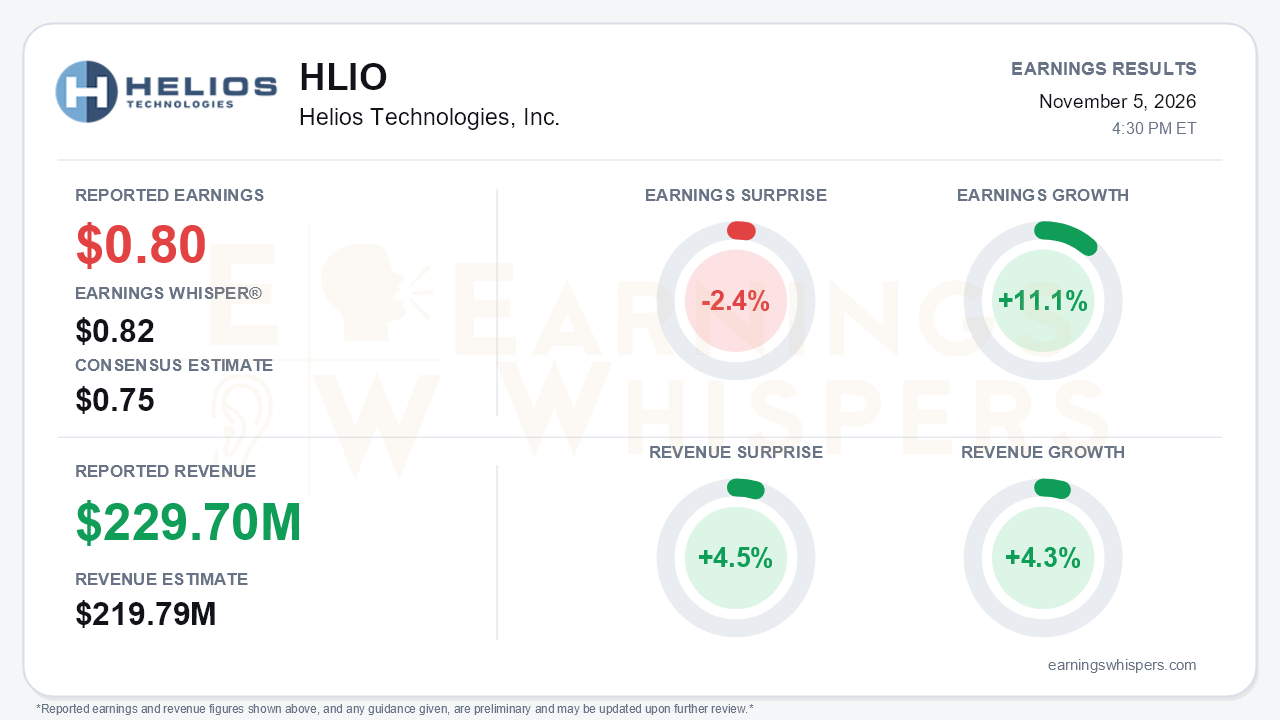
Helios Technologies (NYSE: HLIO) posted a record third quarter on the top line, but the quality of the beat deserves scrutiny. Adjusted EPS of $0.80 topped the $0.75 consensus yet fell short of the $0.82 Earnings Whisper number, a 2.4% miss against the bar that more engaged investors were using. Revenue of $229.7 million beat the $219.79 million consensus by 4.5% and came in $8 million above the high end of management's own $215-222 million guide. Earnings grew 11.1% year over year and revenue grew 4.3%. That is the central tension. Sales keep outrunning expectations, but margins have stopped expanding, part of the upside was borrowed from the fourth quarter, and management is now actively lowering expectations for 2027.
The reported growth rate is clearly decelerating: 17% in Q1, 9% in Q2 and 4% in Q3. Pro forma growth of 13% is the more generous view, because it strips out the divested business that depresses Hydraulics' reported 1% gain. On a pro forma basis, Hydraulics grew 15% and Electronics 9%. Still, the geographic detail shows soft spots. Hydraulics APAC sales fell 18%, and the CFO acknowledged that sales and EPS benefited from customers ordering ahead of announced price increases. The call put that pull-forward at roughly $4-5 million. GAAP EPS of $0.53, up 71%, flatters the comparison. The year-ago quarter carried a $25.9 million goodwill impairment, partly offset by an $18.8 million divestiture gain, so the GAAP jump says more about last year than about this one. On a non-GAAP basis, adjusted operating margin was flat at 16.6%.
Margins are where the story changed most. Adjusted EBITDA margin slipped 20 basis points to 20.3%, compared with gains of 310 basis points in Q1 and 260 in Q2. Gross margin rose only 10 basis points to 33.2%, down sharply from 34.6% in Q2. Management cited material, freight, fuel and European utility inflation as a headwind of more than 100 basis points year over year. Hydraulics gross margin fell 20 basis points. Electronics delivered 10% growth, but its segment operating expenses rose 19%. Management also flagged tightening memory chip and circuit board supply, a shift from earlier in the year, when it called the issue immaterial.
The guidance was mixed. Full-year sales guidance rose for a fourth straight time, to $895-902 million, which implies record annual sales. The bottom line went the other way. The adjusted EBITDA margin range narrowed to 20.2-20.4% from 20.2-21.0%, and adjusted EPS narrowed to $3.08-3.15 from $3.05-3.25, lowering the midpoint despite the higher sales outlook. The Q4 outlook of $205-212 million implies roughly -3% to slightly positive year-over-year growth, with EBITDA margin of just 18.5-19.5%. Management said pricing benefits and Radio Sound synergies will arrive mainly in 2027. It also shifted from the upbeat tone of the prior call to explicit caution, telling investors not to extrapolate double-digit growth and pointing toward 5%-plus organic growth next year.
The call did preserve a credible longer-term growth story. Faster secured its first data center thermal management order after quarter end. More than 30 prospective customers are now sampling, up from about a dozen cited last quarter, and the company has NDAs in place with hyperscalers. Marine grew year over year for the first time in seven quarters. Order intake and backlog rose by double digits, and October was the best month on record. The balance sheet is a real asset. Operating cash flow reached a third-quarter record of $40 million, free cash flow was $32 million, and leverage fell to 1.4x from 2.4x. Management said it is open to larger acquisitions. Bears still have legitimate ammunition: distributor restocking versus end demand, a China inventory build management is monitoring, inventory above $200 million, and Radio Sound integration costs landing in Q4.
Investors were already pricing in much of this caution. Earnings Whispers sentiment remained positive but weakened meaningfully, falling from 0.32 to 0.19. Shares have dropped 26.7% from the $82.01 open after the August report to $60.09, about 18% below the 200-day moving average of $73.41. The market has been discounting the margin and growth-deceleration risks that this report made explicit.
The bottom line is that Helios delivered a revenue beat and a higher sales outlook, but the details point to a business shifting from margin-driven earnings acceleration to a slower, inflation-pressured phase. Missing the whisper, trimming the top of the EPS range and guiding to a flat-to-down fourth quarter undercut the headline record. The data center win and the strong balance sheet give the stock a credible catalyst path. For now, though, the near-term setup hinges on whether 2027 pricing and synergies can restore margin expansion.
Read our earnings preview for Helios Technologies, Inc.: https://www.earningswhispers.com/article/HLIO/22304
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-05 | |
| Nov-05 | |
| Nov-04 | |
| Oct-28 | |
| Oct-22 | |
| Oct-21 | |
| Oct-19 | |
| Oct-16 | |
| Oct-05 | |
| Oct-01 | |
| Sep-28 | |
| Sep-09 | |
| Sep-01 | |
| Aug-11 |
