Kayne Anderson BDC Faces Dividend Coverage Test As Consensus Slips Below 40-Cent Payout
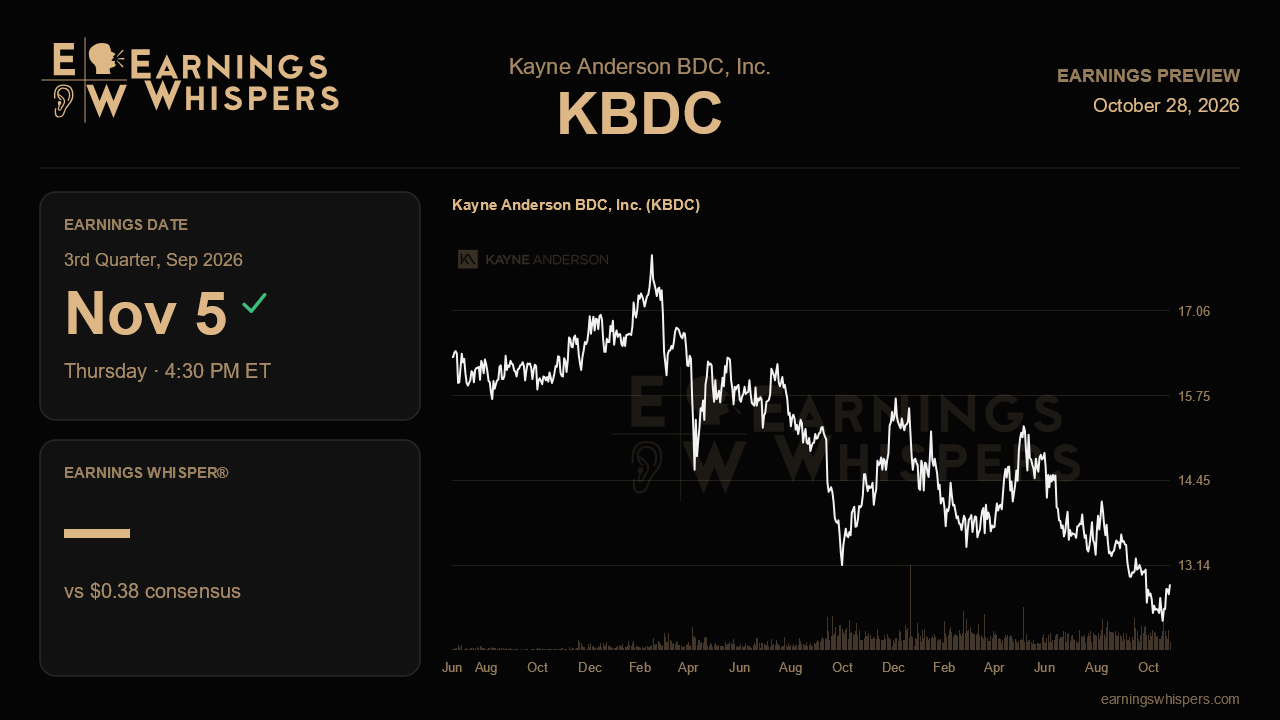
The number that matters most for Kayne Anderson BDC this quarter is not the earnings estimate on its own but how it stacks up against the dividend. Analysts expect net investment income of $0.38 per share, two cents below the 40-cent quarterly payout that management reaffirmed through 2026. If that estimate proves accurate, it would mark the first quarter in this recent stretch where earnings fail to cover the distribution. That would turn a slow, orderly softening into a more pointed question about how long the payout can rest on accumulated income rather than current earnings.
The forecast implies roughly an 11.6% decline from the $0.43 earned a year ago and a step down from last quarter's $0.42. That fits a clear pattern. Net investment income has drifted from 44 cents to 43 to 42 over recent quarters, and total investment income fell to $55.7 million last quarter from $61.4 million a year earlier. Dividend coverage compressed to 105% from 110% two quarters prior. Management cushioned concerns by pointing to about 26 cents of undistributed income, enough to bridge several quarters of modest shortfalls. A miss of a penny or two is survivable on paper. A consensus figure sitting below the dividend, however, means the Street already doubts that core earnings alone can carry the payout.
Last quarter's call offered genuine reasons for optimism alongside the deterioration. New loan spreads widened to 566 basis points over SOFR, the rotation out of lower-yielding broadly syndicated loans into private credit is finished, and portfolio yield edged up to 10.2%. New commitments rose to $138.7 million from $93 million, with another $69 million closed or nearing completion after quarter end. Leverage climbed to 1.17 times, though management attributed that to delayed repayments rather than a deliberate push. The validating evidence would be a quarter in which those wider spreads and a larger asset base start lifting interest income enough to offset lost income from troubled credits. If investment income stabilizes or grows from $55.7 million, the earnings floor may be closer than the estimate suggests.
Credit is the swing factor that could overwhelm all of that. Non-accruals rose to 2.7% of the portfolio from 1.4% just two quarters earlier, with 4over and a last-out tranche of Diversify newly added, and American Soccer already weighing on income. Net realized and unrealized losses cut net asset value by 26 cents to $16.00, and management shifted its language from emphasizing resilience to acknowledging credit noise and a shallow, slow economic slowdown. Another rise in non-accruals or a further NAV decline would challenge the idea that this is a gentle drift. Lumpy items also matter: last quarter's dip partly reflected a smaller payment-in-kind catch-up from Arborworks, so one-time income swings could distort the headline figure in either direction.
The market has not been patient. Shares are down 4.2% since the last report, trailing the S&P 500 by about 3.6 percentage points, and at $12.84 they trade well below the 200-day moving average of $13.83 and roughly 20% under last reported book value. The post-earnings range of $12.14 to $13.97 sits entirely below the prior quarter's $13.22 to $15.23 band, a sign the stock has reset lower. Sentiment remains heavily bearish at 74%, though that is less lopsided than the 84.5% reading before the previous report, suggesting some of the gloom may already be priced in.
Ultimately, this report hinges on whether stronger origination economics can arrest the slide in earnings before credit stress forces management to lean harder on its income buffer. Stable non-accruals, a steady NAV and income near the dividend would support the view that the 40-cent payout is secure. Fresh credit marks and earnings well short of the distribution would make that commitment look increasingly expensive to keep.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-09 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Aug-07 | |
| Jul-09 | |
| May-12 | |
| May-11 | |
| May-11 | |
| May-08 | |
| Apr-09 | |
| Mar-03 | |
| Mar-02 | |
| Mar-02 |
