El Pollo Loco Faces A Traffic And Produce Cost Test After Two Guidance Raises
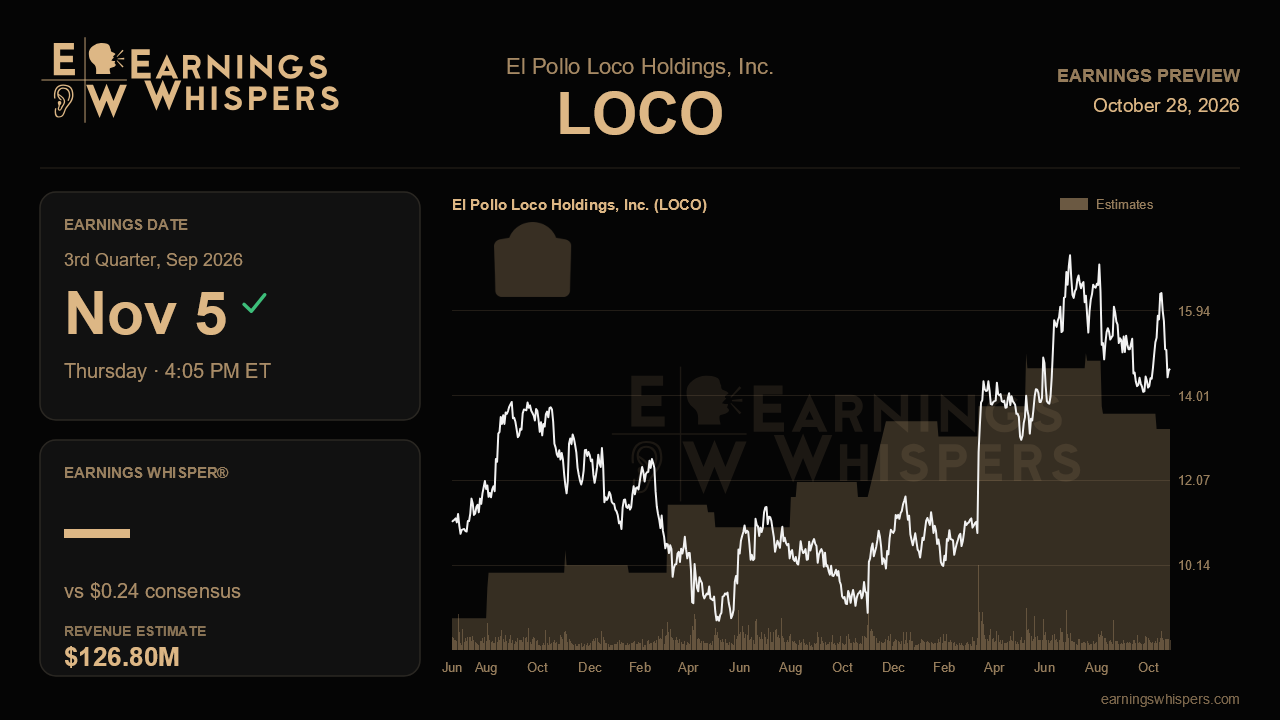
El Pollo Loco enters its third-quarter report with an awkward split between what management has been saying and what the stock has been doing. The company has raised its full-year outlook two quarters in a row, opened restaurants at nearly double last year's pace and started talking like a national brand. Yet shares have fallen about 13% since the last report while the S&P 500 was essentially flat. When results arrive after the close on November 5, the question is whether the momentum story holds up once the easy July numbers give way to a full quarter of tougher comparisons and costlier produce.
The Street is not asking for much on the bottom line. Consensus calls for earnings of $0.24 a share, down about 11% from $0.27 a year ago, on revenue of roughly $126.8 million, up a modest 4.3%. That combination of mid-single-digit sales growth and shrinking per-share profit fits the guidance management laid out last quarter. It steered third-quarter restaurant margins to 18% to 18.5%, a clear step down from the second quarter's 19.5% and roughly level with last year's 18.3%. Commodity inflation is the main culprit. Management lifted its full-year commodity forecast to 2.5% to 3.5%, up from 1% to 2% at the start of the year, with produce driving about three-quarters of the pressure. A slightly higher borrowing spread after the revolver refinancing adds a small headwind below the operating line.
The top line matters most. Management guided third-quarter system comps to 3.5% to 4.5%, even though the quarter-to-date pace through late July was running 5.8% on the back of World Cup advertising, the Loaded Quesadillas launch and the new Chata Coffee lineup. A result near or above the top of that range would suggest the summer lift came from the menu rather than a one-off sporting event. A result at the low end would imply August and September cooled sharply. The more important detail sits underneath the headline comp. Second-quarter transactions turned negative, down 0.9% system-wide after a small gain in the first quarter, so growth relied entirely on higher check. With effective pricing already easing to 3.4% from 4.6%, the company cannot lean on menu prices forever. Steady or positive traffic would be the strongest evidence that the value-tilted quesadilla offering and the Loco Tenders trial with younger diners are actually bringing people in.
Margin delivery is the second test. Hitting the 18% to 18.5% target while produce costs stay elevated would show cost discipline is real. Falling below it would cast doubt on the $68 million to $70 million adjusted EBITDA forecast. Given two consecutive raises, merely reaffirming that range would be acceptable. Another bump would signal that management sees the fourth quarter's harder comparisons as manageable. Development should also get attention. The company had 10 openings by midyear against a target of 18 to 20, plus a first Idaho unit and early talks about East Coast franchise deals. Concrete progress on signed agreements would help support the national ambitions.
Sentiment has cooled noticeably, with bullish readings slipping to about 28% from nearly 39% ahead of the last report, and the price action reflects that caution. At $14.62, the stock sits much closer to its post-earnings low of $13.95 than to its high of $17.15, though it remains slightly above its 200-day moving average. That lowers the bar somewhat, since the market has already discounted some disappointment.
In the end, this report hinges on whether El Pollo Loco can show that its comp growth is broadening beyond price. If traffic stabilizes and margins land within guidance despite produce inflation, the selloff will look like an overreaction to a company still executing. If transactions slide further and the comp drifts toward the low end, the narrative of steadily rising expectations will be much harder to defend.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-15 | |
| Oct-01 | |
| Sep-29 | |
| Sep-17 | |
| Sep-11 | |
| Sep-04 | |
| Aug-26 | |
| Aug-10 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Jul-15 | |
| Jul-10 | |
| Jul-08 |
