El Pollo Loco's Traffic And Growth Story Strengthens, But An In-Line Quarter And Trimmed Margin Guide Show Profits Lagging Sales
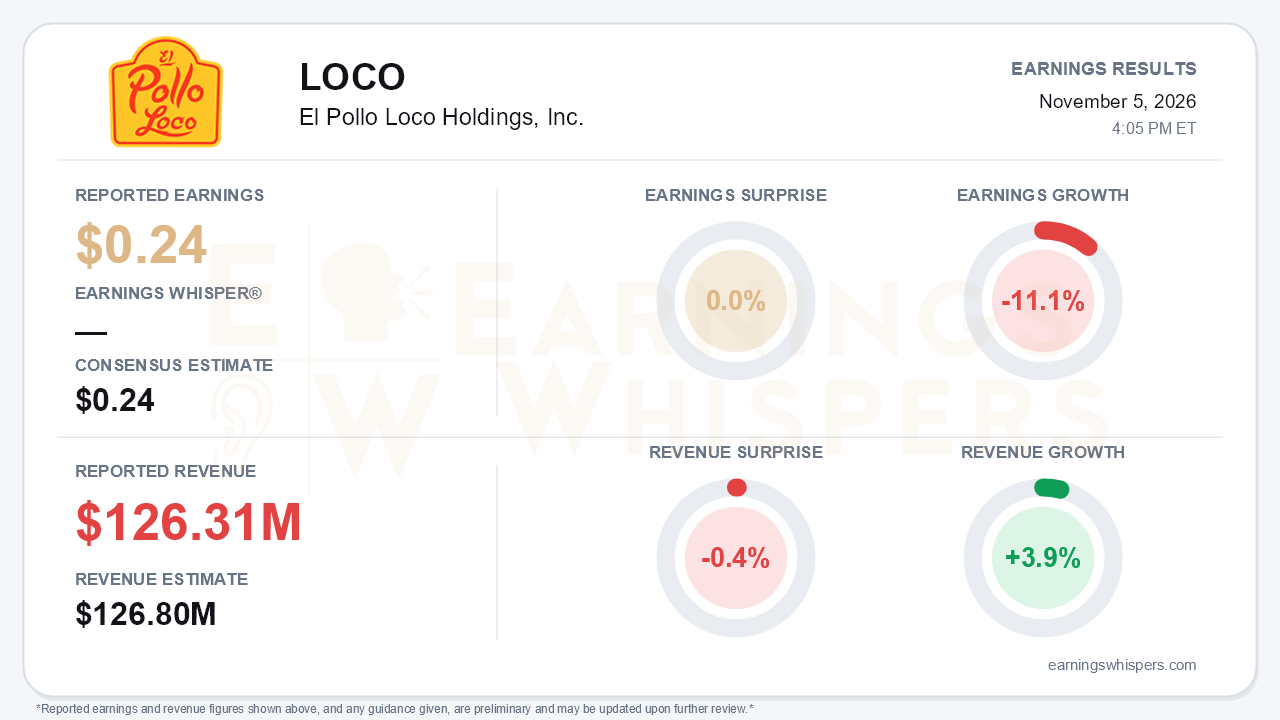
El Pollo Loco delivered a quarter in which the top line and development story clearly improved, but profitability did not keep pace. Adjusted earnings of $0.24 per share matched the consensus estimate exactly and fell 11.1% from a year ago. Revenue rose 3.9% to $126.31 million, which was 0.4% short of the $126.8 million consensus. That is the central tension. System-wide comparable sales accelerated to 5.0%, and traffic turned positive, yet adjusted EBITDA, adjusted EPS and GAAP operating income all declined year over year. The growth is real. The leverage from that growth has not yet shown up in earnings.
The quality of the quarter deserves a closer look. At the restaurant level, results were respectable. Company-operated comparable sales rose 4.4%, made up of a 4.0% increase in average check and a 0.3% increase in transactions. Restaurant contribution margin edged up to 18.4% from 18.3%. Higher utilities, repairs and maintenance, and third-party delivery fees offset much of the benefit from menu pricing.
The pressure came further down the income statement. General and administrative expense jumped 13.1% to $14.0 million, or 11.1% of sales, driven by incentive compensation, stock compensation and executive transition costs. Depreciation and amortization rose to $4.6 million from $4.0 million. Franchise revenue fell 3.0%, reflecting lapping POS-related IT pass-through revenue and a prior-year royalty true-up, even though franchise comps rose 5.3%. Income from operations slipped to $10.2 million from $11.5 million. Only a halving of interest expense, the result of paying down $28 million of revolver debt this year, kept GAAP EPS at $0.23 rather than falling further from $0.25. Year-to-date GAAP net income of $27.8 million also includes a $6.3 million legal settlement, so it overstates the underlying trend.
The call preserved a credible sales-momentum narrative. System comps improved from 3.9% in the second quarter to 5.0% in the third, beating the 3.5% to 4.5% guide management had given on its prior call. Traffic swung to +0.7% from -0.9%. Digital rose to 31% of system sales from 27% a year ago, and loyalty membership is up about 11%. Management lifted its full-year comp outlook to roughly 4.5%, the top of the prior range. That marks the fourth consecutive upward step from an initial 2% to 3%.
The margin picture moved the other way. Restaurant margin of 18.4% was well below the 19.2% and 19.5% posted in the first and second quarters. The full-year restaurant margin guide was trimmed to 18.25% to 18.5% from 18.25% to 18.75%. Commodity inflation is now expected to run a little over 3%, versus 1% to 2% at the start of the year, which more than offsets an improved wage outlook of about 1%. Adjusted EBITDA guidance of $68 million to $70 million was only reiterated after raises in each of the prior two quarters.
The forward signals carry the same split. Fourth-quarter-to-date comps of 3.6% have moderated from the third quarter. Management also said it plans to restrain 2027 pricing because the consumer is "a little stretched." That combination of rising food costs and limited pricing power gives bears legitimate ammunition on margins.
The offset is development, which is the biggest change in the story. The company opened 12 restaurants through the third quarter and reaffirmed 18 to 20 openings for 2026. It issued an initial 2027 target of 25 to 30 openings, well above the mid-single-digit unit growth framework it outlined early this year. Other development steps include:
- a signed Queens lease for a mid-2027 New York debut;
- franchise agreements covering 15 New York units over five years;
- richer incentives for brand-new markets; and
- a new chief operating officer, Damon Thomas, formerly of Shake Shack and Raising Cane's.
The expansion carries a cost. The revolver balance rose $4 million after quarter end to $27 million, and cash stood at just $3.4 million. Management also expects higher incentive spending tied to the New York build-out.
Investor sentiment remained positive but weakened noticeably heading into the report, falling to 0.23 from 0.39. Price action tells a more constructive story. Shares hit their inter-earnings high of $17.15 the day after the August report, then slid to a low of $13.95 in late September. They rebounded about 18% into this release. At $16.47, the stock sits 4% below that high, 2.4% below the post-August opening price, and roughly 16% above its 200-day moving average. Momentum and AVWAP trend readings are positive. That means the stock entered the report with much of the comp acceleration already reflected, leaving less room for an in-line print and a softer margin outlook.
The bottom line is that El Pollo Loco is executing well on traffic, digital and unit growth, and the 2027 development plan meaningfully raises the long-term growth profile. Near-term earnings power is moving the other way, with rising commodity costs, heavier G&A, a trimmed margin guide and pricing restraint ahead. Until sales gains translate into earnings growth, the setup rests more on expansion potential than on demonstrated profit leverage.
Read our earnings preview for El Pollo Loco Holdings, Inc.: https://www.earningswhispers.com/article/LOCO/22330
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-07 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-15 | |
| Oct-01 | |
| Sep-29 | |
| Sep-17 | |
| Sep-11 | |
| Sep-04 | |
| Aug-26 | |
| Aug-10 | |
| Aug-07 | |
| Aug-06 |
