NLIGHT's China Optics Snag Puts Defense Momentum And Fourth-Quarter Visibility On Trial
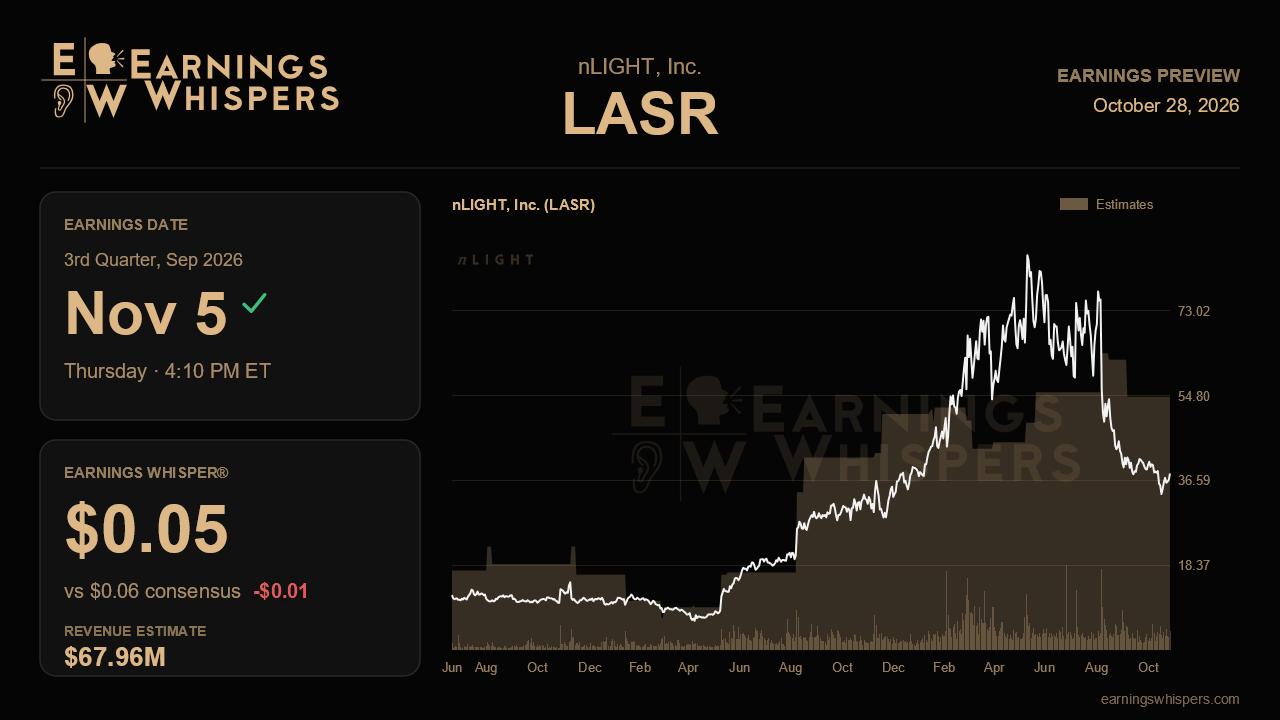
nLIGHT heads into its third-quarter report with a business that looked stronger than ever three months ago and a stock that has been treated as if something broke. The company posted record revenue, record aerospace and defense sales and record operating cash flow, then announced a Department of War award with a ceiling above $600 million. It also disclosed a sudden shortage of dual-use optics sourced from China that it said would leave roughly $17 million of third-quarter demand unfilled. The market chose to focus on the shortage. The upcoming release should show whether that was the right call.
Wall Street expects non-GAAP earnings of $0.06 a share on revenue of $68.0 million, which sits exactly at the midpoint of management's $63 million to $73 million guidance range. Consensus has also drifted up toward the midpoint from about $66 million when the outlook was issued, so analysts are not bracing for the worst. The Earnings Whisper of $0.05 is a penny below consensus. That gap is too small to signal deep skepticism, but it does suggest the informal bar is no higher than the published one. Revenue growth of just 1.8% over the $66.7 million reported a year ago would look flat. That year-over-year comparison hides the real story, though: an expected sequential drop of nearly 18% from the second quarter's $82.6 million, driven by a supply problem rather than weaker orders.
This is a quarter about plumbing more than demand. Management said demand was broad-based and accelerating across directed energy, sensing, munitions and additive manufacturing. If that holds, the key question is whether nLIGHT secured enough optics to land inside its range, or better yet, recaptured some of the lost $17 million. Margins are the second test. The company guided gross margin to 24% to 30% and product gross margin to 34% to 40%, both below recent norms. Product margin had already slipped to 41.2% in the second quarter on higher manufacturing spending. Adjusted EBITDA guidance of $1 million to $7 million compares with $10.7 million last quarter. Results near the top of those ranges would suggest the hit is mostly about volume and timing. Results at the bottom would raise concern that cost pressure is becoming structural.
The forward commentary may matter more than the quarter itself. Management called fourth-quarter execution a question mark. A clearer read on optics supply, whether through alternate sourcing, inventory rebuilding or progress on qualification, would go a long way toward lifting that cloud. Investors will also want early evidence that the JLWS award, which was supposed to begin contributing this quarter, is actually generating revenue. Management framed it as more than a replacement for the winding-down Healthy2 program. Any sign of slippage there would undercut that argument just as the exit from cutting and welding removes $25 million to $30 million of annual revenue.
Sentiment has improved to 36.6% bullish from 13.5% heading into the last report. Even so, the stock has fallen 34.7% since then while the S&P 500 was essentially unchanged. At $38.07, shares sit well below the 200-day moving average of $57.69 and in the lower part of the post-earnings range, about 14% above the $33.32 low. The previous quarter's trading floor near $57 now looks far away. A balance sheet holding about $331 million in cash gives the company room to work through the disruption. The heavy selling, however, means the market wants proof, not reassurance.
Ultimately, this report hinges on one question: is the China optics problem a temporary bottleneck on a growing defense franchise, or the start of a longer squeeze on revenue and margins? Results inside guidance, clearer fourth-quarter supply visibility and tangible JLWS revenue would support the bullish case. Another wide or lowered range would suggest the market's discount is deserved.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-12 | |
| Oct-11 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 | |
| Jul-20 | |
| Jul-10 | |
| Jul-10 | |
| Jul-09 | |
| Jul-09 | |
| Jun-08 | |
| May-15 | |
| May-13 |
