NLIGHT Crushes Low Bar And Guides To A Record Quarter, But The Supply Bottleneck Now Stretches Into 2027
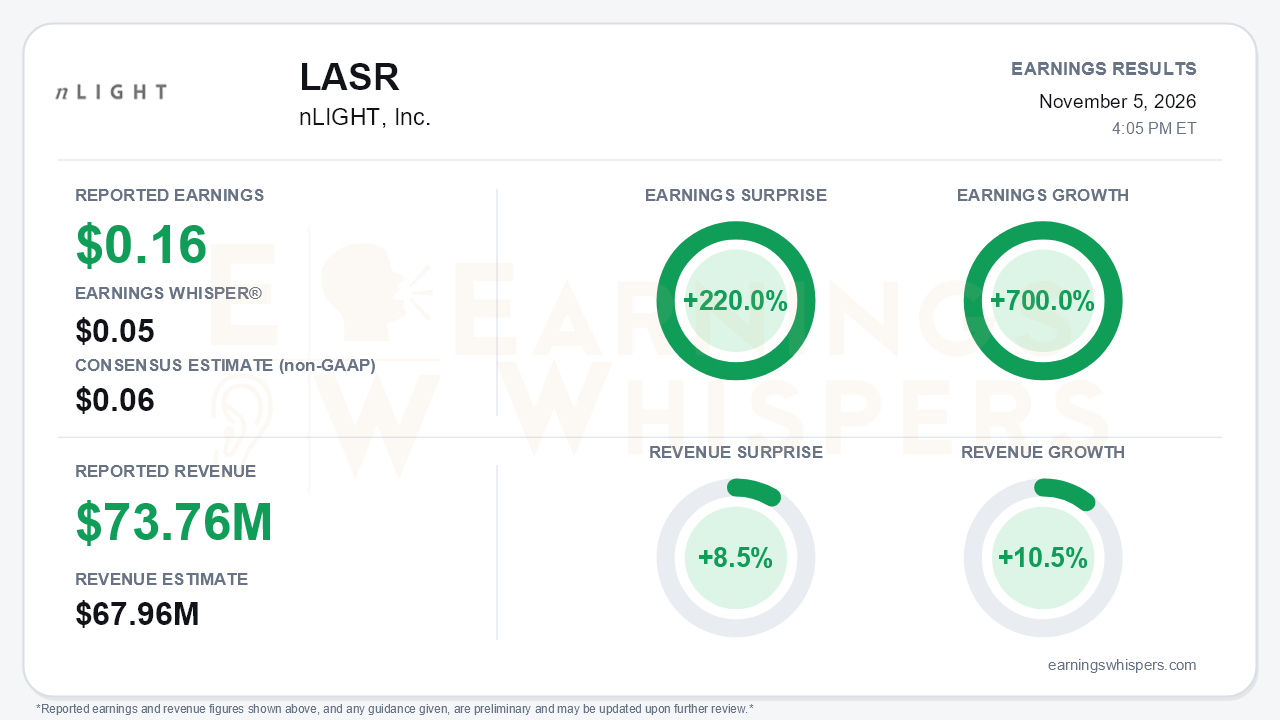
nLIGHT delivered the kind of beat that would normally reset a stock's narrative. Non-GAAP earnings of $0.16 per share topped the $0.06 consensus by 220.0% and cleared the $0.05 Earnings Whisper number. Earnings grew 700.0% from a year ago. Revenue of $73.76 million beat consensus by 8.5% and rose 10.5% year over year. Management then guided fourth-quarter revenue to $84 million to $90 million, a range whose midpoint would top the second quarter's $82.6 million record. The central tension is that this outperformance came inside a supply-constrained quarter, and the constraint is now lasting longer than management indicated three months ago.
The quality of the beat deserves scrutiny, because the headline masks a sharp deceleration. Revenue fell 11% sequentially from $82.6 million. Year-over-year growth slowed to 11% from 34% in the second quarter and 71% in the fourth quarter of 2025. Products revenue was essentially flat at $48.0 million versus $47.6 million a year ago. Growth came almost entirely from Development revenue, which rose 34% to $25.7 million but carries single-digit gross margins. Defense & Space revenue climbed to $52.5 million from $45.6 million. Advanced Manufacturing was flat year over year at $21.3 million and down 16% sequentially.
On a GAAP basis, nLIGHT lost $7.2 million, or $0.12 per share. That compares with a $6.9 million loss, or $0.14 per share, a year earlier and a $1.3 million loss in the second quarter. The main driver was a $7.5 million restructuring charge. The non-GAAP profit adds back that charge plus $9.9 million of stock-based compensation. Interest income of $2.5 million also helped, earned on cash raised in a roughly $192 million equity offering. That offering pushed the share count to 57.9 million from 50.3 million.
Margins were the cleanest positive. Product gross margin hit a record 47.4%, or 48.8% on a non-GAAP basis. That compares with a 34%-40% guide, 41.2% in the second quarter and 41.0% a year ago. Adjusted EBITDA reached $11.1 million against a $1 million to $7 million guide. On the call, management upgraded its framing of product gross margin to "comfortably above 40%" as a new baseline, from "consistently 40% or above" earlier in the year. Fourth-quarter guidance calls for:
- product gross margin of 40%-46%, a step down from the third quarter because some benefits are not expected to repeat;
- total gross margin of 30%-36%;
- Adjusted EBITDA of $12 million to $18 million, which implies the highest margin yet at the midpoint.
Management described demand as accelerating in both defense and advanced manufacturing. The JLWS program, which carries a $627 million ceiling, began its initial ramp. The company also cited allied counter-UAS interest, munitions replenishment and laser sensing ramps as growth drivers. The China exit is complete, reducing geopolitical exposure.
The supply chain is where bears have legitimate ammunition. On the second-quarter call, management flagged a $17 million shortfall, and only about $2 million of it was recovered. Another roughly $15 million of product revenue is now excluded from the fourth-quarter guide and pushed into the first half of 2027. Last quarter, management had left open the possibility of a fourth-quarter catch-up. The fixes will also cost money in the near term: second-sourcing, redesigns and possible in-sourcing of optics all carry higher costs. Inventory rose to $59.8 million from $45.4 million at year-end, and cash and investments slipped to about $314.5 million from $330.8 million last quarter. Management also acknowledged limited visibility into the second half of 2027, and an analyst raised competitive directed-energy entrants.
The market had already priced in considerable disappointment. Shares closed at $32.99 the day before the report, down 43.4% from the $58.27 open after the August release. That left the stock 42.6% below its 200-day moving average. It also sat within 1% of its inter-earnings low of $32.70, set on November 4, and 46.7% below the $61.95 high reached the day after the prior report. The Earnings Whispers price and AVWAP trend readings are negative, which is consistent with that slide. Investor sentiment nonetheless improved, rising to 0.27 from 0.13. That is a modest move that leaves expectations constructive but far from euphoric.
The setup is more complicated than the 220% surprise implies. The stock entered the report pricing in a broken growth story. The release instead showed record product margins, a record revenue guide and an expanding defense pipeline. The deferral of $15 million in shipments is a timing problem rather than lost demand, at least as management describes it. Even so, it is a timing problem that has now slipped twice.
The bottom line is that nLIGHT beat a deliberately conservative bar on every line and offered a credible record-quarter guide supported by structurally higher product margins. However, decelerating growth, a widening GAAP loss and a supply overhang now extended into 2027 mean investors must trust execution on recovery. The quarter's numbers alone cannot settle that question.
Read our earnings preview for nLIGHT, Inc.: https://www.earningswhispers.com/article/LASR/22327
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-12 | |
| Oct-11 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 | |
| Jul-20 | |
| Jul-10 | |
| Jul-10 | |
| Jul-09 | |
| Jul-09 |
