Kratos Faces A Show-Me Quarter As Raised Growth Outlook Collides With A 30% Stock Slide
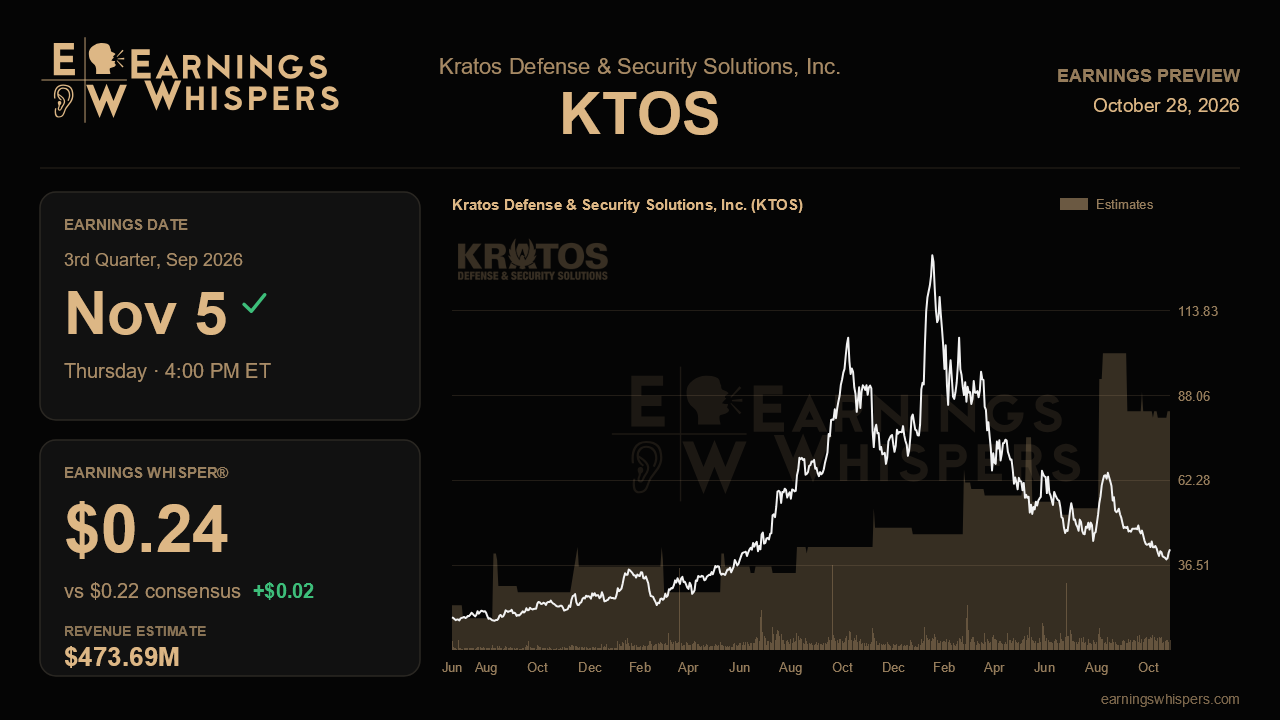
Kratos Defense & Security Solutions has done almost everything a growth story is supposed to do this year, and the market has responded by marking the stock down by nearly a third. Since the company last reported, shares have fallen 29.8% while the S&P 500 was roughly flat. That gap is the central tension heading into the November 5 report after the close. Management has raised its organic growth outlook three times in a row, yet investors appear to be pricing in either execution risk, cash burn fatigue, or skepticism that the second-half acceleration will actually show up.
The Street is looking for non-GAAP earnings of $0.22 a share on revenue of $473.7 million, which would be a 36.3% jump from the year-ago quarter's $347.6 million. The revenue figure sits comfortably inside management's third-quarter range of $460 million to $480 million, leaning toward the upper half rather than stretching beyond it. The earnings whisper of $0.24 is a couple of cents above consensus, a modest signal that the more engaged crowd expects Kratos to clear the bar again. That would fit the pattern: last quarter revenue of $458.8 million blew past a $400 million to $410 million guide, and adjusted EBITDA of $38.2 million topped the high end of its range.
The bigger test is whether the acceleration management promised is real. Full-year organic growth guidance has climbed from roughly 12.7% to 18.5% at the start of the year, to 15% to 19%, and then to 19% to 23%, with the third quarter guided to 19% to 25% organic growth and the fourth quarter to as much as 31%. Each raise lifts the bar for the next one. A print near the top of the range plus a reaffirmed or nudged-up annual outlook of $1.75 billion to $1.81 billion would validate the narrative. A result near the low end, or any softening of the fourth-quarter math, would challenge it, especially since management already assumes a continuing resolution that pushes budget clarity into January.
The operating details matter as much as the headline numbers. Hypersonics is the clearest proof point, with management tracking toward about $400 million this year, double 2025, and at least $700 million in 2027, backed by roughly $400 million in recently received funding and an operational Indiana integration facility. Investors should look for evidence that the newer wins, including a directed-energy counter-drone contract worth about $160 million and a roughly $100 million space domain awareness production award, are converting into revenue and bookings. The engine business is the newest catalyst: Kratos is ordering components for 3,000 small turbojets for 2027 at around $50,000 each, with more than 5,000 planned for 2028. Any update on supplier readiness or additional missile program wins would strengthen that thesis. Unmanned Systems, which grew just 8.1% organically last quarter versus 22% in Government Solutions, remains the laggard to watch.
The soft spots are margins and cash. The strengthening Israeli shekel cost $2.5 million of EBITDA last quarter and is expected to shave $5 million to $7 million for the year, capping margin expansion near 100 basis points. Free cash flow was negative $18.9 million as receivables swelled and the company prepaid for long-lead engine materials. Another quarter of heavy working capital consumption would be defensible if tied to the engine ramp, but investors will want to see receivables collected rather than piling up.
Sentiment has cooled slightly, to 13.4% bullish from 18.2% heading into the last report, and the stock at $41.32 sits far below its 200-day moving average of $65.58 and near the bottom of its post-earnings range. That lowers the emotional bar, but not the operational one. The report hinges on whether Kratos can show that the second-half acceleration is arriving on schedule while proving its investment spending is building a business rather than simply consuming cash.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 14 hours | |
| Oct-26 | |
| Oct-26 | |
| Oct-21 | |
| Oct-20 | |
| Oct-16 | |
| Oct-15 | |
| Oct-14 | |
| Oct-14 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-09 | |
| Oct-08 |
