Kratos Matches The Whisper And Posts Record Bookings, But Cash Burn And A Below-Street 2027 Guide Leave Shares Near A 52-Week Low
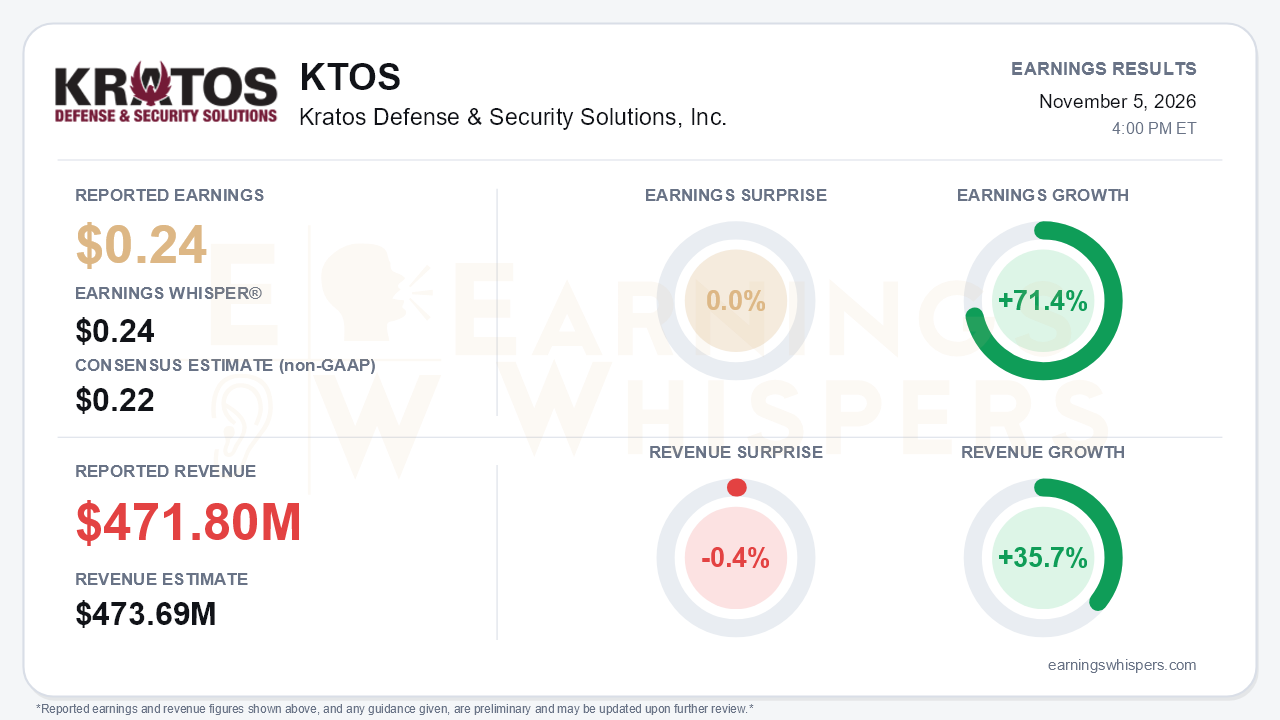
Kratos Defense & Security Solutions delivered adjusted earnings of $0.24 per share in the September quarter. That was two cents above the $0.22 consensus but exactly in line with the $0.24 Earnings Whisper number, so investors got a match rather than an upside surprise. Revenue rose 35.7% to $471.8 million but fell 0.4% short of the $473.69 million consensus, and adjusted EPS grew 71.4% year over year. The more important story sits below the headline. Kratos booked $1.037 billion of orders, a 2.2-to-1 book-to-bill, which pushed backlog to a record $2.65 billion from $2.08 billion a quarter earlier. At the same time, it continues to burn cash and gave a first look at 2027 that trails Street revenue expectations. That is the central tension: the order book and margins are accelerating, while the stock has been trading as though the story is breaking.
The quality of the quarter is mixed. Adjusted EBITDA of $50.9 million, a 10.8% margin, cleared the $40-45 million guide and rose from $38.2 million (about 8.3%) in the June quarter. That is real operating leverage, led by the Government Solutions segment, where EBITDA nearly doubled to $46.3 million. On a GAAP basis, however, Kratos swung from net income of $8.7 million to a $0.2 million net loss and posted a $4.9 million operating loss. Several items drove the gap:
- Stock compensation doubled to $18.1 million.
- Amortization of intangibles and capitalized contract costs climbed sharply after the Nomad and Orbit acquisitions.
- Unallocated corporate expense rose to $19.0 million from $9.3 million.
Pretax income was propped up by $8.7 million of interest income on a $1.4 billion cash pile built largely through $1.35 billion of equity issuance this year. Diluted shares rose to 188.8 million from 172.9 million. Organic growth of 23.2% is strong, but acquisitions account for a meaningful share of the 35.7% headline.
The operating mix also shifted. Government Solutions grew 35.8% organically, and Defense Rocket Systems surged 149%, up from roughly 50% in the June quarter, as hypersonic funding reached about $600 million versus about $400 million cited previously. Unmanned Systems moved the other way. Revenue fell to $74.6 million against a quarter that included a $16.1 million international Valkyrie shipment, segment book-to-bill was just 0.8, and backlog slipped to $357.4 million. Management countered with what may be the most consequential development on the call: a Valkyrie low-rate initial production contract from an undisclosed customer, with a fourth-quarter revenue ramp expected. The call also brought engine wins that broaden the propulsion thesis:
- The J85 was selected for Boeing's JDAM-LR.
- The GEK800 was chosen as the second-source JASM engine, with an EMD contract.
- The plan for 3,000 engines in 2027 was reaffirmed, including roughly 1,500 sales weighted to the second half.
Guidance carries both sides of the argument. Kratos raised full-year 2026 adjusted EBITDA to $176-180 million and tightened revenue to $1.78-1.81 billion, up from $1.59-1.675 billion at the start of the year. The initial 2027 forecast of $2.1-2.2 billion in revenue and $230-240 million in EBITDA implies 18-22% growth and modest margin expansion. Management called it conservative against a considerably higher internal roll-up, citing the continuing resolution, a lame-duck and divided Congress, and a first quarter of 2027 it expects to be the trough. Bears still have legitimate ammunition:
- The top end of the fourth-quarter organic growth range was trimmed.
- Cost-plus mix has climbed from 23% to 32% this year, capping margin upside.
- Large space prime contracts would carry lower margins.
- Free cash flow was negative $29.4 million in the quarter, and days sales outstanding rose to 125 from 114.
- Full-year free cash flow use is guided at $110-120 million, and management does not expect positive cash flow until 2029.
The market had already priced in plenty of skepticism. Shares closed at $35.96 the day before the report, down 38.9% since the open after the August release. They sit 42.6% below the 200-day moving average and 46.4% below the inter-earnings high of $67.10 reached on August 14. The stock set a 52-week low of $35.71 on November 4, the eve of the report. Investor sentiment improved modestly, from 0.18 to 0.23, and remains only mildly positive. The Earnings Whispers trend readings reflect the same split: sequential growth and momentum are positive, while price and AVWAP trends remain negative.
The bottom line is that Kratos produced a fundamentally stronger quarter than its stock chart suggests. Record orders, an EBITDA beat, rising hypersonic funding and a long-awaited Valkyrie production award all point to a business that is gaining traction. Still, an in-line print against the whisper, a slight revenue miss, GAAP losses, ongoing dilution and cash burn stretching to 2029 give investors reasons to demand proof. A 2027 outlook that hinges on appropriations timing in Washington adds to that caution. Whether the backlog converts on schedule, not the size of the pipeline, will decide whether this report marks a turning point.
Read our earnings preview for Kratos Defense & Security Solutions, Inc.: https://www.earningswhispers.com/article/KTOS/22326
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-04 | |
| Oct-28 | |
| Oct-28 | |
| Oct-26 | |
| Oct-26 | |
| Oct-21 | |
| Oct-20 | |
| Oct-16 | |
| Oct-15 | |
| Oct-14 | |
| Oct-14 |
