Karman Faces A Cash And Leverage Test As Record Backlog Meets A 33% Stock Slide
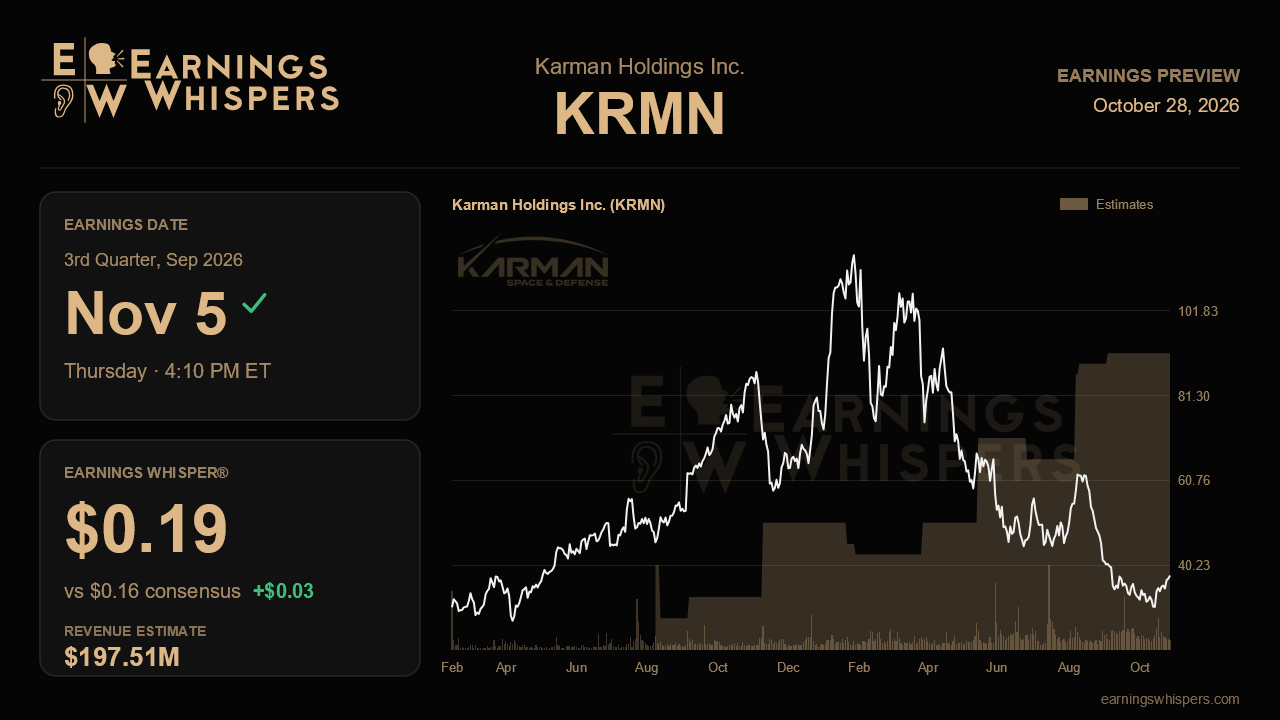
Karman Space & Defense heads into its third-quarter report with one of the more striking disconnects in aerospace. Management has raised full-year guidance three calls in a row, pushed backlog to a record $1.3 billion and described customers talking about production increases of up to 10 times current build rates. Yet the stock has fallen nearly 33% since the last report while the S&P 500 was essentially flat. The question for Thursday's after-the-close release is whether the operating story is still accelerating, or whether the market's concerns about cash burn and borrowing are starting to show up in the numbers.
The Street is looking for earnings of $0.16 a share on revenue of $197.5 million, which would represent growth of roughly 60% on both lines from a year ago. That is a strong number, helped by acquisitions, and it implies a modest sequential step up from the $182.1 million booked last quarter. The whisper number of $0.19 sits meaningfully above consensus, suggesting that the more engaged part of the market expects Karman to clear the published bar with some room to spare. On the full year, management's latest revenue range of $730 million to $745 million brackets a consensus of about $730 million, which sits right at the low end. With the first half already in hand, the guidance implies roughly $400 million of second-half revenue, so a Q3 print near or above $197.5 million keeps the midpoint comfortably in reach and leaves room for a fourth consecutive raise.
The backlog story deserves the closest look. Bookings of roughly $500 million last quarter were mostly aimed at 2027 and beyond, so the useful signal this time is whether new orders keep pace with an accelerating revenue run rate and whether the four contingent supply agreements flagged earlier, potentially worth more than $1 billion, continue converting into firm contracts the way the five-year space and launch agreement did. Updates on the second-source opportunities in separation motors, anti-armor propulsion, large rocket motor cases and interceptor shrouds would help show that the 10x demand talk is translating into real awards rather than conversation.
The weaker parts of the last call are where the report could disappoint. Operating cash flow was negative last quarter as receivables and contract assets ballooned, and management guided to only $15 million to $20 million of free cash flow for the entire second half while it invests ahead of orders. Net debt reached $752 million and leverage of about 3.7 times overshot the roughly 3 times the company had targeted earlier, with the year-end goal now reset to about 3.5 times. Any further slippage there, especially if the Walker Precision deal adds to borrowings, would reinforce the bearish case. Margins also matter: the EBITDA outlook already assumes a slight second-half dip from a heavier cost-plus mix, so a deeper decline would be a warning sign. With organic growth now disclosed only annually, investors have less visibility and will lean harder on these other indicators.
Sentiment has swung from clearly bearish before the last report to moderately bullish now, even as the share price collapsed. At $37.73, the stock trades far below its 200-day moving average near $65 and sits closer to the bottom of its post-earnings range of $29.34 to $63.73, a sharp downshift from the prior quarter's $43.68 to $70.86 band. That positioning means expectations embedded in the price look considerably lower than the operating guidance would suggest.
Ultimately, this report hinges on whether Karman can show that its growth is self-funding. Revenue and backlog have rarely been the problem. If cash conversion improves and leverage moves credibly toward 3.5 times while bookings stay strong, the narrative of a high-growth defense supplier investing wisely remains intact. If working capital keeps absorbing cash, even another guidance raise may not be enough to win back skeptics.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-26 | |
| Oct-26 | |
| Oct-22 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-16 | |
| Oct-16 | |
| Oct-14 | |
| Oct-13 | |
| Oct-09 | |
| Sep-09 | |
| Sep-01 | |
| Aug-31 |
