Karman Matches The Whisper And Raises Guidance Again As Backlog Hits $1.7 Billion, But Shares Remain Deeply Below Trend
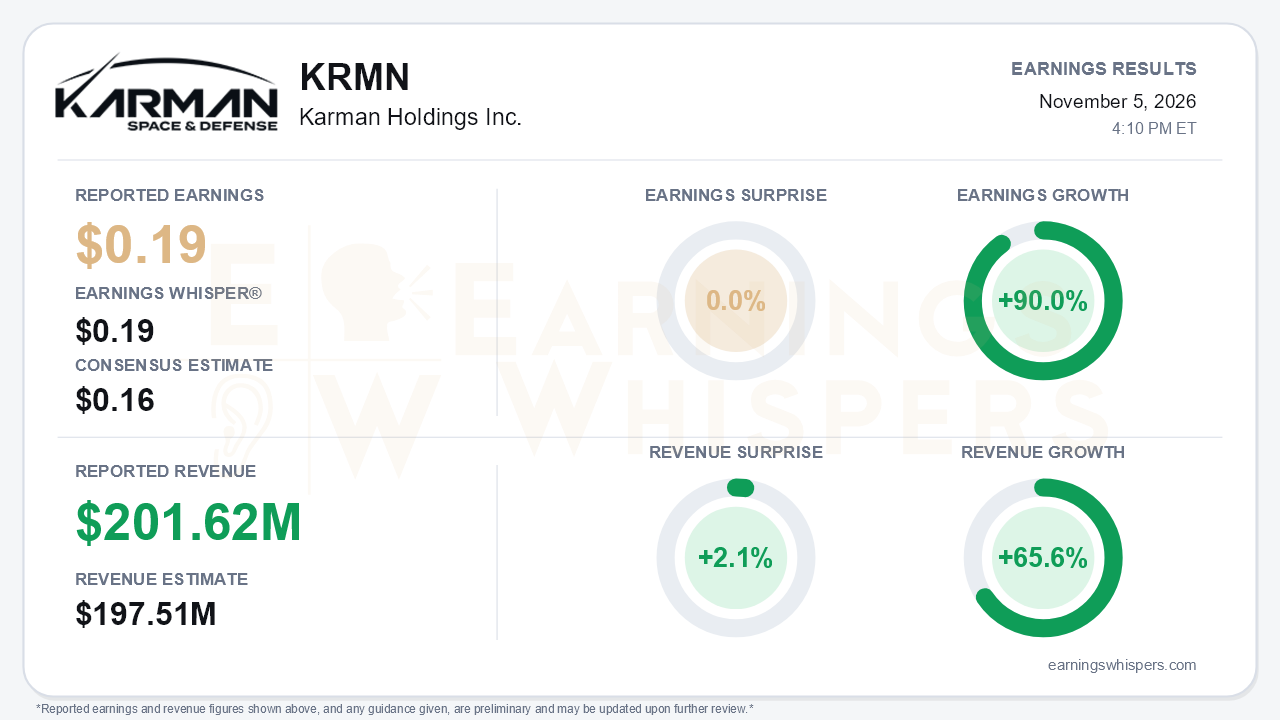
Karman Holdings (NYSE: KRMN) delivered adjusted earnings of $0.19 per share for the September quarter. That was ahead of the $0.16 consensus but exactly in line with the $0.19 Earnings Whisper number, a 0.0% surprise against the whisper. Revenue of $201.62 million beat the $197.51 million consensus by 2.1%. Earnings grew 90.0% year over year and revenue grew 65.6%. The quarter itself merely met elevated expectations. What matters is the forward picture. Management raised fiscal 2026 guidance for the third consecutive quarter and lifted backlog to a record $1.7 billion. Even so, the stock has fallen almost 40% since the last report. That disconnect is the central tension.
The quality of the quarter deserves a closer look, because GAAP and adjusted results tell different stories. GAAP net income jumped 174% to $20.9 million, or $0.16 per share. Most of that gain came from a $7.6 million tax benefit tied to R&D credits. Pre-tax income rose only about 12%, to $13.3 million, as interest expense nearly doubled to $18.0 million and G&A more than doubled to $41.5 million. The adjusted EPS figure actually backs out the tax-credit benefit, so the $0.19 is the cleaner read. Adjusted EBITDA rose 60% to $60.5 million. The 30.0% margin, however, was slightly below the 31.0% of a year ago, so the leverage from 66% revenue growth is not showing up as margin expansion. Free cash flow turned positive at $13.4 million, a welcome change from the cash burn earlier in the year, but it remains negative $11.5 million year to date.
The operating story underneath is strong but not uniformly so. Organic growth was 25%, roughly matching the 24.4% pace in the June quarter. Tactical Missiles rose 52% and Hypersonics/Strategic Missile Defense rose 40%, both driven by interceptor and counter-UAS production. Maritime revenue of $45 million was up 30% sequentially and ahead of plan. Space & Launch, however, fell 7% because of the ULA Vulcan schedule shift. That segment has decelerated from +29% in Q1 to +6% in Q2 and now -7%, though management expects a 2027 rebound. Sequential revenue growth also cooled, from 20% to 11%. In addition, the call softened organic growth language from "25% or higher" to a "20-25%" annual algorithm.
The bigger development is how much visibility Karman is building. Guidance now calls for $755-$760 million in revenue and $225-$227 million in adjusted EBITDA, up from $730-$745 million and $215-$222.5 million last quarter. Management attributed most of the raise to performance rather than the Walker Precision acquisition, and said it has full visibility to the midpoint. Bookings of roughly $465 million followed about $500 million in Q2. They included a $218 million, seven-year THAAD agreement with Lockheed Martin. Two more seven-year solid rocket motor agreements are expected this year, and second-source pursuits have grown to five, with two in qualification. The CEO described the 2027 ramp as steeper than forecast and said the long-term agreements will not dilute margins.
Bears still have legitimate ammunition:
- 2027 adjusted EBITDA margin is framed flat at about 30%.
- CapEx is rising to 5-6% of revenue.
- Net debt has climbed $325 million since year-end to $791 million, driven by acquisitions.
- Remediation of a material weakness has slipped to mid-2027.
- The CFO is changing.
- A continuing resolution and a possible shift in congressional control could delay defense appropriations.
On the positive side, leverage fell to 3.2x from 3.7x and is now guided below 3x by year-end. The second-half free cash flow target also rose to at least $20 million.
The market setup is more complicated than the fundamentals imply. Shares entered the report at $34.17. That is down 39.1% from the $56.10 open after the August report and 45.7% below the 200-day moving average of $62.98. The stock peaked at $63.73 on August 17, then collapsed to a 52-week low of $29.34 on October 15, and has since recovered about 16.5%. The supplied materials do not explain the selloff, and nothing in this report suggests operating deterioration on that scale. Investor sentiment swung meaningfully, from -0.34 to +0.31, flipping from negative to positive. Earnings Whispers momentum and AVWAP trend readings have also turned positive, consistent with the bounce off the October low.
The bottom line is that Karman delivered a whisper-matching quarter wrapped around a materially stronger forward story. The third straight guidance raise, a backlog that has more than doubled since year-end, and multi-year agreements extending visibility into 2027 all support that story. The flaws are real: flat margins, heavier debt and capex, a stalled Space & Launch segment, and softer organic growth language. They are not, however, the profile of a company whose stock should trade 46% below its long-term average on fundamentals alone. Investors will need to see bookings, cash conversion, and appropriations clarity to close that gap.
Read our earnings preview for Karman Holdings Inc.: https://www.earningswhispers.com/article/KRMN/22322
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Oct-28 | |
| Oct-26 | |
| Oct-26 | |
| Oct-22 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-16 | |
| Oct-16 | |
| Oct-14 | |
| Oct-13 |
