Moelis Must Convert An 80% Pipeline Surge Into Fees As Shares Lag Badly
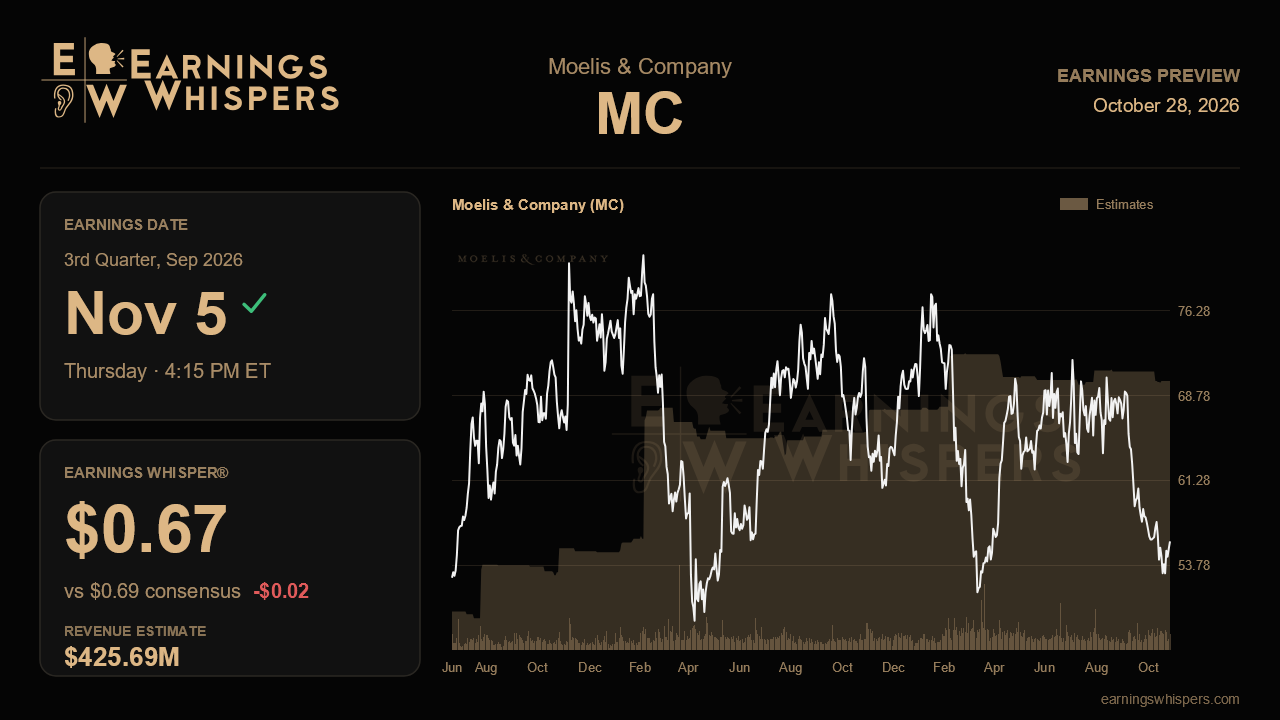
Moelis & Company heads into its third-quarter report with an awkward mismatch. Last quarter management described a record total pipeline, an announced pipeline up 80% from a year earlier and a long-missing mid-market finally stirring. Yet the stock has fallen 16.3% since that call while the S&P 500 gained 4.6%. Either the market doubts that pipeline will close on schedule, or it is worried that whatever revenue does arrive will be eaten by rising costs. The November 5 release, due after the close, is a test of both concerns.
The Street is looking for revenue of about $425.7 million, up 19.3% from $356.9 million a year ago and a modest step above the record $409.4 million posted last quarter. Earnings are a different story. Consensus calls for $0.69 a share, barely above the year-ago $0.68, implying growth of just 1.5%. The Earnings Whisper sits a touch lower at $0.67. The gap is small, but it suggests the bar is not being quietly raised. The more telling point is the spread between nearly 20% top-line growth and almost flat profits. Analysts appear to be modeling limited operating leverage, so revenue alone may not settle the debate. With no formal guidance on the table, the cost commentary from last quarter's call becomes the main yardstick.
That commentary cut both ways. Management held its compensation ratio near 65.8%, matching full-year 2025, and the pre-tax margin widened to 18.6% from 17.6% in the year-ago quarter. But it also flagged a pricier, more competitive market for senior bankers, and it nudged non-compensation expense up to the mid-to-high $60 million range per quarter on syndication and deal costs. Lateral hiring has accelerated to 12 managing directors year to date, and new hires usually cost money before they generate fees. A comp ratio that holds near 66% while non-comp spending stays inside the stated range would support the margin story. Any slippage on either line would explain why the Street is so cautious on earnings.
On the revenue side, the key question is whether the announced pipeline is turning into completed fees. Management said its M&A pipeline was skewing toward larger deals with bigger average fees, and that activity had picked up in the $1 billion to $5 billion mid-market, which had been absent for most of the prior year. Evidence that sponsors are starting to sell those 2019 to 2021 vintage assets would be meaningful validation. The firm has also been building businesses outside M&A:
Capital markets posted record revenue last quarter.
The private capital advisory group now has seven dedicated managing directors in GP-led secondaries and has added LP-led secondaries and promoted co-investment.
A securitization capability came online.
Progress in these lines would show the recovery is broadening. Capital structure advisory remains the soft spot, having declined year over year again last quarter. Stabilization there would remove a drag, and lender selectivity toward highly levered borrowers could eventually help that business.
Sentiment has swung sharply. Bullish readings now stand around 74%, up from roughly 16% before the last report, even as the share price has fallen. At $55.88, the stock trades well below its 200-day moving average of $64.27 and closer to the $51.39 low of its post-earnings range than to the $70.51 high. That combination points to optimistic expectations on the business but a skeptical price. Management's newly stated openness to a sizable acquisition adds another variable, since any update on deal criteria could shape how the market views capital allocation.
Ultimately, the report has to show that a record pipeline can produce record fees without costs absorbing the gains. Strong revenue alongside a steady comp ratio and contained non-comp spending would argue the selloff overshot. Strong revenue with thin profit growth would suggest the market's caution about the cost of growth was justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-15 | |
| Sep-21 | |
| Sep-18 | |
| Sep-18 | |
| Aug-10 | |
| Jul-31 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-27 | |
| Jul-22 | |
| Jul-09 | |
| Jul-08 |
