Moelis Beats On A 40% M&A Surge, But Slowing Pipeline Growth And A Softer Margin Cloud The Outlook
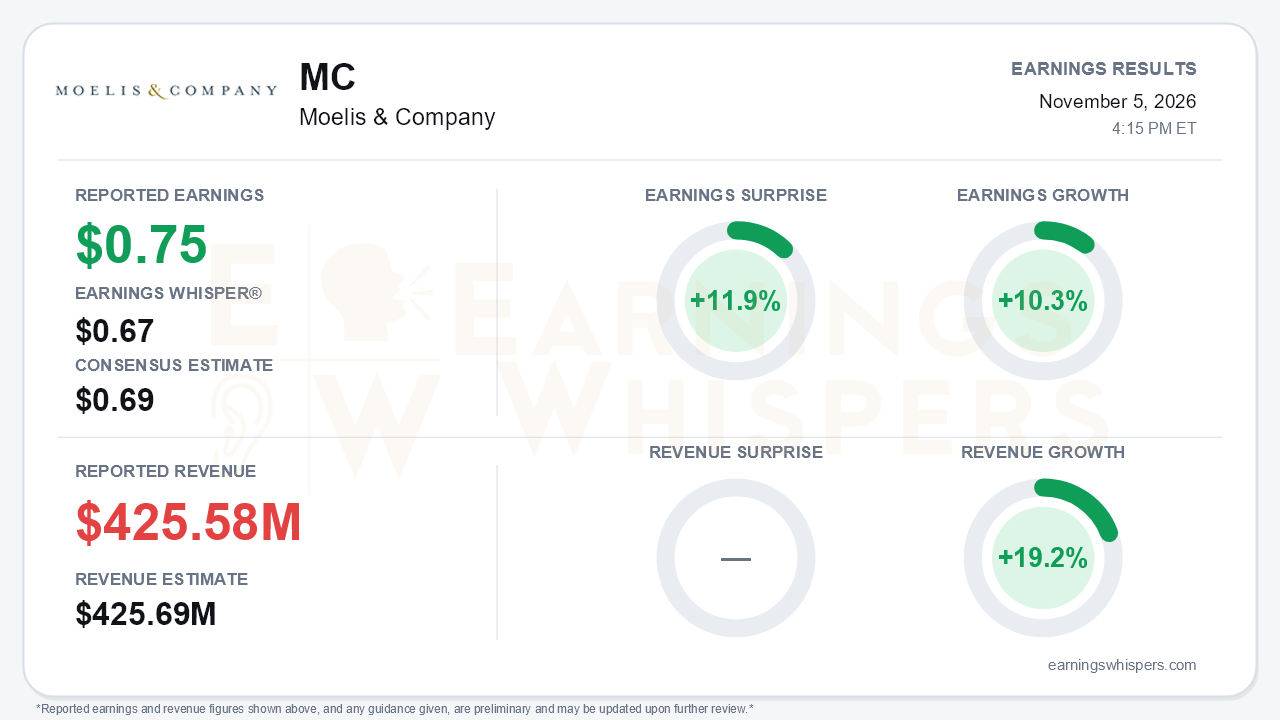
Moelis & Company delivered a clean earnings beat in the third quarter. Adjusted EPS of $0.75 topped the $0.69 consensus by 11.9% and cleared the $0.67 Earnings Whisper number, with earnings up 10.3% from a year ago. Revenue of $425.58 million matched the $425.69 million consensus almost exactly, so the upside came below the top line. The more important story is forward-looking. Current results are strengthening, led by a 40% jump in M&A revenue, while the leading indicators management discussed on the call cooled noticeably. That is the central tension.
The revenue growth figure needs context. Revenue rose 19.2% year over year on a reported basis. On the company's adjusted basis, growth was 13%, because last year's adjusted revenue included a $19.1 million gain on the sale of MA Financial Group shares. Even the 13% figure marks continued acceleration from 12% in the second quarter and 4% in the first. Nine-month revenue reached a record $1.15 billion, up 10%. Management attributed the gains to record average fees per completed transaction rather than higher deal volume.
The quality of the beat deserves some scrutiny. Adjusted pre-tax income rose only 9%, and the adjusted pre-tax margin slipped to 21.4% from 22.2% a year earlier. Several factors explain the gap:
- The compensation ratio improved only slightly, to 65.8% from 66.2%.
- Non-compensation expenses climbed 17% on new office space, AI and technology spending, and heavier deal travel.
- Adjusted other income fell 23%.
- A lower adjusted tax rate of 28.9%, versus 29.4%, helped carry net income growth to 10%.
The comp ratio has now sat at 65.8% all year. Management still expects some reduction by year-end, but it has not appeared yet. Full-year non-comp growth is now tracking around 19%, well above the first-quarter guide of growth similar to 2025's rate. The nine-month adjusted pre-tax margin of 18.6% does compare favorably with 18.2% a year ago.
Beneath the headline, the business mix shifted decisively toward advisory. M&A now represents roughly 70% of revenue, up from about two-thirds, driven by strategic M&A and larger, more complex assignments. Sponsor transaction counts rose about 30% through nine months. Capital structure advisory posted one of its strongest quarters on record, reversing year-over-year declines in the first half. Management expects that work to shift toward traditional restructuring and liability management over the next 12 to 18 months. It cited stress in software and AI-related credits and a wall of 2028-29 maturities, which gives the firm a credible counter-cyclical lever. Capital markets went the other way, softening after a record first half because volatility disrupted deal timing.
The forward signals are where bears have legitimate ammunition:
- **Pipeline:** The total pipeline is at a record and new business origination is up about 20%. But announced-pipeline growth slowed to roughly 20% year over year from 80% at the second-quarter call.
- **Tone:** Management declined to repeat its earlier "early innings" description of the M&A cycle. It flagged risk from any slowdown in AI infrastructure financing and said it was still "processing the last 48 hours" of post-midterm market moves.
- **Costs and taxes:** A Section 162(m) change could add a few points to the tax rate from 2027, and AI and technology spending is expected to keep rising.
- **Capital return:** Buybacks slowed to about $19 million in the quarter, even as cash grew to $658.7 million with no debt.
The growth investment is real. Thirteen managing directors have joined year-to-date and 11 more are committed through 2027, the most active recruiting year on record. Private Capital Advisory is being built out across GP-led secondaries, primary fundraising, and LP-led and co-investment teams. That hiring supports future revenue capacity but keeps cost pressure elevated in the near term.
Investor expectations had already deflated before the report. Earnings Whispers sentiment fell from 0.16 to 0.05, remaining marginally positive but noticeably weaker. Shares entered the report at $61.35, down 8.1% from the opening price after the July report. That leaves the stock 3.7% below its 200-day moving average of $63.72 and 13% below the August 13 inter-earnings high of $70.51. However, the stock had rebounded 19.4% from its October 22 low of $51.39, suggesting buyers were already stepping back in ahead of the print. The Earnings Whispers trend readings are mixed: sequential growth and momentum are positive, while price and AVWAP trends remain negative.
The bottom line is that Moelis produced the quarter its advisory franchise needed: accelerating revenue, record fees, a resurgent restructuring practice, and a comfortable EPS beat. Margins slipped year over year and cost growth keeps outrunning early guidance, so operating leverage has not yet arrived. A sharply slower announced pipeline and a more guarded management tone also argue that the easy part of the M&A recovery may be behind it. Restructuring demand and the hiring wave give Moelis multiple paths to growth. Whether the comp ratio finally bends and the pipeline re-accelerates will determine whether this beat marks durable momentum or a peak in the near-term cycle.
Read our earnings preview for Moelis & Company: https://www.earningswhispers.com/article/MC/22336
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-28 | |
| Oct-15 | |
| Sep-21 | |
| Sep-18 | |
| Sep-18 | |
| Aug-10 | |
| Jul-31 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-27 |
