Morgan Stanley Direct Lending Faces Dividend Coverage Test As Street Sees NII Slipping Below 45 Cents
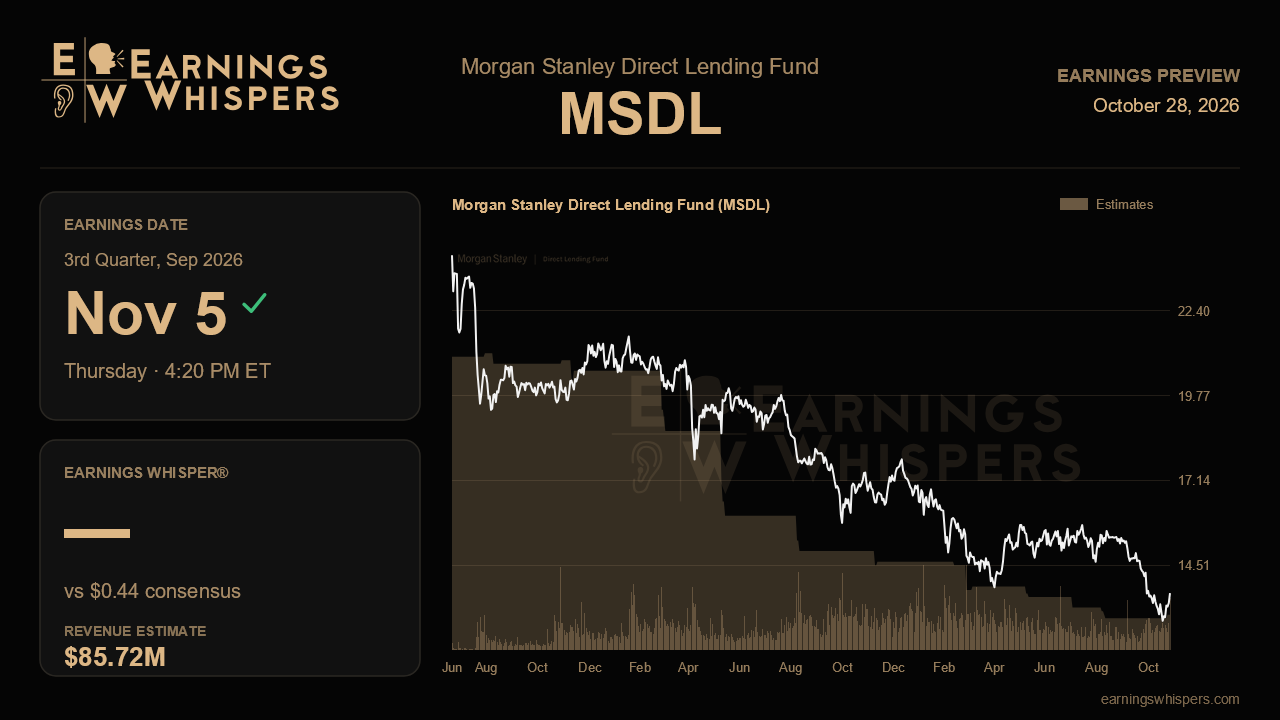
For a business development company, the dividend is the scoreboard, and Morgan Stanley Direct Lending Fund heads into its September-quarter report with the Street forecasting a number that falls just short of it. Consensus calls for earnings of $0.44 per share, a penny below the 45-cent quarterly payout that management set when it cut the dividend from 50 cents at the start of the year. Last quarter, net investment income only barely covered that reset distribution. A shortfall this time, however small, would raise the question the company has been trying to put to rest: whether the reset was large enough.
The expectations describe a shrinking earnings base rather than a collapse. Revenue is projected at $85.7 million, down from $88.8 million last quarter and roughly 14% below the $99.7 million earned a year ago. Earnings per share are expected to fall about 12% from the year-ago 50 cents. Management has not issued formal guidance. Instead, the benchmark comes from the trajectory it described: net investment income has stepped down four straight quarters, from 50 cents to 49, 47 and then 45, and the Street is effectively betting on a fifth.
The swing factors are the ones management highlighted last quarter. On the positive side is the Capstone joint venture. Its contribution to net investment income rose from about a penny to 3 cents in a single quarter, and management expects assets to grow toward roughly $700 million over the coming year. If commitments and called equity keep climbing from the 58 companies and 52% reported last time, the venture could add another penny or so and offset weakness elsewhere. Buybacks are the second support. They added 10 cents to net asset value in the first half, and with the shares now trading near 70% of the last reported $19.50 NAV, every repurchase is even more accretive.
The headwinds look more stubborn. Non-accruals jumped from 1.5% to 2.9% of cost after three names were added, which drags on portfolio yield. Repayments of $240 million outran $146 million of fundings, shrinking the portfolio to $3.6 billion. Management has also called the rise in financing costs a permanent re-rate. The June issue of $350 million in unsecured notes, made ahead of a $425 million maturity in February 2027, strengthens the balance sheet. It may also leave the company carrying extra debt for a few quarters, which typically dilutes earnings. A stable or lower non-accrual rate, net portfolio growth helped by the more lender-friendly spreads near SOFR plus 500 that management described, and a fifth straight NAV decline being avoided would all support management's view that this is a period of transition. More credit migration would undercut it, especially if it extended beyond names already flagged.
The market has already taken a skeptical view. The shares have fallen 11.4% since the last report, while the S&P 500 was essentially flat over the same stretch. At $13.64, the stock sits well below its 200-day moving average of $15.02. It is also much closer to its post-earnings low of $12.71 than to its high of $15.68, a range that is both wider and lower than the prior quarter's. Sentiment has deteriorated as well, with bearish readings rising from about 39% to more than 57%. That lowers the bar somewhat, but it also shows how little patience remains for another credit surprise.
In the end, the report hinges on whether 45 cents marks a floor. If the joint venture ramp and accretive buybacks can hold net investment income at the dividend while non-accruals stabilize, the steep discount to NAV starts to look overdone. If credit costs and a shrinking portfolio push earnings below the payout again, investors will begin pricing in a second dividend reset.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-27 | |
| Oct-05 | |
| Aug-31 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Jul-06 | |
| Jun-29 | |
| May-07 | |
| May-07 | |
| May-06 | |
| Apr-06 | |
| Feb-27 | |
| Feb-26 |
