Morgan Stanley Direct Lending Fund Beats On NII, But A Fee-Flattered Quarter Can't Hide Another NAV Slide
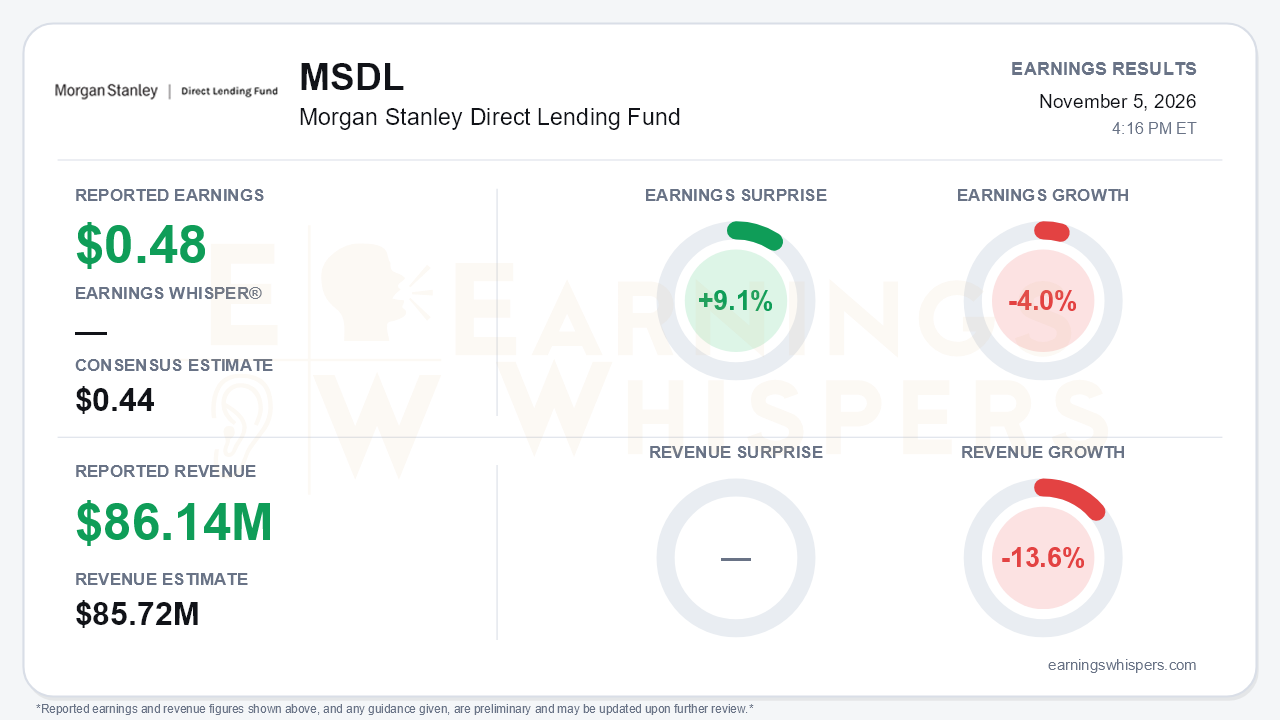
Morgan Stanley Direct Lending Fund (NYSE: MSDL) reported net investment income of $0.48 per share for the third quarter, beating the $0.44 consensus by 9.1%. Total investment income of $86.14 million came in 0.5% above expectations. Both lines still shrank from a year ago: earnings fell 4.0% and revenue dropped 13.6%. The headline beat is the least important part of the quarter. MSDL paired a meaningful shareholder-friendly fee cut and a new supplemental dividend with its worst credit and NAV quarter of the year. That is the central tension. The income story is getting structurally better for 2027 just as the asset base is eroding.
The quality of the beat deserves scrutiny. NII rose to $0.48 from $0.45 in Q2, but not because the portfolio earned more. Total investment income actually slipped to $86.1 million from $88.8 million, reflecting new non-accruals and lower non-recurring revenue. The improvement came on the expense side. Income-based incentive fees collapsed to just $441,000, compared with $9.3 million a year earlier, because the incentive-fee cap and look-back kicked in. Management acknowledged the distortion and put "clean" NII in the low-to-mid 40s cents. On a GAAP basis, the quarter was a loss of $0.32 per share, versus a $0.09 gain in Q2 and $0.32 of positive earnings a year ago. The swing reflects $38.2 million of realized losses and $29.4 million of unrealized depreciation. NAV per share fell 3.8% to $18.76 from $19.50. That extends a steady slide from $20.26 at the end of 2025, and the decline now outpaces what the regular $0.45 dividend returns each quarter.
The credit detail on the call explains the losses. The Bright Pet (AMCP Pet Holdings) restructuring handed ownership to the lender group and produced the quarter's largest NAV hit. Three new non-accruals (Any Hour, LogRhythm and FPG Intermediate Holdco) added $17.2 million at cost. Non-accruals now span eleven companies and 3.4% of the portfolio at cost. Other credit measures also weakened:
- Risk-rated 1-2 assets slipped to 93.4% from roughly 95%.
- Weighted average LTV rose to 42.4% from about 39%.
Management's tone shifted from describing credit as "broadly stable" in Q2 to attributing problems to company-specific execution and integration missteps at acquisitive borrowers. It declined to call a peak in non-accruals and noted another restructuring already underway in Q4. Meanwhile, the portfolio is shrinking. Fair value fell to $3.43 billion as fundings halved to $75 million against $141 million of repayments. Leverage still ticked up to 1.25x because equity eroded faster than assets.
The forward-looking levers are real, though, and the call preserved a credible earnings story for 2027:
- **Fee cut:** Effective January 1, the base management fee drops to 0.75% from 1.00% and the incentive fee to 15% from 17.5%. Management sized the benefit at about 3 cents of quarterly NII per share.
- **Capstone JV:** The joint venture is now about 65% called, up from 52% in Q2 and 47% in Q1. Management expects roughly 4 cents of additional quarterly NII at full ramp by mid-2027.
- **Spreads and rates:** New-deal median spreads widened to 538 basis points from 475, with lower leverage and more sponsor equity. Management expects the September Fed hike to lift floating-rate income starting in Q4.
- **Supplemental dividend:** A new formulaic payout returns 50% of NII above the $0.45 regular dividend, starting with 1.5 cents.
- **Refinancing:** The February 2027 maturity is pre-funded with $350 million of 6.1% notes.
The risks cut the other way. The same Fed hike is a headwind to sponsor M&A, exits and borrower interest coverage. Management also flagged AI spending and rising cloud costs as near-term pressure on software borrowers' margins.
The market has been skeptical. Shares trade at $14.11, down 8.4% since the open following the August report and 5.5% below the 200-day moving average of $14.93. That is roughly 75% of NAV, a discount wide enough that the company's Q3 buybacks, averaging $15.24, were executed well above today's price. Investor sentiment remained negative and edged slightly lower, to -0.41 from -0.39. The change is modest, but it signals that the fee cut and supplemental dividend did not meaningfully shift expectations heading into the print.
That reaction is defensible. The fee reductions and JV ramp could plausibly add about 7 cents of quarterly NII over the next several quarters. That would more than offset the expected normalization from the flattered $0.48. But bears have legitimate ammunition: NII gains are worth little if NAV keeps losing 30 to 75 cents per quarter to restructurings. Management's own reluctance to call a peak in non-accruals leaves that question open.
The bottom line is that MSDL delivered a headline beat of modest quality alongside genuinely shareholder-friendly structural changes. The defining number this quarter was the 3.8% NAV decline, not the $0.48 of NII. Until credit losses stabilize and the portfolio stops shrinking, the discount to book and the soft sentiment reading look more like a reasonable response to deteriorating asset quality than a mispricing.
Read our earnings preview for Morgan Stanley Direct Lending Fund: https://www.earningswhispers.com/article/MSDL/22341
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-05 | |
| Oct-28 | |
| Oct-27 | |
| Oct-05 | |
| Aug-31 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Jul-06 | |
| Jun-29 | |
| May-07 | |
| May-07 | |
| May-06 | |
| Apr-06 |
