Outfront Faces A Post-World Cup Test As Transit Strength Meets Rising Spending
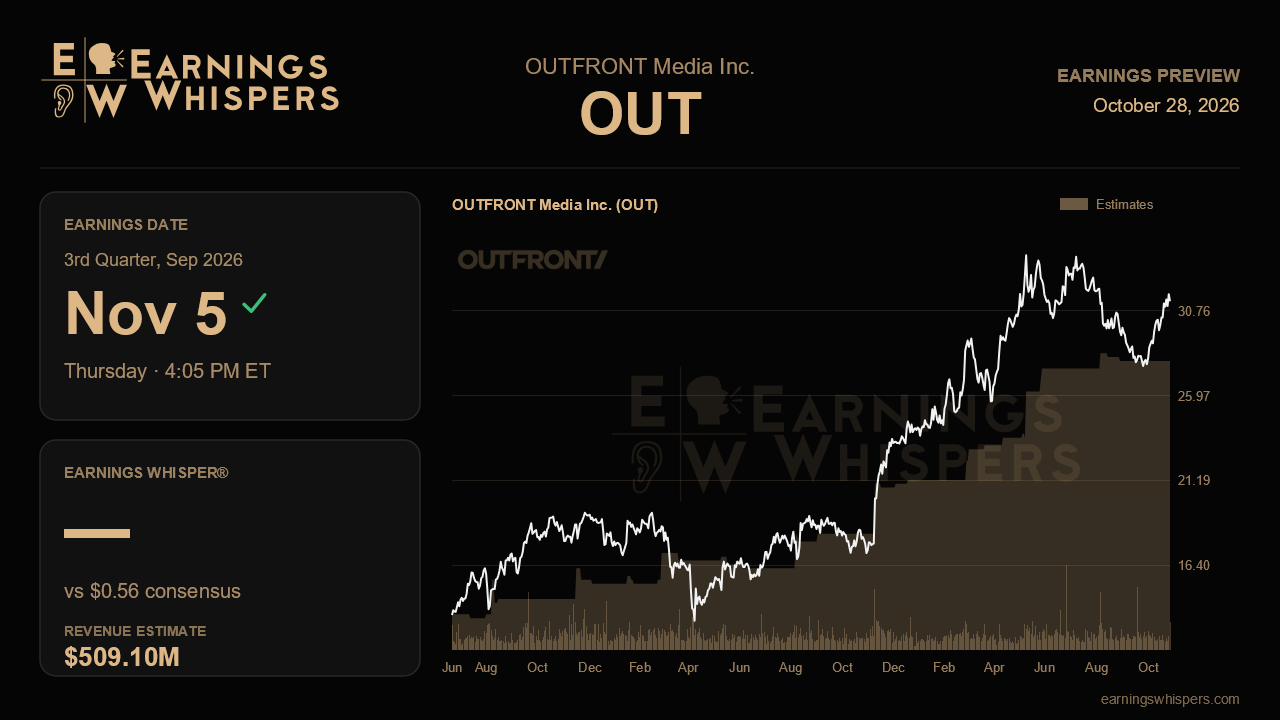
Outfront Media heads into its third-quarter report with an unusual problem: its last quarter may have been too good to repeat. A World Cup-fueled 14% revenue jump, a second straight increase to full-year AFFO guidance and a 10% dividend hike made the summer call the most upbeat in a year. The November 5 release, due after the close, will show how much of that momentum belongs to the business and how much belonged to one-time events.
Wall Street expects earnings of $0.56 per share on revenue of $509.1 million. That revenue figure would be about 8.9% higher than a year ago, a slowdown from the 14% pace of the second quarter. The slowdown is expected, though. Management guided to high-single-digit revenue growth for the quarter, with transit up about 20% and billboard up mid-single digits, so consensus sits near the top of that outlook. The earnings estimate is more telling. It is essentially flat with last year's $0.57 and well below the prior quarter's $0.68. Analysts appear to have absorbed management's warning that costs will climb.
That warning is the main swing factor. Management said SG&A would grow faster than revenue for the rest of 2026 as it adds programmatic sales staff, data and analytics capability and tooling, including the hire of a Chief Data Officer. Its refinancing also replaced 5% notes with 6% notes due 2034, lifting interest costs. Neither is a demand problem, but both reduce the profit from each extra dollar of sales. If costs rise only modestly faster than revenue and adjusted OIBDA margins hold up, the spending will look like disciplined reinvestment. A sharper squeeze would raise doubts about whether the full-year AFFO target, now low-20s percent growth off a $338 million 2025 base, still has room to spare.
Transit is where the growth story will be tested. Revenue there accelerated to 32% last quarter, led by a 48% surge from the New York MTA. Guidance of roughly 20% growth for the third quarter implies a clear slowdown, so investors should look at the quality of the result, not just the headline figure. Management also reversed an earlier expectation that MTA revenue would exceed its $161 million minimum annual guarantee and switch to revenue sharing in the fourth quarter. It now plans to spread the guarantee evenly over time for the foreseeable future. That removes a possible year-end boost, which means future upside has to come from advertising demand rather than contract accounting.
The World Cup is the other key question. Management expected about $16 million more from the tournament in the third quarter, and it said roughly half of the event's total revenue came from new business. Evidence that first-time World Cup advertisers are returning would support the bull case. Further gains in billboard yield, which rose 12% last quarter, and in programmatic sales, which grew about 50% and now make up a fifth of digital revenue, would show that pricing power reaches beyond special events. Early comments on the New York Jets partnership and on acquisitions, now possible with leverage near 4.0x, could add to the story.
The market has turned more skeptical. Bullish sentiment has fallen to 15.7% from 47.8% before the last report, and the stock has slipped 2.6% since then, slightly behind the broader market. At $31.30, shares remain above their 200-day moving average but sit well below the post-earnings high of $33.54. That leaves a modest bar for a positive surprise.
The central question is simple. Can Outfront show that demand stays strong once the World Cup lift fades, while keeping its heavier spending from eroding the AFFO growth that justified two guidance increases and a higher dividend? A reaffirmed or raised full-year outlook would answer it.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-23 | |
| Oct-21 | |
| Sep-02 | |
| Aug-31 | |
| Aug-10 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-29 | |
| Jul-14 | |
| Jun-03 | |
| May-28 |
