OUTFRONT Media Edges Past Estimates And Lifts AFFO Outlook Again, But An SG&A Surge Is Eating The Billboard Upside
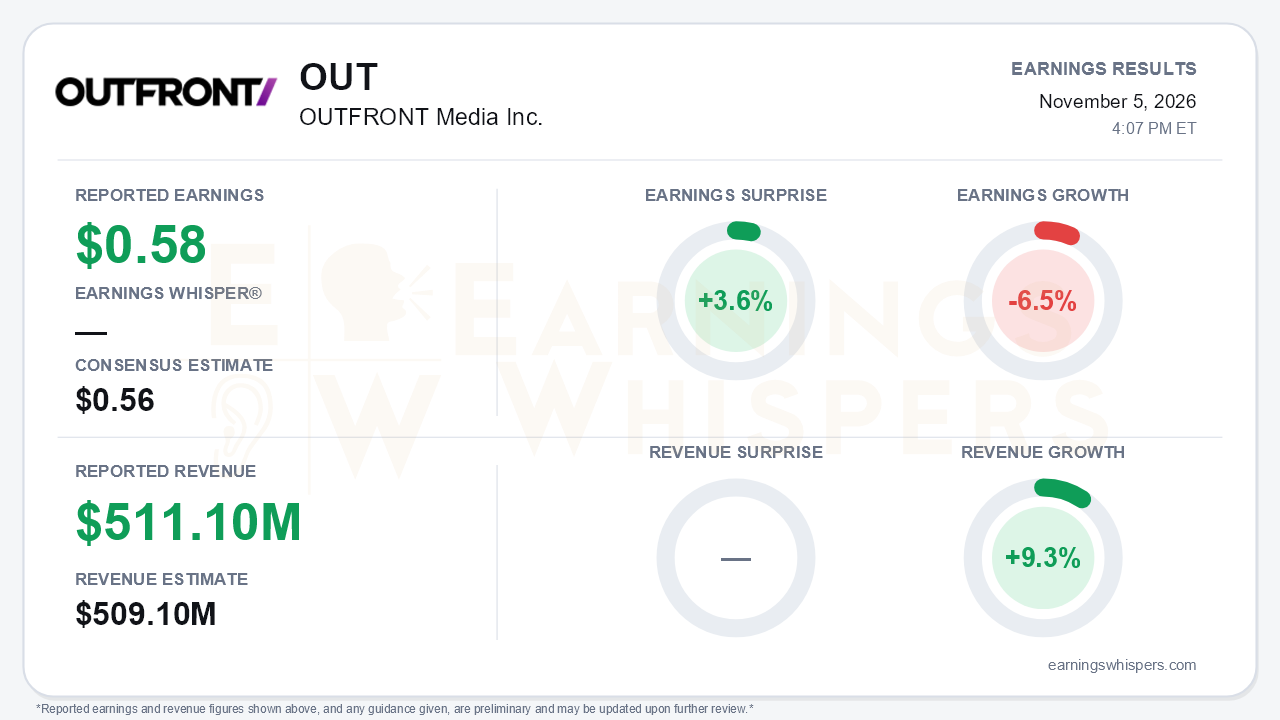
OUTFRONT Media delivered a modest beat that came with a fourth consecutive increase to its full-year outlook. Third-quarter earnings of $0.58 per share topped the $0.56 consensus by 3.6%, and revenue of $511.1 million edged past the $509.1 million estimate by 0.4% while growing 9.3% year over year. Management said it now expects full-year AFFO growth of roughly 25%, up from low-20s after the second quarter, and it called for double-digit revenue growth in the fourth quarter. The central tension is that the top line is strengthening while profit conversion is weakening sharply. On Earnings Whispers' normalized basis, earnings fell 6.5% from a year ago. That decline sits against GAAP diluted EPS that rose to $0.36 from $0.29 and recast AFFO that grew 5% to $102.9 million. The company's late-2025 change to its AFFO methodology complicates the year-over-year comparison, and investors should not read the quarter as clean per-share growth.
The quality of the quarter deserves scrutiny below the revenue line. Total revenue grew more than $43 million, but Adjusted OIBDA rose only $8.1 million, or 5.9%, to $145.3 million. The consolidated margin slipped to 28.4% from 29.3%. The main cause was SG&A, which jumped 23.1% to $129.5 million on:
- higher compensation;
- professional fees, including software and technology spending;
- client entertainment;
- a larger bad-debt allowance.
The billboard segment shows the problem most clearly. Billboard revenue rose 5.9% to $373.7 million, helped by yield gains and FIFA World Cup spending, yet segment Adjusted OIBDA rose just $0.2 million and margin fell to 37.3% from 39.5%. Transit carried the quarter. Revenue there climbed 20.4%, and Adjusted OIBDA jumped 84.1% to $28.9 million, lifting segment margin to 21.4% from 14.0%. Corporate expense, on the adjusted basis the company reports, rose 29.1%.
The call preserved a credible growth story, but the momentum metrics cooled noticeably. Consolidated OIBDA growth slowed to about 6% from 29% in the second quarter, and AFFO growth slowed to 5% from 45%. Several key revenue lines also lost speed versus the second quarter:
- digital revenue growth eased to 14% from 23%;
- programmatic growth fell to 16% from roughly 50%;
- MTA growth dropped to 22% from 48%;
- enterprise growth slowed to 6% from 12%.
Against that, billboard yield rose 9% to $3,318 per month. Fourth-quarter guidance calls for transit above 20% and billboards in the mid-single digits, even as the FIFA contribution fades; it fell to roughly $15 million in the third quarter from about $35 million in the second. Management framed the SG&A step-up as investment tracked against returns. Still, it guided fourth-quarter SG&A plus corporate expense up high teens, so margin pressure is part of the plan rather than a one-off.
The forward catalysts are real:
- Net leverage fell to 3.9x, below the 4x-5x target range, from 4.7x at year-end, and management signaled more active M&A.
- Capex was trimmed to about $85 million and interest expense guidance lowered to just over $140 million, both supporting AFFO.
- Political spending is tracking ahead of the prior midterm cycle.
- Early first-quarter 2027 pacing was described as "pretty good."
- The IRL Nav self-serve platform is set to open to small advertisers in 2027.
Bears have legitimate ammunition as well. Management flagged tough 2027 comparisons in transit, the MTA and AI-advertiser spending, along with more modest media inflation next year. The rising bad-debt allowance appeared in both segments, and the nine-month provision roughly doubled to $8.7 million. The release also disclosed that OUTFRONT no longer expects to recoup current or future MTA equipment deployment costs, a reminder of how economically demanding that contract remains.
The market setup is more complicated than the surprise implies. Investor sentiment dropped from 0.48 to 0.17 heading into the report, a meaningful cooling, though it stayed in positive territory. Shares traded at $32.48 just before the release, up only 1.1% from the open after the August report. That leaves them 3.1% below the inter-earnings high of $33.54, which was set the day after last quarter's release. The stock had fallen to $27.48 on October 1 and recovered 18.2% from that low, so it entered this report after a solid rebound. Momentum and AVWAP trend readings are positive, while the price trend is neutral.
The bottom line is that OUTFRONT is executing on demand and the balance sheet. The company beat on revenue, raised AFFO guidance again and created room for acquisitions. However, the operating leverage that powered earlier quarters has stalled because SG&A is absorbing most of the incremental revenue, especially in billboards. Investors who believe the reinvestment will pay off in 2027 have support from the guidance. Those focused on slowing digital and MTA growth, tougher comparisons and shrinking margins will see the normalized earnings decline as the more telling number.
Read our earnings preview for OUTFRONT Media Inc.: https://www.earningswhispers.com/article/OUT/22355
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-23 | |
| Oct-21 | |
| Sep-02 | |
| Aug-31 | |
| Aug-10 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 |
