After Two Guidance Raises, Omada Must Prove Its Second-Half Slowdown Is Only By Design
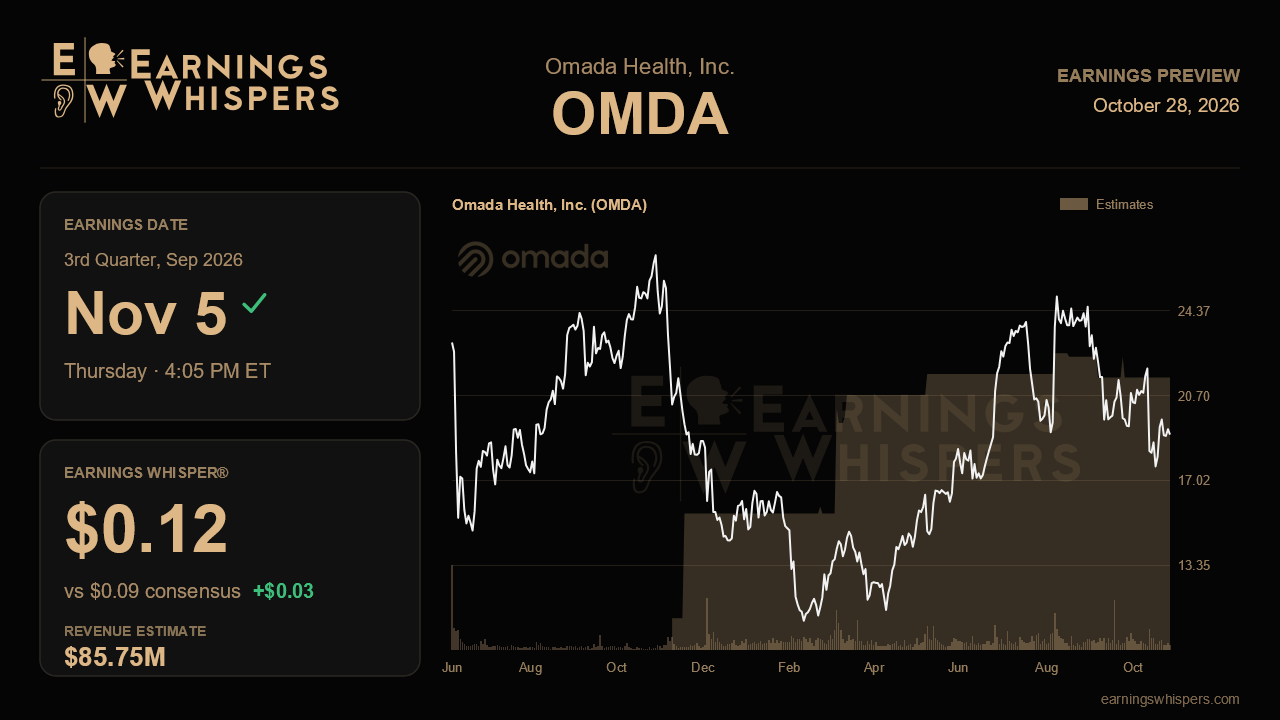
Omada Health heads into its third-quarter report with an unusual setup: the business just delivered the best quarter in its history, management has raised its full-year outlook twice, and yet the stock has slipped since that report. The tension is simple. Management told investors the second half would cool off by design after an exceptional first half pulled enrollments forward. This report is the first real test of whether that slowdown is as orderly as promised, or whether it is the start of something less comfortable.
Wall Street expects non-GAAP earnings of $0.09 per share on revenue of about $85.8 million when Omada reports after the close on November 5. That revenue figure would represent roughly 26% growth from the $68.0 million posted a year ago, still a strong pace, but a clear step down from the 43% growth of the second quarter. It also implies a modest sequential dip from the $87.8 million reported last quarter, which fits management's message of a more measured back half. The Earnings Whisper of $0.12 sits a few cents above consensus, a meaningful gap for a company only recently crossing into profitability, and a sign that the informal bar is higher than the published one.
Guidance frames the stakes. Omada lifted its 2026 revenue outlook to $334 million to $340 million, up from $322 million to $330 million a quarter earlier and $312 million to $322 million at the start of the year. Adjusted EBITDA guidance climbed in parallel to $21 million to $27 million. Notably, the full-year consensus of roughly $327 million sits below the bottom of management's range, suggesting the Street remains skeptical or simply has not caught up. Either way, a company that has beaten and raised twice has room to do it again if second-half enrollment holds up. Management also flagged that implied second-half EBITDA margins would fall back toward 7% from 12% in the second quarter as earlier hiring annualizes, so a margin step-down by itself should not alarm anyone. A sharper decline would.
The operating details matter more than the headline numbers. Gross margin hit a record 73% on a GAAP basis last quarter, and management indicated the business could run above its 70% long-term target, a point it planned to address at its September investor day. This is the first report since that event, so holding gross margin in the low 70s would validate any lifted framework. Membership, which reached 1.1 million, should keep climbing, and the diabetes and hypertension books, which carry the highest pricing and longest tenure, need to keep outgrowing the overall base. Updates on the second PBM channel, which was tracking ahead of plan, and early commentary on 2027 catalysts, including the HCSC expansion covering about 1.5 million lives, the first prescribing customer and the standalone cholesterol track, will shape how investors view next year.
The risk worth monitoring is GLP-1 coverage. Employers were split heading into 2027, with some expanding and others dropping weight-loss benefits, and any shift in that balance during the selling season could affect next year's enrollment math. The CEO transition, with Wei-Li Shao taking the top job in January, adds a layer of attention to tone.
Sentiment has grown slightly more bearish, moving to 24.7% bearish from 22.2% before the last report, and shares have lagged the S&P 500 by about 8 percentage points. At $19.01, the stock sits above its 200-day moving average but much closer to the $17.48 low of its post-earnings range than the $25.45 high. That leaves room for relief if Omada shows the deceleration is controlled. The central question is whether growth is slowing only because of tough comparisons and pulled-forward enrollment, or because demand itself is cooling.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-20 | |
| Oct-13 | |
| Sep-10 | |
| Sep-09 | |
| Aug-26 | |
| Aug-07 | |
| Aug-06 | |
| Jul-23 | |
| Jul-23 | |
| Jul-15 | |
| Jul-13 | |
| May-27 | |
| May-07 |
How This Eli Lilly-Tied IPO Stock Fared In Its First Quarter
OMDA OMDA -9.63%
Investor's Business Daily
|
| May-07 |
