Omada Health Beats Consensus But Misses The Whisper As Third Guidance Raise Collides With Slowing Growth And A Cloudier 2027
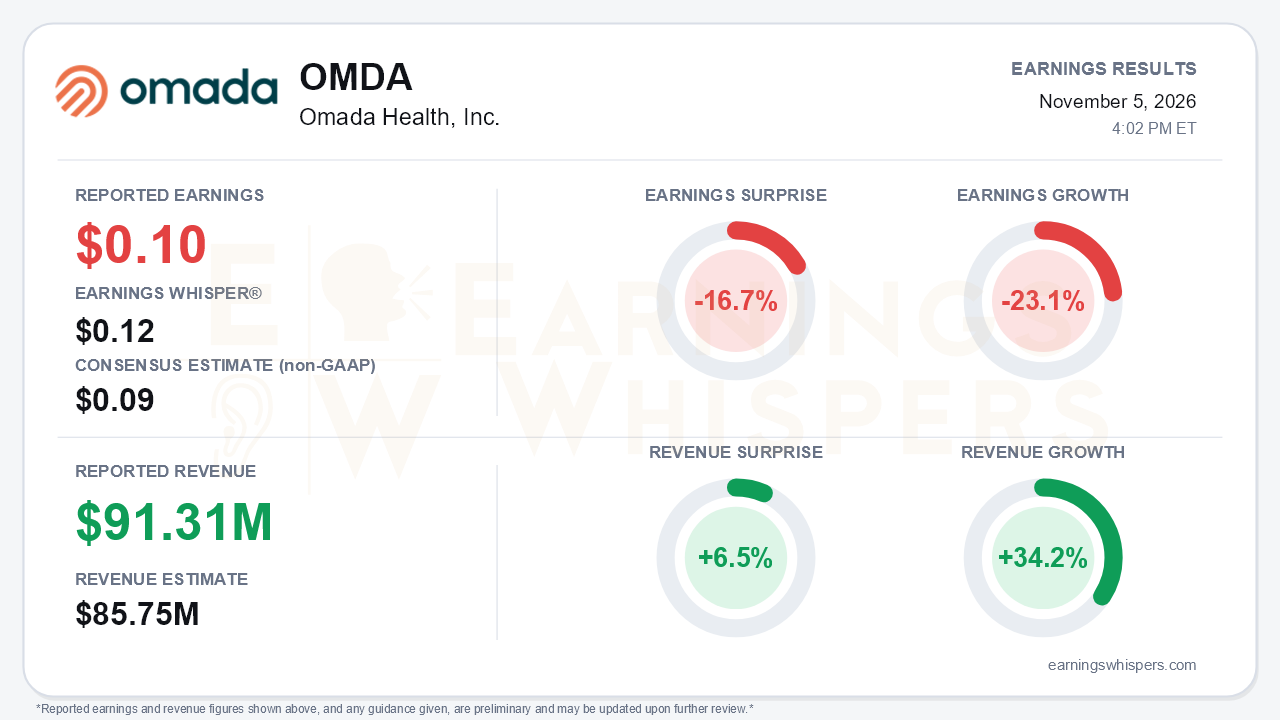
Omada Health (NASDAQ: OMDA) delivered its most profitable quarter as a public company, yet the stock still faces a harder setup than the headline implies. Third-quarter earnings of $0.10 per share topped the $0.09 consensus but fell short of the $0.12 Earnings Whisper number, a 16.7% miss against the expectation that mattered most. Revenue of $91.31 million beat the $85.75 million consensus by 6.5% and grew 34.2% year over year. Management raised full-year guidance for the third straight quarter. On Earnings Whispers' normalized basis, earnings fell 23.1% year over year, while on a GAAP basis the company swung from a $3.2 million net loss to $6.6 million of net income. That divergence reflects different comparison bases, not a deterioration in reported profitability. The central tension is plain: profitability is inflecting sharply just as top-line growth is normalizing and visibility into 2027 is getting murkier.
The quality of the margin story is genuine. GAAP gross margin jumped to 76% from 66% a year ago, and non-GAAP gross margin hit a record 78%, up from 74% in Q2 and 64% in Q1. The improvement came mainly from services. Services revenue rose 35% while services cost of revenue grew only 4%. The hardware loss also narrowed, with hardware cost exceeding hardware revenue by about $2.7 million versus roughly $5.2 million a year ago. Operating income reached $4.8 million against a $2.5 million loss, and adjusted EBITDA climbed to $12.4 million, a 14% margin. Two caveats temper the picture. Roughly $2.0 million of interest income padded the bottom line. Share-based compensation also rose to $5.9 million from $3.5 million. Free cash flow was a modest $2.5 million through nine months, and about $20 million in option-exercise proceeds did much of the work lifting cash to $243 million.
The call underscored that the unit economics are improving faster than the growth rate. Trailing 12-month cost of revenue per member fell to an all-time low of $81, down from $94 a year earlier. Revenue per member rose to $294 on a richer diabetes and hypertension mix. Retention improved to 58% from 43% in Q4 2024, and average tenure reached a record of about two years and four months. Management credited real-time enrollment, replacing weekly batching, with lifting enrollment yield about 10% year to date and driving the quarter's upside. The CFO now references an 80% long-term gross margin target, up from 70%-plus. The deceleration, however, is unmistakable:
- **Revenue growth** slowed to 34% from 43% in Q2 and 42% in Q1.
- **Member growth** cooled to 36% from 45% and 51%.
- **Fourth-quarter outlook:** guidance implies Q4 revenue below Q3 and a slight sequential dip in total members.
- **Q4 adjusted EBITDA** is set to moderate as Omada hires in R&D and staffs care teams for 2027 launches.
Forward catalysts are real but back-end loaded. The HCSC fully insured expansion, covering about 1.5 million lives, goes live January 1, 2027, and will phase in through the year. A large financial institution signed on for GLP-1 FlexCare and launched in-year. Peer-reviewed data showed 6% weight loss at 12 weeks on the GLP-1 care track versus 3.3%. Bears have legitimate ammunition, though:
- **Selling season:** GLP-1 coverage deliberations and rising healthcare costs have pushed the season deeper into Q4 than usual.
- **2027 visibility:** management declined to quantify 2027 covered lives or FlexCare signups.
- **Employer coverage:** reports point to declining employer GLP-1 coverage heading into 2027.
- **Pricing pressure:** outcome-based performance guarantees are becoming more common in RFPs, with competitors marketing 100% of fees at risk.
- **Leadership change:** Wei-Li Shao becomes CEO on January 1.
- **Customer concentration:** related-party revenue accounted for roughly $58 million of the quarter's $91 million.
Investor sentiment entered the report mildly negative and essentially unchanged, edging from -0.22 to -0.23. Repeated guidance raises have not won over the crowd. Shares closed at $19.43 before the release, down 6.1% from the open after the August report. They have given back much of the late-August spike to $25.45 and sit 23.7% below that inter-earnings high. The stock has recovered 11.2% from its October 16 low of $17.48 and trades about 9.7% above its 200-day moving average of $17.72. Short-term momentum readings have turned positive, but AVWAP remains negative, consistent with a stock still working off its post-August reversal.
The bottom line is that Omada's quarter strengthened the profitability case well beyond what the 2026 guidance trajectory implied a year ago. Adjusted EBITDA guidance has more than quadrupled at the midpoint since the initial outlook. The miss versus the whisper, decelerating member growth, and a soft Q4 setup shift the debate toward 2027 bookings, which management has not yet sized. Until the extended selling season resolves and HCSC begins contributing, the margin story is credible but the growth story requires faith.
Read our earnings preview for Omada Health, Inc.: https://www.earningswhispers.com/article/OMDA/22353
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-20 | |
| Oct-13 | |
| Sep-10 | |
| Sep-09 | |
| Aug-26 | |
| Aug-07 | |
| Aug-06 | |
| Jul-23 | |
| Jul-23 | |
| Jul-15 | |
| Jul-13 |
