Playboy's Turnaround Faces Proof Test As Stock Slides Despite Profit Inflection
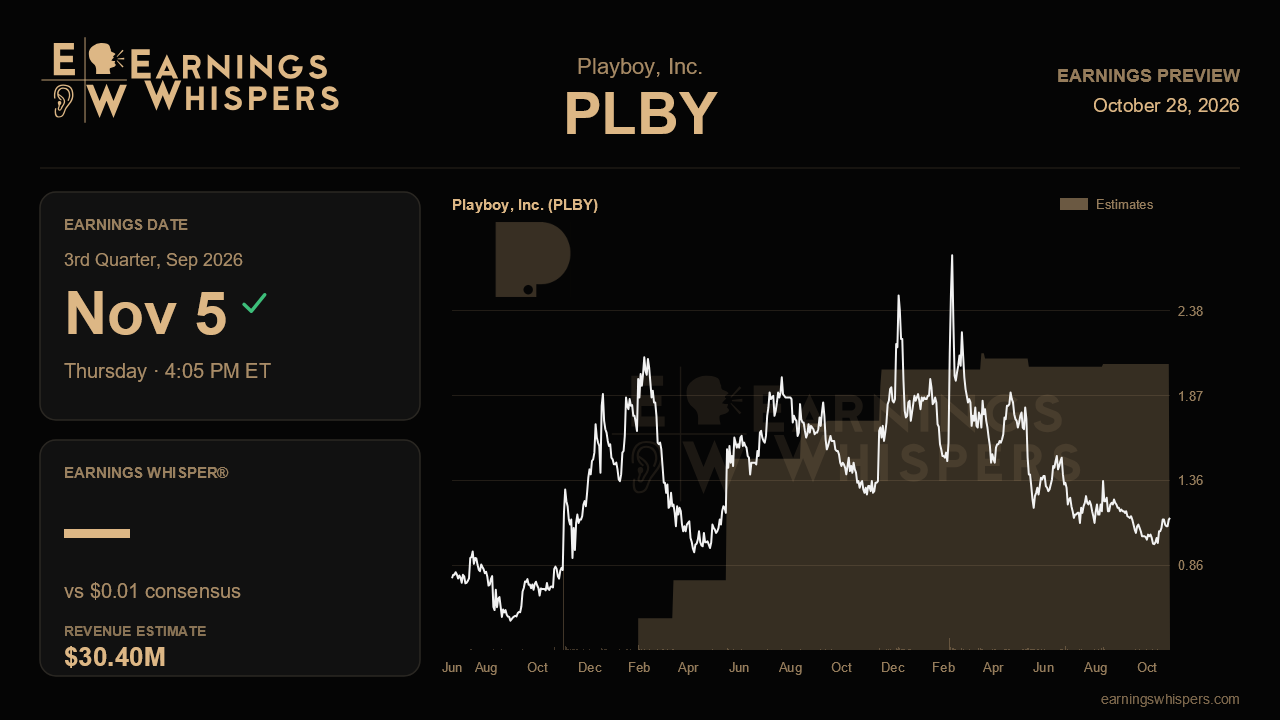
Playboy enters its third-quarter report with an awkward disconnect. Last quarter management described the clearest evidence yet that its multi-year turnaround was producing real profits, positive cash flow and steady deleveraging, and it announced a share buyback on top of that. The stock has since fallen about 25%, trailing the S&P 500 by roughly 24 percentage points. When the company reports after the close on November 5, the question is whether the operating story still holds up or whether the market saw cracks that the narrative glossed over.
The Street's bar is modest. Analysts expect earnings of about a penny a share on revenue of $30.4 million. That would be roughly 5% revenue growth from $29.0 million a year ago, while EPS would fall from two cents. The company has not issued formal guidance, so consensus is effectively a bet that the business can hold the $31.2 million and roughly breakeven bottom line it posted last quarter. Revenue growth of about 5% would be a step down from the nearly 11% pace of the second quarter. That makes the top line the more telling number, since a penny of EPS gives management little room either way.
Honey Burdette carries much of the weight. The lingerie brand grew 18% last quarter to $19.5 million, with total comps up 15% and every region positive. Retail now faces tougher comparisons after several years of double-digit gains, so growth increasingly depends on the online channel. Management has also cooled on opening five new U.S. stores, citing expensive rents, and is leaning toward e-commerce. That reasoning is defensible, but it puts more pressure on digital growth. Double-digit comps despite the harder comparisons would support the bull case. A sharp slowdown would suggest last quarter marked a peak. The September Honey Burdette x Playboy collaboration launch should give an early read on whether the two brands can cross-sell.
Licensing is the other swing factor. It returned to modest growth of 2% last quarter despite a roughly $200,000-per-quarter drag from the owner-operator transition in China. Signs that the drag is fading, or that new licensing chief Crystal Bach is filling the pipeline, would ease worries that the core royalty business has stalled. The newer media efforts carry the most hope and the least proof. Management pointed to July as the best month yet for Playboy.com subscriptions, sponsorship deals scheduled to book revenue this quarter, and a paid-voting contest with about 2.5 times the revenue of its predecessor. This report should show whether those streams produce visible dollars. The risk is that management steps up spending to accelerate media before revenue arrives, which would weigh on adjusted EBITDA that reached about $7 million, or a 22% margin, last quarter.
Sentiment has improved even as the share price has fallen. Bearish readings have eased to 16.4% from 32.2% before the last report, so pessimism is less entrenched. The chart tells a weaker story. At $1.13 the stock sits well below its 200-day moving average of $1.45 and near the bottom of its post-earnings range of $0.95 to $1.60. Notably, it trades only modestly above the $1.05 price at which the company is repurchasing roughly 15% of its shares. Updates on buyback payments, debt reduction toward the $108 million target, and legal costs, which are still eating about $700,000 a quarter, will matter for the equity case.
Ultimately, this report needs to show that the second quarter was a durable baseline rather than a high-water mark. If Honey Burdette sustains strong growth against tougher comparisons, licensing holds steady, and the early media revenue arrives without eroding margins, the stock's slide will look like a disconnect from fundamentals. If any of those pillars wobble, the market's skepticism may prove warranted.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-22 | |
| Oct-19 | |
| Sep-30 | |
| Sep-21 | |
| Aug-11 | |
| Aug-10 | |
| Aug-07 | |
| Jul-27 | |
| Jul-22 | |
| Jun-29 | |
| Jun-22 | |
| Jun-11 | |
| Jun-04 | |
| May-29 |
